分类: business

  • Fed has ‘work to do’ if price rises don’t ease for Americans, Warsh says

    Fed has ‘work to do’ if price rises don’t ease for Americans, Warsh says

    The annual Jackson Hole Economic Policy Symposium, a high-profile gathering that draws central bankers, senior government officials, and leading academics from across the globe to debate pressing economic challenges, kicked off this week with a stark warning from the newly appointed leader of the U.S. Federal Reserve about persistent inflationary pressures.

    Kevin Warsh, who was tapped by President Donald Trump to lead the central bank in May, used his first keynote address at the Wyoming-based conference to lay out his policy stance, noting that while summer inflation readings came in better than many forecasters had projected, the data has not yet shown that underlying cost-of-living pressures have meaningfully improved for U.S. households.

    Warsh emphasized that with annual inflation still running well above the Fed’s long-standing 2% target – the latest official data puts 12-month price growth at 3.4% as of July – the central bank’s top priority right now must be taming rising prices. “Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do,” he told attendees.

    While Warsh explicitly cautioned that his remarks should not be interpreted as binding forward guidance for future rate decisions, his comments have immediately shifted market expectations for the Fed’s upcoming September 15-16 policy meeting, where officials will set the federal funds rate. In addition to signaling that further tightening remains on the table if inflation does not cool fast enough, Warsh also argued that the Fed’s post-2008 practice of providing explicit forward guidance on future rate moves has outlived its usefulness.

    “Oversharing policy deliberations and overcommitting to future decisions can lead markets, businesses, and households astray,” he said, adding that the practice also limits the Fed’s “freedom to make the right calls when it’s time to decide.”

    The Fed has held interest rates steady at a range of 3.5% to 3.75% for five consecutive meetings through July, as officials balanced inflation concerns against broader economic uncertainty. Persistent tensions between the U.S. and Iran have driven a sharp surge in global oil prices in recent months, keeping upward pressure on energy and broader consumer costs.

    Following Warsh’s Jackson Hole speech, CME Group data shows that bond and interest rate markets have sharply increased their bets on a September rate hike. Analysts at Capital Economics noted that Warsh delivered a “far clearer – and hawkish – message” than expected, leaving the door open to an earlier rate increase than markets had previously priced in.

    “Hikes are not guaranteed, but Warsh is now at least suggesting he is on board with them if economic growth remains strong and monthly core Personal Consumption Expenditures price growth remains a bit too firm,” the firm’s analysts wrote in a note to clients.

    Rate hikes work to cool inflation by raising borrowing costs for consumers and businesses, encouraging lower spending that in turn eases upward pressure on prices. While higher rates deliver better returns for savings accounts, they also push up costs for mortgages, auto loans, and credit card debt, and increase the interest payments the U.S. government owes on its national debt.

    In a development that underscores the growing fiscal pressure facing the U.S., rising interest payments have now pushed the total national debt past the $40 trillion mark, more than doubling over the past decade across both the Trump and Biden administrations. Data from the Congress Joint Economic Committee shows the debt is growing at a staggering rate of roughly $90,000 per second, or $7.8 billion per day.

    Treasury Secretary Scott Bessent recently announced a plan to buy back more government debt in an effort to lower overall borrowing costs, but market optimism around the measure faded quickly after the announcement.

    The Fed’s September rate decision will also carry significant political weight, as the U.S. approaches upcoming mid-term elections, with voters across the country already listing affordability and rising living costs as one of their top policy concerns. President Trump, who appointed Warsh to lead the Fed, has a well-documented history of criticizing previous Fed chair Jerome Powell, repeatedly pressing for steep rate cuts and arguing that rate hikes hold back U.S. economic growth. Analysts and political observers will be closely watching Trump’s reaction to whatever decision the Fed makes next month.
  • Tech stocks lift Australian sharemarket to cap winning week, tech giant Dicker Data rises 20pc

    Tech stocks lift Australian sharemarket to cap winning week, tech giant Dicker Data rises 20pc

    The Australian Securities Exchange (ASX) has closed out a positive trading week, wrapping up with a technology-driven rally on Friday that pushed the benchmark index into positive territory even as ongoing concerns about potential interest rate hikes simmer among investors.

    Upbeat quarterly results from major U.S. tech giants Nvidia and Salesforce spilled over into overnight trading on Wall Street, and that momentum carried over to Australia’s domestic tech sector, which led all industry gains for the day. By the closing bell, the ASX 200 benchmark index climbed 0.6% to settle at 9092.3 points, with nine out of 11 tracked industry sectors finishing in positive territory. For the full week, the index logged a solid 0.37% gain, arriving at the final stretch of the quarterly corporate earnings reporting season.

    A number of individual stocks posted dramatic single-day gains. Dicker Data, a leading Australian IT software and hardware provider, saw its share price surge 20.7% to $15.30 after the firm reported a 37% jump in first-half net earnings. Fiona Brown, the company’s managing director, attributed the strong performance to growing market opportunities driven by global enterprise technology refresh cycles, rising corporate investment in artificial intelligence infrastructure, and sustained high demand for software and cybersecurity solutions.

    Other tech stocks also posted significant gains. SaaS firm Readytech Holdings recovered 8.8% in Friday trading, trimming its year-to-date loss to 37% amid a broader sector-wide pullback for software-as-a-service stocks. Accounting software provider Xero notched its best single-day performance in two months, climbing 4.8% to $85.64, while Technology One gained 3.5%, and WiseTech, NEXTDC and LIFE360 all posted gains between 2.1% and 2.7%. In the resources sector, Pantoro Gold rose 5.9% and integrated lithium developer Vulcan Energy gained 5% to rank among the day’s top movers.

    Not all stocks ended the day in positive territory, however. Property exchange platform PEXA plummeted 17.4% to hit an all-time low in its five years of public trading on the ASX, after the company released full-year results that included guidance forecasting a sharp slowdown in future earnings driven by declining homeowner sales activity in a cooling property market.

    Investment firm WAM Capital also faced severe volatility, with shares dropping 18.5% to reach a 16-year low. The company reported an after-tax operating loss of $125.9 million for the 2024 financial year, a sharp reversal from the $219.6 million profit it posted in the prior year. It also announced a halved partially franked dividend, ending six consecutive years of dividend payouts that exceeded realized annual profits.

    Other notable single-day moves included Virgin Australia, which announced its first dividend since relisting on the exchange. Even though the airline reported a 13% uplift in annual earnings, the announcement failed to attract buyer interest, and shares dipped 1.4%. Retail giant Harvey Norman fell 1.8% as ongoing weak trade conditions in the United Kingdom weighed on investor sentiment. Jack Cowin, chairman of Domino’s Pizza Australia, purchased an additional $3 million in Domino’s shares this week, just days after the chain reported a full-year net loss of $134.2 million. Cowin stepped down from his role as non-executive chairman on August 5, and Domino’s shares dipped 1% in Friday trading.

    Market analysts have noted rising volatility during the final stretch of this earnings reporting season. Morningstar analysts have adjusted their fair value estimates upward for roughly one-third of the Australian companies they cover this reporting cycle, while cutting valuations for only around 20% of covered firms. Average share price movements on earnings results day currently sit at 6.5% in either direction, a level not far off the all-time high for daily volatility set back in February 2025. “We’re seeing share price volatility pick up again too, little surprise given the smaller stocks cluster in the final week,” Morningstar analyst Lochlan Halloway explained in a research note this week.

    Despite hotter-than-expected domestic inflation data released earlier this week that stoked broader concerns about imminent interest rate hikes from the Reserve Bank of Australia, the interest rate-sensitive ASX 200 still managed to carry through to a weekly gain, underscoring the strength of the tech-driven rally that anchored the end of the trading week.

  • Tanker pays record $5.3 mn to transit Panama Canal: administrator

    Tanker pays record $5.3 mn to transit Panama Canal: administrator

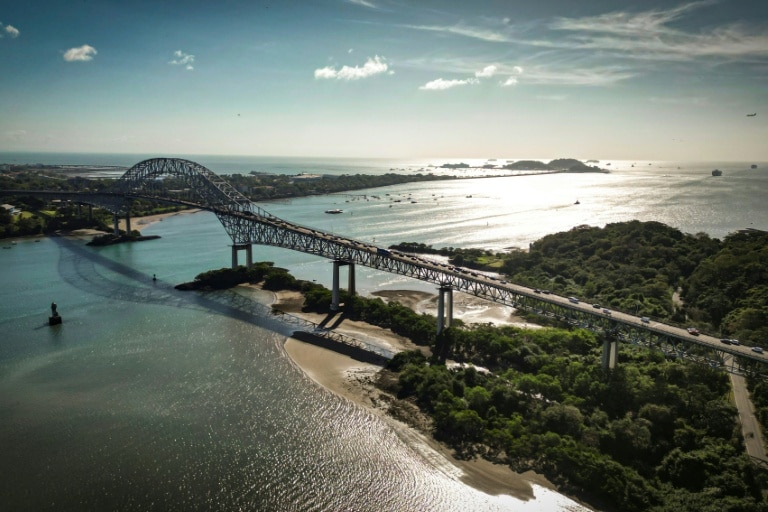
    As a crippling drought driven by the El Niño weather pattern pushes the Panama Canal to implement sweeping capacity cuts, a South Korean energy firm has made global shipping history by paying a record-breaking $5.3 million to secure priority passage for its liquefied petroleum gas (LPG) tanker, the waterway’s leadership confirmed Thursday.

    Ilya Espino de Marotta, deputy administrator of the Panama Canal Authority, shared the details of the unprecedented transaction with Agence France-Presse. The vessel in question, the G. Spirit, is owned by SK Gas, a leading energy company based in South Korea. It completed its transit through the key interoceanic shipping lane on September 1, just two days before new El Niño-related restrictions on daily transits went into effect, Bloomberg reporting confirms.

    The crisis at the Panama Canal comes amid a regional dry spell amplified by El Niño, the cyclical weather phenomenon that warms surface waters across the central and eastern equatorial Pacific, triggering disruptive shifts in global wind and rainfall patterns. This year, El Niño has also helped push global average temperatures to what is on track to be the hottest year ever recorded. On Tuesday, Panama joined a growing list of Central American nations to declare a national emergency over the climate-driven impacts of El Niño, which have sent water levels in the canal plummeting to critically low levels.

    As one of the world’s most vital maritime chokepoints, the Panama Canal accommodates roughly 5% of total global maritime trade, connecting the Atlantic and Pacific Oceans and cutting thousands of miles off travel times for cargo vessels traveling between the two basins. To conserve dwindling water supplies amid the drought, canal authorities have implemented a phased reduction in daily transit capacity: starting September 3, the maximum number of daily vessel transits dropped from 32 to 34, with a further cut to 32 daily transits scheduled for later this month.

    Most vessels reserve transit slots through the canal weeks or months in advance, with unbooked vessels currently facing an average five-day wait to pass through. For shippers in a hurry to move time-sensitive or high-value cargo, however, the canal authority runs a last-minute auction system for priority slots that would otherwise go unfilled. The average winning bid for these auction slots between October 2023 and February 2024 was just under $55,000, a fraction of the record price paid this week.

    This historic transaction marks the second time in months that a high-priced priority transit has made headlines. Back in April, a liquefied natural gas (LNG) carrier paid $4 million to skip the waiting line, as heightened energy demand spurred by the Middle East conflict created urgency for moving vital fossil fuel cargoes through the waterway. The sharply rising cost of priority transits underscores the growing pressure on global supply chains as climate-driven extreme weather disrupts key shipping infrastructure around the world.

  • World shares mostly gain after upbeat results for Nvidia and other tech giants lift US stocks

    World shares mostly gain after upbeat results for Nvidia and other tech giants lift US stocks

    Global equity markets mostly climbed through Friday’s early trading sessions, building on a tech-driven rally from Wall Street triggered by blowout quarterly results from AI powerhouse Nvidia. The upward momentum carried across most major European and Asian benchmarks, even as some individual markets bucked the trend and investors braced for upcoming commentary from the U.S. Federal Reserve.

    In early European trading, Germany’s benchmark DAX index gained 0.6% to close the early session at 26,523.10, while France’s CAC 40 notched a stronger 1.1% increase to 8,408.72. The UK’s FTSE 100 posted a more modest 0.2% uptick, reaching 10,815.07. Futures for U.S. indexes signaled a muted opening ahead: S&P 500 futures slipped 0.1%, while Dow Jones Industrial Average futures edged 0.2% higher.

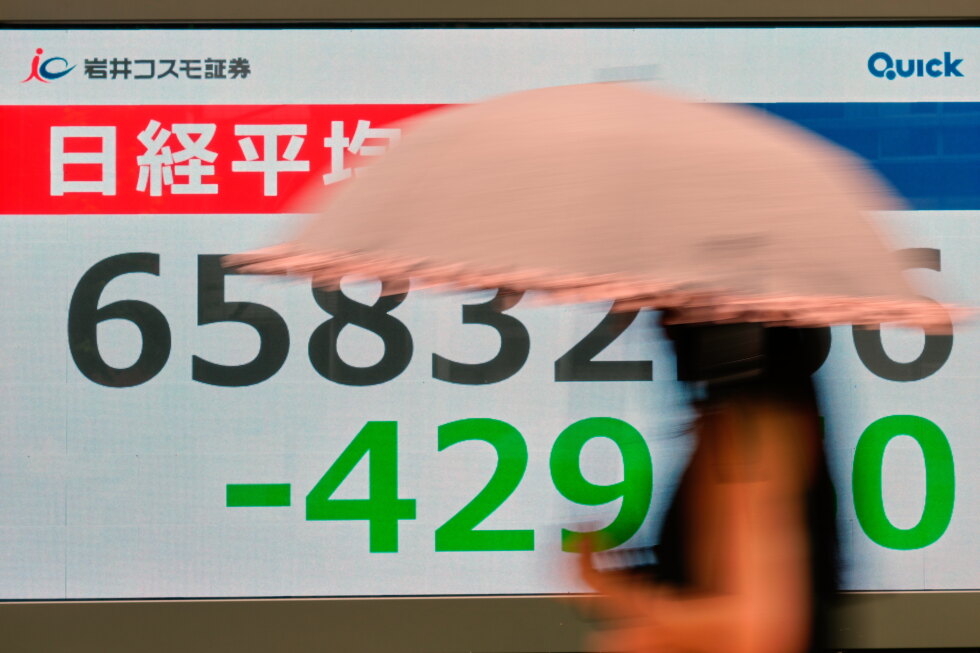
    Across Asian markets, the picture was mixed. South Korea’s Kospi emerged as the region’s sharpest decliner, dropping 1.8% to 6,788.88. Mainland China’s Shanghai Composite also fell slightly, shedding 0.1% to 3,952.18. By contrast, Japan’s Nikkei 225 added 0.4% to hit 66,405.56, Hong Kong’s Hang Seng gained 0.2% to 25,584.79, and Australia’s S&P/ASX 200 rose 0.6% to 9,092.30. Taiwan’s Taiex index surged 0.8%, while India’s Sensex posted a 0.2% gain.

    The market uptick originated on Wall Street Thursday, when the S&P 500 climbed 0.7% to move within striking distance of its all-time high set earlier in August. The Dow added 0.2% on the day, while the Nasdaq composite jumped 1.6% — gains driven almost entirely by a surge in technology stocks fueled by AI demand.

    Nvidia, the global leader in AI-optimized semiconductors, led the charge with an 8.7% rally after the firm reported second-quarter profit and revenue that far outpaced Wall Street analyst forecasts. The company also released upcoming revenue projections that topped consensus estimates, confirming that robust demand for chips powering AI development projects shows no signs of slowing. “AI has reached its inflection point,” Nvidia CEO Jensen Huang said in commentary following the release. “It’s doing useful work. Its tokens are productive and profitable.”

    The strong results helped ease mounting investor anxiety that AI stocks had become overvalued after years of rapid gains fueled by AI hype. In recent weeks, the sector has faced growing skepticism that valuations have outpaced actual profit potential, and that demand for AI chips could cool if the AI revolution fails to deliver on outsized growth promises. Nvidia’s strong performance helped allay those fears for the moment.

    Another major tech firm, enterprise software leader Salesforce, also posted a historic gain, jumping 22.6% — its best single-day performance in six years. The company reported one of its strongest quarters in history, driven by AI-driven growth, raised its full-year revenue forecast, and announced an expanded partnership to integrate AI startup Anthropic’s Claude chatbot into its customer data management platform. The results eased prior concerns that AI-native competitors could siphon customers away from established enterprise software providers like Salesforce.

    Not all U.S. stocks joined the rally, however: a majority of S&P 500 constituents ended the trading day lower. Big box retailer Best Buy dropped 4.4%, even though the company beat analyst forecasts for both profit and revenue in its latest quarter, as persistent worries about consumer spending power amid ongoing high inflation kept investor sentiment muted. Discounters turned in a mixed performance: Dollar General gained 2.5% after beating profit estimates, as analysts predict dollar chains could gain market share from cash-strapped higher-income households seeking more affordable shopping options. By contrast, rival Dollar Tree fell 3.9% despite topping profit expectations.

    In the bond market, Treasury yields moved slightly higher after a new report on weekly unemployment benefit applications confirmed the U.S. labor market remains resilient, a key factor the Federal Reserve considers when setting monetary policy. In currency markets, the U.S. dollar edged up to 159.56 Japanese yen from 159.39 yen, while the euro slipped marginally to $1.1648 from $1.1652.

    Oil prices, a key wild card for global inflation forecasts, have see-sawed in recent sessions amid ongoing uncertainty over conflict in Iran and the resumption of unimpeded commercial shipping through the Strait of Hormuz, a critical chokepoint for global oil supplies. On Friday, international benchmark Brent crude fell 0.4% to $88.13 per barrel, a pullback after the price rose 1.8% in the prior session. U.S. benchmark West Texas Intermediate crude fell 0.6% to $83.08 per barrel.

    All eyes are now turning to a highly anticipated speech scheduled for later Friday from Federal Reserve Chairman Kevin Warsh. Despite growing market pressure for clearer guidance on future U.S. monetary policy, Warsh has signaled he will continue the Fed’s recent approach of providing limited clues to markets about the central bank’s plans for managing inflation.

  • Harvey Norman warns of sales slowdown following federal budget, rate rises

    Harvey Norman warns of sales slowdown following federal budget, rate rises

    One of Australia’s biggest retail names, Harvey Norman, has linked a sharp slowdown in sales growth in the second half of its financial year to weakened consumer confidence triggered by the federal government’s 2026 May budget, with mounting cost-of-living pressures and three consecutive interest rate hikes amplifying the strain on discretionary spending.

    The iconic furniture and electronics retailer reported a solid overall annual result in its latest market update, recording a 3.1% year-on-year rise in total sales to hit $9.6 billion, with Australian franchisee revenue accounting for $6.6 billion of that total. Net profit for the first half climbed 15.2% compared to the previous year, fueled by strong household spending through the key Christmas trading period. But the company made clear that momentum stalled immediately after the federal budget announcement, with consumers pulling back on non-essential purchases amid widespread economic uncertainty.

    “Consumer confidence softened further following the May 2026 federal budget, resulting in more cautious discretionary spending,” the company said in its official update.

    Chairman Gerry Harvey noted the business started the year on a strong trajectory, before a confluence of economic factors dragged down sales in the second quarter. The retailer stopped short of placing full blame on the federal government, also citing skyrocketing fuel and energy costs, elevated freight expenses, and the three consecutive interest rate increases from the Reserve Bank of Australia as key headwinds.

    The Albanese government’s 2026 budget introduced sweeping, once-in-a-generation changes to Australia’s capital gains tax and negative gearing rules, policies that have reshaped investor sentiment across the property and retail sectors. Starting July 1, 2027, the existing 50% capital gains tax discount will be replaced with an inflation-adjusted indexation system. A new 30% minimum tax rate on capital gains will take effect a year later in 2028, eliminating the long-standing tax advantage that allowed asset-rich, cash-poor households to sell assets during low-income years to reduce their tax burden. Negative gearing tax deductions have also been eliminated for new purchases of existing residential properties, though the policy retains existing arrangements for current landlords and allows negative gearing for newly constructed properties.

    Harvey Norman is not alone in facing challenging trading conditions. Fellow major Australian retailer JB Hi-Fi also flagged broader economic pressures when releasing its recent results. In a mid-August earnings call, CEO Nick Wells said the retailer saw a slow start to the new financial year driven by higher interest rates and fuel costs, but he remained optimistic that upcoming major sales events including Black Friday would boost revenue for the remainder of the year.

    Despite the second-half slowdown, Harvey Norman leadership struck a confident tone about the company’s long-term outlook. “The full-year sales result reflects a strong first half and a resilient performance across the Harvey Norman brands as retail conditions became more variable during the second half,” Mr. Harvey said. “Disciplined cost management and sales growth enabled us to absorb inflationary pressures and continue to invest in our expansion initiatives.” He added that the business is well positioned to deliver sustainable long-term growth for its shareholders.

  • Virgin Australia profits soar to $404m after avoiding costly fuel crisis

    Virgin Australia profits soar to $404m after avoiding costly fuel crisis

    Australia’s competitive domestic aviation market has delivered a sharp divide in full-year financial results, with Virgin Australia recording a robust 21% jump in annual profit and issuing its first shareholder dividend since returning to public markets, while rival Qantas has absorbed hundreds of millions of dollars in losses tied to a global jet fuel crisis.

    In its latest full-year market update released this week, Virgin Australia reported an underlying net profit after tax of $404 million, representing a substantial year-over-year increase from the prior reporting period. The airline’s strong performance is largely attributed to a proactive risk management strategy that saw it fully hedge fuel prices months ahead of the extreme volatility that roiled global energy markets in recent months.

    As refining margins for jet fuel skyrocketed from roughly $US20 per barrel to a peak of $US130 per barrel, airlines across the globe were left grappling with ballooning operational costs. Unlike many of its industry peers, Virgin Australia’s hedging strategy insulated the carrier from the worst of these price shocks, allowing it to keep costs stable and preserve margins through the period of volatility.

    The contrast with Qantas could not be clearer. The larger Australian carrier confirmed this reporting cycle that geopolitical instability tied to the ongoing war in the Middle East, paired with skyrocketing fuel costs that far outpaced growing demand for international travel, erased $420 million from its annual profit.

    Thursday’s results mark Virgin Australia’s first full-year financial report since the company relisted on the Australian Securities Exchange on June 24, 2025. To reward investors for their patience following the carrier’s post-pandemic restructuring and relisting, the board has approved a maiden dividend of 7.6 cents per share for qualifying shareholders.

    Virgin Australia Chief Executive Dave Emerson framed the strong results as validation for the company’s multi-year strategy to build a leaner, more resilient business model focused on Australian travelers. “Looking ahead, we remain focused on providing value and choice to Australians to meet their travel needs,” Emerson said. “As an industry, we all have a role to play in managing costs so aviation doesn’t become unaffordable for Australians.”

    The divergent results between the two major Australian airlines highlight how differing risk management approaches can lead to drastically different outcomes during periods of widespread industry disruption, with well-positioned carriers able to capitalize on volatility to gain ground on larger competitors.

  • Australian shares dragged down by interest rate fears after inflation data

    Australian shares dragged down by interest rate fears after inflation data

    Australia’s benchmark share market faced steep downward pressure on Thursday, dragged lower by a combination of stickier-than-expected inflation, stronger-than-forecast household spending, and a wave of underwhelming corporate earnings results that have flipped market expectations for future interest rate moves. The benchmark S&P/ASX 200 closed the trading session down 89.60 points, a 0.98% drop that brought the index to 9038.20, while the broader All Ordinaries index fell 95.60 points, or 1.02%, to settle at 9243.20. Against this volatile backdrop, the Australian dollar strengthened against the U.S. dollar, hitting 71.83 US cents at market close. Just two of the ASX’s 11 industry sectors managed to finish the day in positive territory, with nine ending the session in negative territory.

    The sell-off was led by the consumer discretionary, technology, and large mining sectors, with top retailers leading the declines after releasing weak full-year results. Retail conglomerate Wesfarmers, one of the biggest listed companies on the exchange, saw its share price slump 4.58% to $79.46 after reporting a 1.8% annual drop in net profit to $2.87 billion, where strong performance from its Bunnings and Kmart divisions was offset by lackluster earnings from Officeworks. Rival electronics retailer JB Hi-Fi fell 4.48% to $66.02, and furniture retailer Harvey Norman dropped 2.17% to $4.50.

    In the technology sector, major listed software firms also posted broad losses. Accounting software leader Xero fell 2.60% to $81.73, logistics tech firm WiseTech Global dropped 3.28% to $39.55, and enterprise software provider Technology One fell 2.74% to $31.64. For large iron ore producers, results were mixed: BHP fell 1.48% to $66.40 and Rio Tinto slipped 0.52% to $178.70, while Fortescue Metals bucked the downtrend to gain 0.85% to $17.70. A small number of stocks outperformed, most notably airline giant Qantas, which saw its share price jump 4.77% to $9.66 despite reporting a 13.1% annual drop in net profit to $2.06 billion, a $330 million decline driven largely by a $420 million hit from surging jet fuel costs. Corporate Travel Management, meanwhile, announced it would refund $191 million to customers and set aside an additional $55 million for remediation for three major clients, as the firm narrowly avoided being delisted by posting a full-year net loss of $346.7 million, dragged down by goodwill impairments.

    The market downturn was triggered largely by fresh economic data released earlier this week that has reinforced expectations that the Reserve Bank of Australia (RBA) may need to implement one more interest rate hike to bring persistent inflation under control. Data from the Australian Bureau of Statistics (ABS) released Wednesday showed that headline annual inflation fell to 3.5% in July, down from 3.8% in June, but the figure still came in hotter than economists had forecast. The RBA’s preferred trimmed mean inflation measure, which strips out volatile price movements to track underlying inflation, held steady at 3.6% – matching the previous month’s reading and defying expectations for a small decline.

    Compounding the inflationary pressure, ABS data released Thursday showed household spending rose a stronger-than-expected 1.1% in July, signaling that consumer demand remains resilient enough to keep upward pressure on prices. As a result of the new data, money markets are now pricing a 50% chance that the RBA will raise its official cash rate by 25 basis points to 4.6% when its Monetary Policy Board meets on September 29. Three of Australia’s four major banks have now updated their forecasts to predict a rate hike before the end of 2024, with NAB chief economist Sally Auld reversing her earlier call for rates to hold steady to predict a September hike.

    “July CPI data showed inflation running hotter than the RBA expected in early August, and the RBA has repeatedly signalled in recent weeks that the Monetary Policy Board would act if upside risks to inflation were realised,” Auld noted, adding that “the risk is biased towards an additional hike in November, especially if activity data shows resilience in coming months.” Westpac remains the only major bank that has not updated its rate forecast to reflect the new inflation and spending data.

  • Asian stocks are mixed after Wall Street losses following economic updates

    Asian stocks are mixed after Wall Street losses following economic updates

    Global financial markets delivered a mixed performance on Thursday, with Asian equities splitting gains and losses following marginal downward movement on Wall Street a day earlier, as a blockbuster earnings report from chip giant Nvidia lifted U.S. futures and oil prices retreated. The session unfolded against a backdrop of shifting macroeconomic data and ongoing investor anxiety around the sustainability of the global artificial intelligence investment boom.

    After U.S. markets closed Wednesday, Nvidia — one of the world’s most valuable public companies and a key barometer for the global AI industry — released quarterly results that far outstripped Wall Street analysts’ projections. The firm reported revenue for the May-to-July quarter more than doubled from the same period a year earlier, fueled by explosive, unrelenting demand for its high-end AI chips that power everything from large language models to generative AI tools for major tech corporations. Following the better-than-expected report, U.S. futures traded into positive territory early Thursday.

    Across major Asian benchmarks, performance was fragmented. Japan’s Nikkei 225 edged down 0.2% to close at 66,162.72, though SoftBank Group, the multinational investment holding that holds a stake in AI leader OpenAI, notched a 0.1% gain. South Korea’s Kospi outperformed most regional indexes, climbing 1.5% to 6,909.81, with market heavyweight Samsung Electronics rising 2% as investors bet on ongoing AI chip demand. Japan, South Korea and Taiwan have emerged as the biggest regional winners from the global AI investment frenzy, and Taiwan’s benchmark Taiex index added 0.5% on Thursday.

    In Greater China markets, Hong Kong’s Hang Seng Index slid 0.4% to 25,548.83, while the Shanghai Composite Index gained 0.6% to 3,935.99. New economic data released by China showed growth in industrial profits slowed to 11.2% in July, down from 15.1% in June, signaling ongoing softness in the country’s industrial recovery. Further afield, Australia’s S&P/ASX 200 dropped 0.9% to 9,041.70, and India’s Sensex posted a marginal 0.1% decline.

    On Wednesday, U.S. markets closed with modest losses, with the benchmark S&P 500 falling less than 0.1% to remain just below its recent record high levels. The Dow Jones Industrial Average lost 0.2%, while the tech-heavy Nasdaq Composite dipped 0.1%. Beyond Nvidia’s results, the session brought other notable market-moving developments: Meta Platforms added 1.1% after reaching an $18 billion settlement with U.S. states over claims that its platforms Facebook and Instagram fueled teen social media addiction. The deal also requires Meta to implement new child-safety measures, ending a landmark national trial against the company.

    New macroeconomic data released Wednesday also gave investors new insight into U.S. economic momentum and inflation pressures. The revised estimate for U.S. gross domestic product growth in the April-June quarter came in at 1.5%, matching earlier projections. The personal consumption expenditures price index — the inflation metric the Federal Reserve has long prioritized for policy decisions — held steady at 3.7% in July, unchanged from June. That reading was slightly higher than the 3.6% consensus forecast from economists surveyed by FactSet, and remains far above the Fed’s longstanding 2% annual inflation target.

    Nvidia’s strong results have come at a time of widespread debate among investors over the future of the AI boom. While chip and AI-related stocks have rallied for more than two years, many market participants warn that massive current investments in AI infrastructure could lead to an asset bubble, as companies may fail to generate enough near- and medium-term profits to justify the sky-high valuations and rising capital outlays.

    In energy markets, oil prices edged lower early Thursday. Brent crude, the global benchmark for oil pricing, fell 0.5% to $86.49 per barrel. For context, the commodity traded around $72 per barrel in late February, before the outbreak of open conflict in Iran pushed energy prices higher. U.S. benchmark West Texas Intermediate crude also dropped 0.5% to $81.84 per barrel. In currency markets, the U.S. dollar appreciated slightly against the Japanese yen, rising to 159.38 yen from 159.31 yen, while the euro edged up to $1.1655 from $1.1651.

  • Bond yields are surging: Here’s why that could spell trouble

    Bond yields are surging: Here’s why that could spell trouble

    Across major global economies from North America to Europe and East Asia, financial policymakers and market participants are growing increasingly uneasy as government bond yields climb to levels not witnessed in a decade or longer. This sharp uptick is pushing borrowing costs higher for every segment of the economy: national governments, private businesses, and ordinary consumers alike.

    At the core of this trend is a toxic combination of ballooning government budget deficits and swelling national debt loads, which have eroded investor confidence in the ability of major economies to restore long-term fiscal sustainability. Compounding this pressure is persistently high inflation across the United States and Europe, which has been further stoked by rising energy prices tied to ongoing Middle East conflict — creating greater odds that central banks will keep interest rates elevated, or even push them higher, in the coming months.

    To understand the current landscape, it is important to contextualize just how far yields have risen. Bond yields move inversely to bond prices, rising when investors demand higher interest returns to purchase or hold government-issued debt. For decades, U.S. Treasury bonds have been viewed as the global gold standard of safe-haven assets, allowing the U.S. government to borrow from international investors at historically favorable rates. But even this market is seeing unprecedented shifts: the yield on 30-year U.S. Treasuries, a key benchmark for gauging long-term economic confidence, hit 5.34% in mid-August — its highest level since 2007, just before the onset of the global financial crisis. While it has since pulled back slightly to around 5.17%, it remains far above levels seen over the past 15 years.

    The same upward trend is playing out across European bond markets. Germany’s benchmark 10-year bund, the eurozone’s de facto risk-free rate, currently trades around 3.22% — a level not reached since 2011. In France, where the sitting government faces intense pressure to implement unpopular spending cuts ahead of next year’s presidential election, the 10-year government bond yield has hit 4.05%, its highest since 2008 and a full 0.5 percentage points above its yield at the start of 2024. Even Japan, which spent decades grappling with deflation and maintaining near-zero bond yields to stimulate growth, has seen a sharp jump: its 10-year yield has surged to nearly 2.9%, up from just 2.1% in February 2024.

    Economists point to repeated large-scale economic shocks over the past 15 years as the root cause of ballooning deficits and debt. Since the 2008–2009 global financial crisis, public debt levels have continued a steady upward climb across nearly all major advanced economies. That acceleration grew even steeper after the COVID-19 pandemic, when governments rolled out massive stimulus packages to prevent economic collapse, and was exacerbated by the onset of new geopolitical shocks, including the Ukraine war, escalating Middle East tensions, and the reversion to tit-for-tat trade conflicts between major global powers. All of these events required extraordinary government spending to buffer domestic economies from the fallout.

    Notably, even countries with a longstanding reputation for fiscal prudence are now facing rising deficits. Charlotte de Montpellier, an economist at ING, pointed out that traditional fiscal conservatives like Germany are no longer immune to expanding budget shortfalls. To fund these ongoing deficits, governments have to issue a growing volume of new bonds, creating intense competition between issuers to attract limited global capital. This competition forces governments to offer higher interest rates to lure buyers, which in turn pushes up overall bond yields across the market.

    Adding to the competitive pressure on capital is a surge in borrowing from large technology companies, which are taking on massive debt to fund the ongoing global boom in artificial intelligence research and deployment. This creates an additional strain on available capital, further pushing borrowing costs higher.

    The most alarming headline comes from the United States, where the U.S. Treasury announced this month that total U.S. national debt has crossed the $40 trillion threshold for the first time in history — doubling the country’s total debt load from just 10 years ago. As yields have climbed, the annual cost of servicing this national debt has ballooned dramatically, consuming taxpayer dollars that could otherwise be allocated to core public priorities including education, health care, and national defense. In 2023 alone, U.S. federal interest outlays hit a staggering $970 billion, up from just $350 billion in 2021.

    Uncertainty over U.S. monetary policy is also amplifying market volatility. With U.S. inflation currently running at 3.7% — nearly double the Federal Reserve’s 2% target — bond investors remain unsure what path new Federal Reserve Chair Kevin Warsh will take to bring prices under control. De Montpellier noted that Warsh has shifted away from the Fed’s recent practice of clear forward guidance on interest rate moves, adopting a more opaque communication strategy that has left markets guessing. Because U.S. monetary policy sets the tone for global bond markets and interest rates worldwide, this uncertainty has spilled over into markets across the globe.

    For ordinary households and businesses, the impact of rising bond yields is immediate and tangible. Higher government bond yields directly translate to higher borrowing costs for everyday consumers, from home mortgages to auto loans and personal credit. For businesses, higher interest rates mean more expensive borrowing to fund expansion, research, and new hiring — a dynamic that weighs on overall economic activity. Ultimately, this translates to fewer home purchases, fewer business investment projects, and slower overall economic growth. As de Montpellier put it: “It’s clearly not good news” for the global economic outlook.

  • Two of Australia’s biggest banks backflip to predict painful new interest rate hike

    Two of Australia’s biggest banks backflip to predict painful new interest rate hike

    Australia’s stubbornly persistent above-target inflation has prompted two of the nation’s largest lenders to revise their interest rate outlooks, delivering a bleak update for mortgage holders already grappling with years of rising borrowing costs. Both the Commonwealth Bank of Australia (CBA) and National Australia Bank (NAB) now confirm that additional Reserve Bank of Australia (RBA) rate increases are on the horizon to cool persistent price pressures.

    NAB’s chief economist Sally Auld has reversed her earlier forecast that rates would remain on hold, now projecting a rate hike as early as the RBA’s September monetary policy meeting. Auld pointed to newly released July Consumer Price Index (CPI) data that came in hotter than RBA leaders had projected just weeks earlier, noting that the central bank’s Monetary Policy Board has repeatedly warned it would take immediate action if inflation risks continued to trend upward. Beyond September, Auld added that the outlook leans heavily toward a second additional hike in November, particularly if broader economic activity data remains resilient in the coming months.

    CBA’s head of economics Belinda Allen shares the expectation of a 2025 rate hike but pushes back the timeline, arguing that current economic data does not yet justify a September increase. Even with a slower timeline, Allen warned that holding rates steady through the November meeting would shock markets and analysts, given the RBA’s laser focus on reining in inflation even as signs of a slowing economy emerge. On a slightly more positive note for struggling mortgage holders, Allen projected that the period of elevated rates could be relatively short: she forecasts the RBA could begin cutting rates as early as May 2027, with a follow-up cut in August, once inflation returns to the central bank’s target range.

    Two other major Australian lenders, Westpac and ANZ, have not yet released updated rate forecasts following the July inflation release. However, independent economic analysts have echoed the big banks’ cautious outlook, arguing that the latest inflation data leaves the RBA with little choice but to resume tightening after its recent pause.

    KPMG chief economist Brendan Rynne explained that the RBA’s decision to leave rates unchanged at its August meeting now leaves the central bank playing catch-up on inflation. So far in 2025, the RBA has delivered three rate hikes totaling 75 basis points, lifting the official cash rate from 3.60% to 4.35%, before pausing rate movements in June and holding again in August. “Today’s data supports the view that without policy action we may be in for a long, costly grind to get inflation under control, and the Reserve Bank may have missed an opportunity at the last board meeting to get ahead of the game by raising rates,” Rynne said.

    Russel Chesler, head of investments and capital markets at global asset manager VanEck, put it more bluntly, noting that July’s data shows the “inflation fire is still smouldering” across the Australian economy. “The inflation fight is far from won,” Chesler said. “We remain firmly of the view that inflation is becoming entrenched and has little chance of returning to the 2.5 per cent midpoint of the RBA’s target range by late 2027.”

    To understand why markets and forecasters are bracing for rate hikes, it is important to break down the latest inflation figures from the Australian Bureau of Statistics (ABS). While headline inflation edged lower to 3.6% in the 12 months to July, down from 3.8% in June, the core trimmed mean inflation rate – a closely watched metric that strips out the most volatile price movements to reflect underlying inflation – held steady at 3.6%, well above the RBA’s 2-3% annual target range. Market analysts had expected a sharper decline in headline inflation to roughly 3.2%, making the higher-than-forecast reading an unwelcome surprise.

    Breaking down price pressures, the biggest driver of ongoing inflation was housing costs, which rose 6% over the past 12 months, followed by food and non-alcoholic beverages, which increased by 3.2%. Energy prices also continued to distort national inflation data: a sharp 2024 electricity price increase dropped out of the annual comparison, but fuel prices spiked 7.5% month-over-month in July following three consecutive months of declines. The jump in fuel prices was driven by two key factors: rising global oil prices and the partial rollback of the federal government’s temporary fuel excise subsidy, which was cut in half this July.

    ABS head of price statistics Rachael McCririck confirmed that while there has been some progress on lowering headline inflation, much of that progress stems from calendar effects, as the extreme price spikes seen in July 2024 roll out of the 12-month calculation. Following the release of the inflation data, money markets immediately priced in an 87% probability that the RBA will deliver at least one additional rate hike before the end of 2025, leaving millions of Australian mortgage holders bracing for new increases to their monthly repayment.