分类: business

  • US energy consumers have spent $121 bn extra due to war: Moody’s

    US energy consumers have spent $121 bn extra due to war: Moody’s

    Eight months after former U.S. President Donald Trump launched an unauthorized military conflict with Iran, new economic analysis has laid bare the steep financial toll the standoff has imposed on American consumers and global energy markets. The conflict, which began in February without formal approval from the U.S. Congress, triggered a cascading series of disruptions that have sent energy costs soaring worldwide: Iran responded to U.S. military strikes by closing the Strait of Hormuz, a critical global shipping chokepoint through which roughly 20% of the world’s daily oil supply passes.

    Independent analysis from Moody’s Analytics quantifies the cumulative burden on American families, estimating that the average U.S. household has paid $1,760 in extra expenses since the conflict began. Of that total, more than half — $121 billion nationwide, equal to $930 per household — comes directly from inflated energy costs. The remaining costs break down into two additional categories: $425 per household from higher interest rates driven by inflationary pressure from energy prices, and $405 per household from expanded military spending, which will ultimately be paid by taxpayers either through growing national debt or future tax increases, according to Moody’s chief economist Mark Zandi.

    In an interview with CNBC published this week, Zandi emphasized that the numbers underscore the intense financial strain already weighing on U.S. consumers. “Consumers are under a lot of financial pressure,” Zandi told the network.

    The outlook for near-term relief remains grim, according to geoeconomics experts, as escalating regional tensions across the Middle East continue to threaten energy infrastructure. Karthik Sankaran, a senior geoeconomics research fellow at the Quincy Institute for Responsible Statecraft, noted that ongoing developments — including Houthi forces capturing a key Red Sea port city and a recent drone strike on a Saudi oil pipeline — have left the global energy system far more vulnerable to shocks than it was at the conflict’s outset.

    Sankaran explained that global buffers that normally soften the blow of energy disruptions have already been exhausted. Global seaborne oil storage held in tankers has been largely depleted, the U.S. Strategic Petroleum Reserve has already released roughly 130 million barrels to cool prices, and China, the world’s top oil importer, has ramped up its imports to 7.2 million barrels per day, up from a June low of 6 million barrels, leaving little spare supply to absorb new disruptions.

    While American consumers face significant discomfort from elevated prices, the situation is far more severe for low- and middle-income nations across the Global South, Sankaran added. Spikes in diesel prices, in particular, hit these economies disproportionately: diesel powers the trucks, buses, and agricultural equipment that underpin local supply chains, and it is far more critical to daily function in these regions than gasoline, which is largely tied to personal vehicle ownership that remains rare in lower-income countries.

    The sustained rise in global fuel prices has already sparked widespread public unrest across six continents, a CNN investigation confirmed this week. Protests over soaring fuel costs have erupted in nations including Syria, Guatemala, France, Portugal, and the Philippines. In Syria, where economic instability has compounded over a decade of civil conflict, demonstrations have been particularly fierce. Sunday protesters blocked the major Hasaka–Deir ez-Zor highway, burning tires and halting oil tanker traffic to voice their anger. Muaz Al Abdullah, a Syria analyst with global conflict monitor Armed Conflict Location and Event Data (ACLED), told CNN that mounting public anger over fuel access, rising prices, plummeting purchasing power, and failing public services has reached a breaking point, with protesters now calling for the dismissal of the country’s energy minister.

  • ‘China Shock 2.0’ fuels EU push for united response to Beijing

    ‘China Shock 2.0’ fuels EU push for united response to Beijing

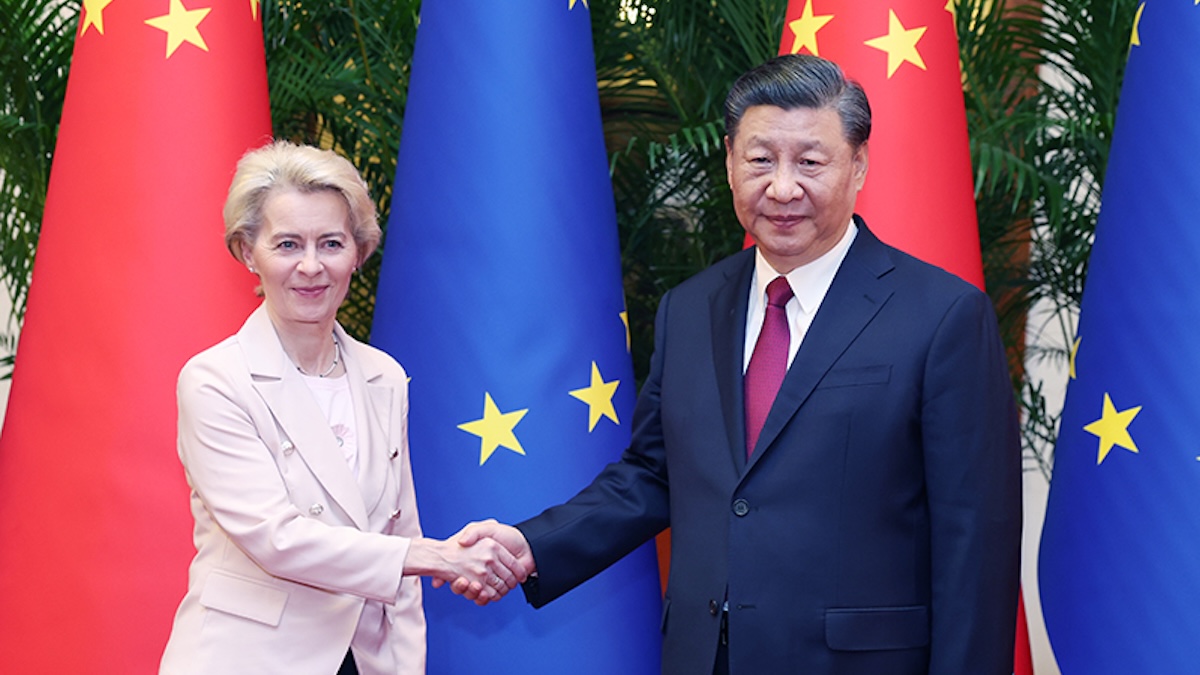
    In her annual State of the Union address to the European Parliament last Wednesday, European Commission President Ursula von der Leyen sounded an urgent alarm over what she terms “China Shock 2.0”, arguing that rising Chinese high-value exports have already arrived and are threatening the bloc’s core industrial base, an outcome she calls unsustainable for European economies.

    The original “China Shock” emerged after China’s 2001 accession to the World Trade Organization, when a flood of low-cost Chinese consumer goods including toys, textiles and basic electronics reshaped global supply chains and eroded Europe’s low-end manufacturing sectors. At the time, European economies adapted by shifting production up the value chain, focusing on higher-value goods and services to maintain competitive advantage. The new iteration of this trade dynamic, however, looks very different: today’s Chinese exports are concentrated in high-value sectors including electric vehicles, industrial machinery, chemicals and power generation equipment, meaning Chinese manufacturing has now closed the competitive gap that let Europe escape the first shock, leaving few untapped higher-value segments for European firms to retreat into.

    Compounding this shift is the legacy of U.S. trade policy: tariffs imposed by the Trump administration on Chinese goods have reduced Chinese access to the American market, pushing the bulk of China’s export surplus toward the European Union, the world’s largest remaining open large economy. Von der Leyen emphasized that the EU’s daily trade deficit with China now hits 1 billion euros (US$1.15 billion), a level that has crossed a clear tipping point. “Some say the second China shock is looming, but it’s already here,” she said. “It shows in our communities and in factories across our Union. It leads to deindustrialization in the industrial heartlands of Europe. This is unsustainable.” She added that Brussels would deploy every policy tool at its disposal to rebalance the bilateral trade relationship, noting that “Words are good. But deeds are better.”

    Von der Leyen also highlighted another key point of economic vulnerability: the bloc’s heavy reliance on Chinese critical raw materials, with China supplying more than 80% of the EU’s needs for many key inputs, and 90% of some rare earth minerals critical for clean energy and defense technology. To address this dependence, she announced the creation of a new European Critical Raw Materials Corporation to help the bloc build stockpiles of materials needed for electric vehicles, semiconductors, batteries and defense systems.

    Just days before von der Leyen’s address, on September 9, the European Commission proposed an updated Public Procurement Act that would grant public authorities the power to reject bids for major infrastructure and service contracts if less than 50% of the contract’s total value originates within the EU. The proposed rules, which would govern the EU’s 2.5 trillion euro annual public procurement market covering national agencies, schools and hospitals, still require formal approval from the European Parliament and all EU member states to take effect. Industry groups including the International Road Transport Union and European Metropolitan Transport Authorities have already called for targeted adjustments to the draft rules, asking for grace periods for already purchased electric buses, aligned exemption frameworks and protections for operators from unexpected costs caused by manufacturer delivery delays.

    In response to von der Leyen’s remarks, China’s Ministry of Commerce reaffirmed Beijing’s consistent stance on Thursday, emphasizing that China rejects confrontational “microphone diplomacy” and has no interest in escalating rhetorical disputes. Ministry spokesperson He Yadong said Beijing favors open communication and pragmatic problem-solving to address bilateral trade frictions.

    The same day, EU Trade Commissioner Maroš Šefčovič held a virtual call with Chinese Commerce Minister Wang Wentao to discuss reciprocal market access and ongoing Chinese export controls on rare earth minerals. Šefčovič is scheduled to travel to Beijing on October 8 and 9 to co-chair the second session of the EU-China Trade and Investment Council, with the European Commission stating it hopes the visit will deliver tangible, credible progress on outstanding trade issues. EU member states will also debate the growing trade imbalance at the upcoming European Council summit scheduled for October 15-16, with the timeline made urgent by shifting U.S.-China trade dynamics: the one-year U.S.-China trade truce is set to expire on November 10, just one week after the U.S. November 3 midterm elections that could reshape Washington’s trade approach. U.S. President Donald Trump and Chinese President Xi Jinping are also set to meet in Washington on September 24, with prior media reports indicating Washington may announce an additional 7.5% tariff on Chinese goods tied to industrial overcapacity ahead of the summit, pushing the average U.S. duty on Chinese imports to roughly 20%.

    Recent data underscores the scale of the EU’s growing trade imbalance with China. Eurostat reported in April that the EU’s full-year 2025 trade deficit with China widened to a record 359.8 billion euros, with EU exports to China falling 6.5% to 199.6 billion euros while Chinese imports to the EU rose 6.4% to 559.4 billion euros. The growing deficit has already split EU member states to some degree: in late May, a France-led coalition of five countries including Italy, Spain, the Netherlands and Lithuania called on Brussels to expand the use of anti-dumping and anti-subsidy investigations against Chinese imports in steel, automotive and clean technology sectors. Since that call, Brussels has moved toward drafting collective policy responses to the perceived trade challenge.

    Beijing has pushed back hard against the “China Shock 2.0” framing, with Chinese officials arguing that growing Chinese industrial competitiveness should be recognized as a global opportunity rather than a threat. In a late July media briefing, Chinese Vice Minister of Commerce Yan Dong argued that the dynamic should be renamed “China Opportunity 2.0”, outlining four core arguments for this re-framing. First, China’s robust manufacturing base acts as a global anchor for supply chains, offsetting product shortages caused by rising protectionism and geopolitical conflict; between 2012 and 2024, China’s textile machinery exports topped $30 billion, helping Southeast and South Asian nations develop into major global manufacturing hubs. Second, China accelerates global technological innovation by rapidly scaling new technologies into affordable mass-market products, with its open-source AI models recording more than 10 billion downloads globally, expanding access to cutting-edge technology for developing nations. Third, China’s booming green manufacturing sector has driven dramatic global cost reductions for clean energy: data from the International Renewable Energy Agency shows that Chinese production has cut global costs for wind and solar power by between 60% and 80% over the past decade, with China’s green industry projected to exceed 20 trillion yuan (US$2.98 trillion) in size by 2030. Finally, China’s high-volume, low-cost industrial output has helped reduce living costs and curb global inflation, a benefit visible this summer in the strong sales of affordable Chinese-made air conditioners across Europe amid record heatwaves.

    Chinese analysts note that Beijing holds a range of policy leverage if the EU moves forward with new restrictive trade measures, including potential adjustments to rare earth export policy, tariffs on European agricultural goods, luxury products and high-end industrial equipment, and restrictions on European service providers operating in the Chinese market. Many Chinese observers argue that full decoupling from China is simply not feasible for the EU. As a columnist for Chinese state-affiliated outlet Huanqiu.com put it, “Europe needs the Chinese market to absorb its high-end equipment, luxury goods and professional services, and needs a stable supply of critical raw materials, while China needs Europe’s technical standards, brand channels and regulatory experience.” The columnist added that framing China as a political scapegoat for Europe’s industrial challenges would only raise costs for European businesses and consumers, and that EU leaders should instead prioritize pragmatic engagement through existing bilateral communication channels.

    Other Chinese analysts point out that the EU does not have fully unified trade interests when it comes to China: Southern European states like France and Italy favor stronger industrial protectionist measures to shield domestic manufacturers, while Northern European countries including Germany, which maintain deep economic ties with China, fear retaliation against their own firms that rely on access to the large Chinese market. As Guizhou-based analyst Sima noted, China is both a competitor and a critical export market for the bloc, meaning internal divisions will shape any unified EU policy. If the EU proceeds with new tariffs or market access restrictions, Sima noted, China has a range of potential response tools including trade remedies, export controls, an unreliable entity list, counter-sanctions and adjusted government procurement rules, and any retaliation would hit individual EU member states unevenly, exacerbating internal divisions. Sima added that Beijing will not sacrifice its core development rights in upcoming negotiations, and called on the EU to improve the competitiveness of its own domestic products and relax its own high-tech export restrictions to China as a more productive path to narrowing the bilateral trade deficit.

  • Japan raises interest rate to new 31-year high to curb rising prices

    Japan raises interest rate to new 31-year high to curb rising prices

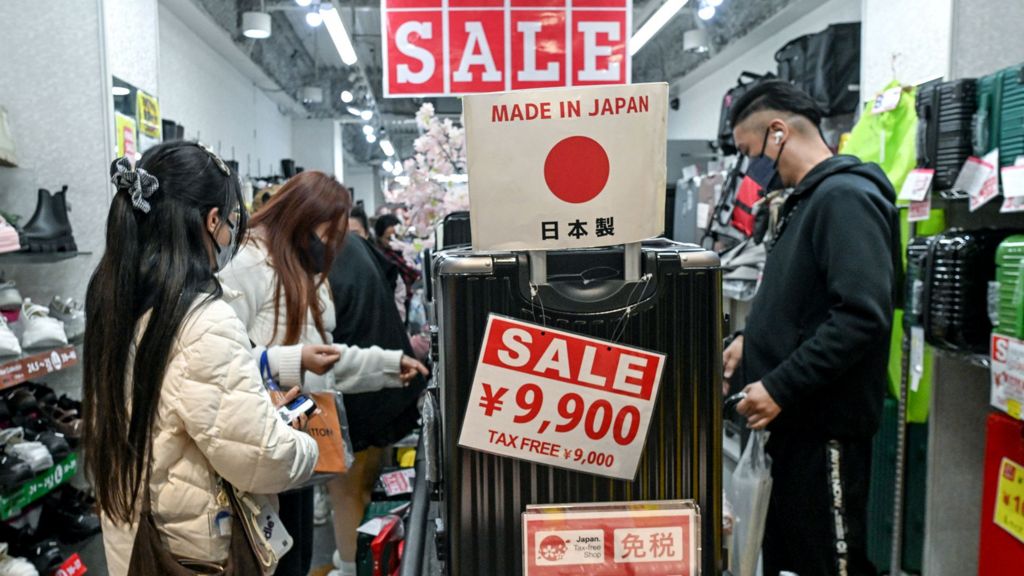
    The Bank of Japan (BOJ) has delivered its latest interest rate hike, pushing its main borrowing cost to 1.25% — the highest level recorded since 1995. The widely expected move, announced Friday, marks the sixth consecutive rate increase from the BOJ since 2024, when the central bank began unwinding three decades of ultra-loose monetary policy from a historic low of minus 0.1%.

    This decision aligns Japan with a broader global trend of monetary tightening, as major central banks around the world ramp up interest rates to combat soaring inflation driven by rising energy prices. The recent Iran war has disrupted energy shipments through the critical Strait of Hormuz, pushing up global oil and gas costs. Just this week, the U.S. Federal Reserve raised its benchmark rate for the first time in more than three years, and the European Central Bank implemented its own rate hike earlier this September.

    Japan faces a unique set of interconnected economic pressures that have necessitated this policy shift. For nearly 30 years, the country grappled with stagnant growth, persistent deflation, or extremely low inflation, but recent years have brought a reversal of that trend. While the latest official data shows core inflation eased slightly to 1.7% in August from 1.8% in July, remaining just below the BOJ’s 2% target, inflation remains a growing concern for Japanese households.

    As a nation heavily dependent on energy imports from the Middle East, Japan is particularly exposed to supply disruptions stemming from the conflict in Iran. Beyond inflation, the country has also struggled with a steep decline in the value of the yen, which hit a 40-year low against the U.S. dollar in August. In response, Japan and the United States launched a coordinated currency intervention to halt the yen’s slide — the first joint intervention of this kind since 2011, when the two countries acted to weaken the yen in the wake of the devastating Tohoku earthquake and tsunami.

    U.S. Treasury Secretary Scott Bessent has openly pressured BOJ Governor Kazuo Ueda to continue raising rates to support the yen, stating that Japanese authorities should “do the right thing” to stabilize currency markets. Both Japanese finance officials and the U.S. Treasury have also confirmed they stand ready to conduct additional joint interventions if the yen’s decline continues.

    Market analysts note that the end of Japan’s era of ultra-cheap borrowing is a landmark shift for the global economy. “One of the world’s last sources of ultra-cheap money is disappearing,” explained Lale Akoner, market analyst at investment firm eToro. Akoner added that if the yen fails to strengthen despite higher interest rates, persistent inflation pressure could force the BOJ to accelerate monetary tightening faster than markets or the Japanese government currently expect.

    Higher interest rates typically attract foreign investors seeking higher returns, which usually strengthens a nation’s currency. As Japan aligns its monetary policy with other major global economies, the central bank’s gradual rate hikes are designed to address domestic economic challenges while bringing Japan into line with global monetary conditions.

  • ‘This is our company’: Nigerians show off oil wealth after share-buying frenzy

    ‘This is our company’: Nigerians show off oil wealth after share-buying frenzy

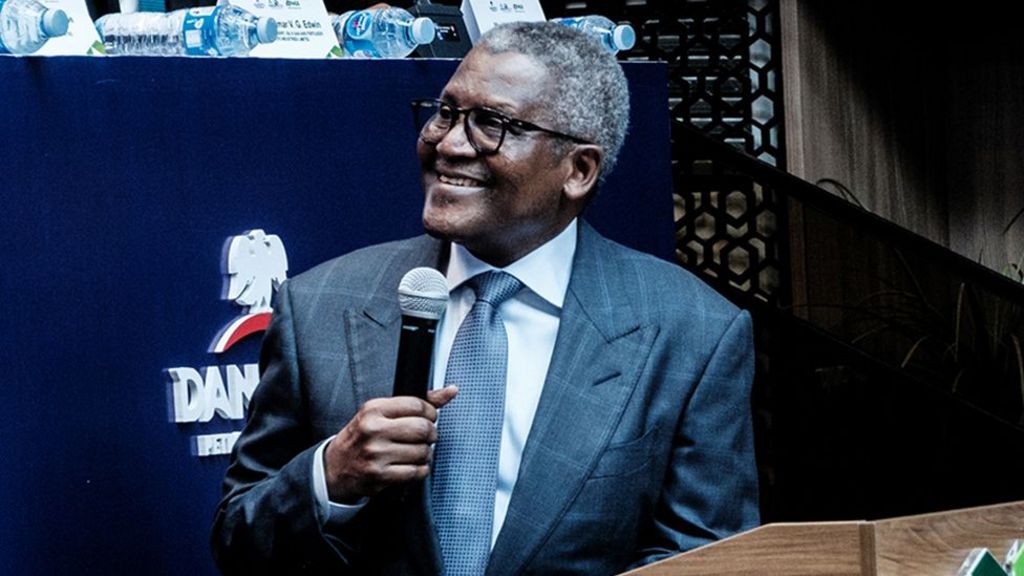
    Across Nigeria, a ground-shaking shift in the country’s energy and investment landscapes has turned ordinary citizens into part-time oil industry owners, igniting a national wave of investor enthusiasm that has flooded trading platforms and dominated social media feeds. What started as an ambitious vision from Aliko Dangote, Africa’s wealthiest billionaire and Nigeria’s most iconic business leader, to create a “people’s IPO” has turned into the largest share offering in African history, capturing the imagination of a nation grappling with widespread economic hardship.

    On Monday, more than 4 billion shares in Dangote’s sprawling Lagos-based oil refinery hit the public market – accounting for just over 3% of the company’s total equity. The offering was structured to be accessible to everyday Nigerians, with a minimum purchase requirement of just 10 shares, equal to roughly $4 (or £3). This low barrier to entry has opened up stock market investing to thousands of first-time participants, turning casual citizens into joke-playing “part-owners” of a facility that has already reshaped Nigeria’s entire oil sector.

    Social media has erupted with playful memes and viral content celebrating the new status of small investors. One widely shared video shows a Nigerian stopping a speeding delivery truck owned by Dangote’s company, lecturing the driver against being reckless with “our company property.” Other memes show small stakeholders dialing up Dangote directly to weigh in on corporate strategy. A new slang term, “Yangote” – a Hausa language pun that translates roughly to “we all own a share now” – has quickly risen to the top of Nigeria’s social media trending charts.

    The unprecedented demand caught popular mobile trading platforms off guard. Leading Nigerian investment app Bamboo crashed entirely on the IPO’s opening day, overwhelmed by the surge of user activity trying to purchase shares. In a public statement after the outage, the platform apologized to users, acknowledging “We know we let you down.”

    Observers say this level of national excitement is almost unprecedented in Nigeria’s modern investment history. Public affairs analyst Jamil Ubah noted that the IPO has tapped into a deep-seated dream of financial advancement for a population where millions struggle to cover basic daily expenses. “I think the hope for the common man is that his money will grow into something big, and don’t forget this is coming at a time when many are struggling as the economy is not doing great,” Ubah explained in an interview with the BBC.

    That enthusiasm has translated directly into action for first-time investors like 25-year-old clothing vendor Idris Lawal Musa, who made his first ever stock market purchase by sinking 21,000 naira ($16, or £12) into 40 shares. “It is no longer Dangote but ‘Yangote’, the company belongs to us now,” Musa told reporters, laughing. Like many small investors participating in the offering, Musa said he plans to sell quickly if the share price rises, fitting with his background as a small business trader.

    The explosive popularity of the IPO also reflects a longer-term shift in Nigeria: the rise of a new investment culture among young Nigerians, who have increasingly embraced mobile trading platforms, digital savings products and cryptocurrency over the past decade. Pre-IPO hype spread rapidly across social media, with users sharing step-by-step investment guides, debating the refinery’s market valuation, and urging friends and family to join in to avoid missing out on the opportunity. That FOMO (fear of missing out) has pulled many first-time investors into the market who have little prior experience with stock risk.

    Even amid the national frenzy, financial experts have issued clear warnings about the potential downside of the hype. Shares can just as easily decrease in value as they can rise, meaning inexperienced investors could lose part or all of their initial investment. Financial analyst Shuaib Uwais cautioned that prospective buyers should not treat the IPO as a guaranteed path to quick wealth. He urged investors to carefully weigh multiple risks that could impact the refinery’s future performance, including disruptions to crude oil supply, unexpected operational challenges, shifting regulatory policies, and global fluctuations in demand for refined petroleum products. “If for any reason the company experiences difficulty in sourcing its raw materials, there could be challenges,” Uwais noted.

    Despite these risks, the IPO marks a major milestone for both Nigeria’s economy and Dangote’s years-long project to end the country’s reliance on imported refined fuel. Until the Dangote refinery launched operations two years ago, Nigeria – Africa’s largest crude oil producer – had no large-scale domestic refining capacity, forcing it to import nearly all finished petroleum products for domestic use. Today, the 700,000-barrel-per-day facility meets most of Nigeria’s domestic fuel demand, transforming the country’s energy sector. For Dangote, the public share offering is designed to raise capital to fund further expansion of the business – a goal that thousands of newly minted small Nigerian shareholders are now eager to support.

  • Dubai court lifts travel ban on British-Pakistani shipping tycoon yet to settle UK case

    Dubai court lifts travel ban on British-Pakistani shipping tycoon yet to settle UK case

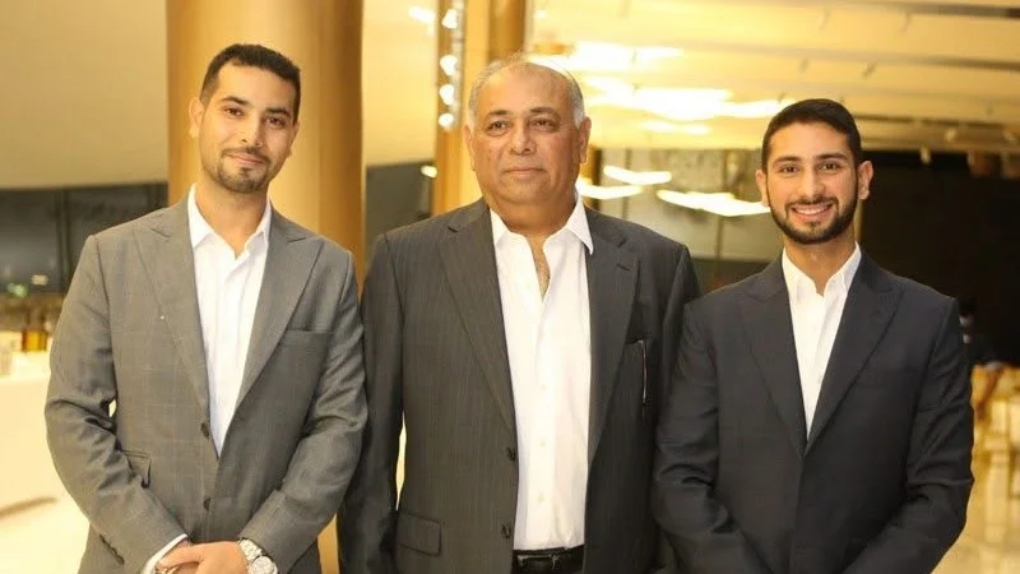
    In an exclusive revelation from court documents obtained by Middle East Eye, a Dubai court has removed a travel ban imposed on a British-Pakistani father and son duo previously found liable for conspiracy and deceit in a major UK fraud case, triggering deep anxiety among creditors who fear the pair will flee the United Arab Emirates. British citizens Muhammad Tahir Lakhani and his son Muhammad Ali Lakhani were first held liable for fraudulent misrepresentation at London’s Commercial Court in 2024, over false claims they made to secure a $45 million loan for Astir Maritime, a shipping firm ultimately controlled by the pair and another family member.

    The loan, the court heard, was reportedly requested to shore up the family’s ship-recycling operations amid a global trade and market downturn, with the funds earmarked for the purchase of ageing vessels that would later be sold to shipyards for dismantling and resale of parts. The Lakhani pair has already admitted to fabricating explanations for their repeated failure to repay the outstanding debt to lenders, who are led by London-based investment firm Njord Partners Sma-Seal LP. To date, no final settlement has been reached in the case, and the pair has remained based in Dubai, where the Lakhani family has built a decades-long portfolio of shipping and ship-recycling enterprises.

    As part of enforcement efforts to recover the unpaid debt, UAE authorities issued a travel ban barring the Lakhanis from leaving the country in 2025. However, court filings confirm that the ban was formally lifted on 26 August this year, following a formal request from the Lakhani family. In their submission to the Dubai court, the pair argued that unrestricted travel was necessary for them to conduct business operations, restructure their financial affairs, and ultimately meet their outstanding repayment obligations to creditors.

    This decision has drawn fierce criticism from sources close to the creditor group, who note that the lifting of the travel ban is both concerning and contradictory to the Lakhanis’ own claims. During the period the travel ban was in effect, the family paid $5 million to resolve separate enforcement proceedings, and later offered a lump sum settlement of between $4 million and $5.5 million to address the outstanding 2024 High Court judgment. This track record of transactions, the source argues, directly undermines the claim that travel restrictions prevented the Lakhanis from organizing their finances to settle the debt. Creditors, including institutional stakeholders such as pension fund managers, now fear the pair will use their newly restored freedom of movement to escape to Pakistan, where the Lakhani family has its ancestral roots.

    Middle East Eye’s repeated requests for comment from Muhammad Tahir Lakhani, who was born in Karachi, went unanswered, including inquiries about whether he planned to leave the UAE. The family’s Dubai-based legal representative also declined to respond to questions about the case. UK authorities have also maintained silence on the matter: the UK Home Office confirmed it does not comment on individual cases, while the Foreign, Commonwealth and Development Office noted it had not been approached for consular assistance but remained ready to provide support if requested. Sources close to the proceedings confirm that Geraldine McCafferty, the newly appointed British ambassador to the UAE, has been fully briefed on the situation.

    The 2024 fraud judgment is not the first legal controversy the Lakhani family has faced in UK courts. In 2020, UK judges issued worldwide asset freezing orders against Tahir Lakhani and his sons after a separate group of lenders accused the family of fraud in connection with other ship-recycling ventures. The 2020 proceedings ultimately resulted in a $77 million judgment awarded to the lenders, which the Lakhanis settled in 2025 for just $5 million, a outcome Tahir Lakhani described as an “amicable” resolution. During the 2020 case, Tahir Lakhani was described in court filings as an “internationally recognised visionary shipping executive”, credited with founding Dubai Trading Agency, the first Middle East-based company to enter the large-scale ship recycling market.

    More recently, in 2024 the Financial Times linked one of Lakhani’s companies to Russia’s so-called “shadow fleet” of vessels used to evade Western sanctions imposed over the Ukraine conflict. In response to the reporting, Tahir Lakhani denied any involvement or facilitation of sanctions breaches, and has long positioned himself as a key figure in the development of the UAE as a global maritime hub. His professional biography, published by Thrive Global, the media firm founded by Ariana Huffington, notes he has played a “critical role in advocating the UAE as an essential zonal and global centre for maritime trade and logistics”.

    A prominent industry figure, Tahir Lakhani, 63, served as vice chairman of the UAE Shipping Association until 2019. Beyond his shipping career, he has claimed to be the youngest player ever to represent Pakistan in tennis’ Davis Cup, and got his start in the industry as a supervisor at a family friend’s ship recycling yard in Pakistan. He inherited a stake in a Dubai trading business through his marriage to wife Uneza in 1985, before renaming the venture Dubai Trading Agency; by the late 1990s, the firm had grown to become one of the world’s largest ship recyclers, purchasing more than 100 end-of-life vessels annually for cash.

    The case has also raised questions about the implementation of the 2021 UK-UAE Illicit Finance Partnership Agreement, a bilateral deal the British government hailed as a landmark effort to crack down on transnational crime, terrorist financing, and illicit money flows between the two nations. In March this year, Democratic Unionist Party MP Jim Shannon formally asked the Home Office to assess how the agreement applies to the Lakhani case, but Security Minister Dan Jarvis declined to comment on individual proceedings while reaffirming the stated benefits of the partnership.

    Middle East Eye, which publishes independent coverage of the Middle East, North Africa and global affairs, first obtained the court documents confirming the lifting of the travel ban on an exclusive basis.

  • Tata Sons extends Chandrasekaran’s term as chairman but a battle looms

    Tata Sons extends Chandrasekaran’s term as chairman but a battle looms

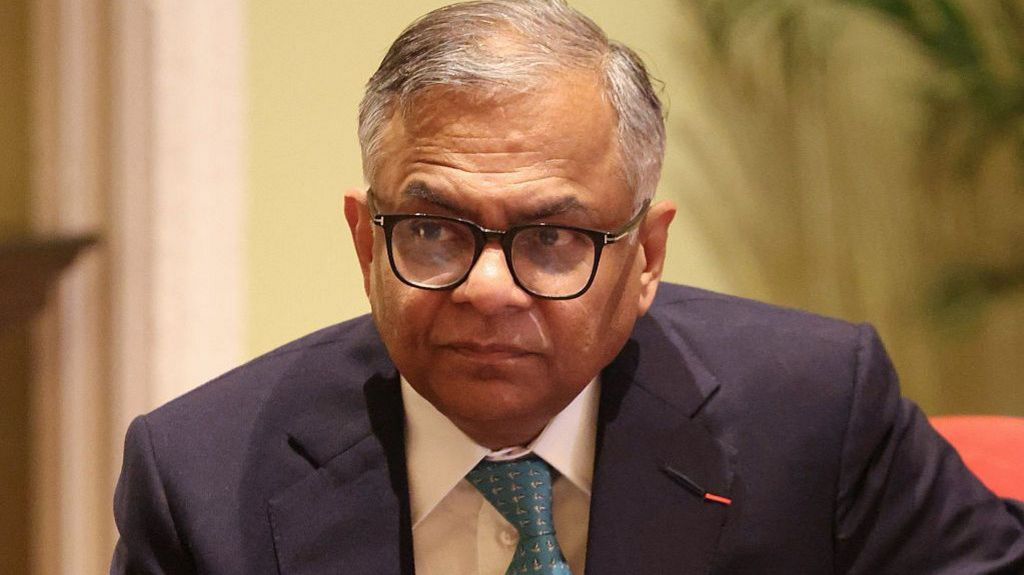
    India’s iconic Tata Group, one of the world’s largest and most diversified conglomerates with a $300 billion global footprint that includes brands like Air India, Jaguar Land Rover, and Tata Steel, while also handling iPhone manufacturing for Apple, is now facing unprecedented internal governance turmoil following a controversial board decision to reappoint N. Chandrasekaran as chairman for an additional five-year term.

    Chandrasekaran, who originally took on the chairman role in 2017, had previously announced last month that he would step down when his current tenure concludes in February. This announcement came after months of gridlock within the Tata Sons board, where members had failed to reach a unanimous resolution on extending his leadership. In a statement released Thursday, the Tata Sons board revealed that Chandrasekaran had reversed his earlier decision after being asked to reconsider his retirement plans, clearing the way for his reappointment once his current term expires.

    However, the move has sparked immediate pushback from Noel Tata, chairman of Tata Trusts—the charitable entity that holds a 66% majority stake in parent company Tata Sons. Noel Tata has labeled the reappointment as “illegal”, throwing the future leadership and strategic direction of the sprawling conglomerate into question. Despite this high-profile dispute, news of Chandrasekaran’s reappointment drove a sharp rally in share prices across publicly traded Tata Group companies on Thursday.

    The unique structure of the Tata Group has long been cited as a root cause of its current governance challenges. While Tata Trusts’ majority ownership has delivered tax and regulatory benefits, and enabled the group to advance extensive charitable initiatives, industry analysts have long noted that the overlapping of non-profit and commercial governance structures creates inherent tensions that can spill over into corporate decision-making. Tata Trusts holds three nominations on the Tata Sons board, and disagreements over key issues including board appointments, funding authorization, and the potential public listing of Tata Sons have been simmering for months.

    Beyond the leadership dispute, Thursday’s board meeting also marked a pivotal shift for the conglomerate: Tata Sons has agreed to comply with a recent directive from the Reserve Bank of India (RBI) that mandates the mandatory listing of the company. This requirement is a reversal of the group’s long-held opposition to listing, and comes shortly after the RBI rejected Tata Sons’ application to deregister its status as a non-banking financial company (NBFC) earlier this week.

    Industry experts widely view Chandrasekaran’s continued leadership as a critical factor in moving the listing process forward, a position that puts him directly at odds with Noel Tata, who has opposed both the listing mandate and Chandrasekaran’s retention as chairman. The internal rift became public knowledge last month when Chandrasekaran openly addressed the divisions, revealing that when his tenure extension was first proposed in February, at least one board member withheld support. He opted to defer a decision in the absence of unanimous backing, and after six months of failed negotiations to resolve the impasse, he made the decision to step down.

    In his statement Thursday, Noel Tata outlined the legal basis for his opposition, noting that while four directors voted in favor of reappointment, he as a Tata Trusts-nominated director voted against it. Under Tata Sons’ articles of association, a majority of Tata Trusts-nominated directors must support the measure for it to be valid. Noel Tata emphasized that the board cannot legally convene a meeting or pass a resolution on the chairman’s appointment or reappointment unless both of the required Tata Trusts-nominated directors are present, and cannot validly approve such a resolution without the support of both. “Given that Mr Noel Tata, being one of the Trust nominee directors, voted against the proposal, it was rendered legally void and without any basis,” his statement read.

    The ongoing dispute leaves India’s largest conglomerate at a crossroads, with competing claims of legitimacy over leadership and a critical regulatory mandate to implement listing that will reshape the future of the 150-year-old Tata Group.

  • China’s EVs, LLMs and the stopping power of the real world

    China’s EVs, LLMs and the stopping power of the real world

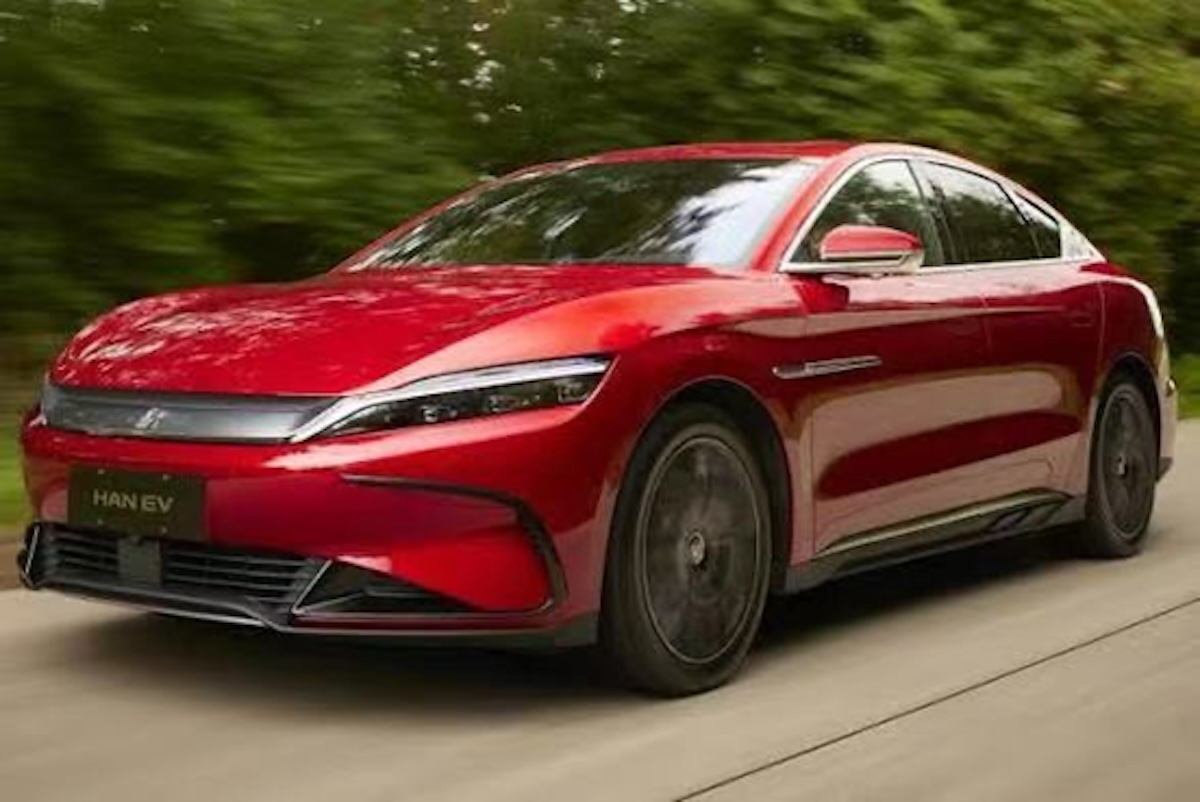
    Four years have passed since 2022, when a first-hand observer moving from Hong Kong to Beijing first encountered a deep crimson BYD Han electric sedan, impressed by its generous dimensions, comparable performance to Tesla’s Model 3, and competitive pricing that undercut the Tesla by 10% and fell 22% short of equivalent U.S. market tags. Today, that 2022 BYD Han already reads as a dated, budget-oriented commuter vehicle – a stark marker of how rapidly China’s electric vehicle sector has evolved.

    This period of rapid transformation mirrors another turning point in late 2022: just days before China lifted its strict zero-COVID public health measures, little-known U.S. startup OpenAI launched ChatGPT to the world, beating more conservative research teams at Google DeepMind to market and igniting a global arms race in large language models (LLMs). For years after that launch, the LLM space became a back-and-forth competition where OpenAI, Anthropic, and Google repeatedly one-upped each other, with smaller players like xAI trailing and Meta stumbling through multiple failed releases.

    Today in 2026, BYD has pushed aggressively into the premium luxury sedan market long dominated by German legacy brands. The new 2026 BYD Seal 08 is significantly larger than the 2022 Han, with game-changing upgrades across every core specification: from battery capacity and horsepower to self-driving systems, air suspension, and rear-wheel steering. The even larger flagship DaHan (Great Han) has moved into the full-size D-segment, a category historically occupied by the Mercedes S-Class, BMW 7 Series, and Audi A8. Even more striking than the technical upgrades is the pricing: the top-trim Seal 08 retails for $35,500, a 25% discount to the 2022 Han’s top trim, while entry and mid-level trims cost 10-15% less at $29,300 to $32,300. The fully loaded D-segment DaHan is priced identically to the 2022 top-trim Han, at just $44,700. For comparison, equivalent premium EV sedans from BMW, Mercedes, and Audi cost three to four times as much in the U.S. market while delivering broadly inferior specs and performance.

    This pricing gap has drawn open criticism from U.S. officials: in a September 2 speech at the Charlotte Economics Club, Treasury Secretary Scott Bessent complained that BYD vehicles are “the best $70,000 car $35,000 can buy – it is heavily subsidized.” A similar observation came from *The New York Times*, which tested a top-trim Geely M9 crossover in early 2026 and noted the $35,000 China-market price is less than half what a comparable vehicle from a U.S. showroom brand costs.

    But claims that unfair subsidies explain BYD’s price advantage do not hold up to scrutiny. Analysis from the Center for Strategic and International Studies (CSIS) shows 79.4% of China’s EV subsidies go directly to consumer purchase incentives such as tax exemptions and government rebates, and historically, per-vehicle EV subsidies in China have been substantially lower than those offered by the U.S. and EU. The key difference is outcome: China’s policy framework has driven 49 million cumulative EV sales since 2009, compared to just 8 million in the U.S. and 12 million in the EU. China’s success stems not from excessive spending, but from aligning industrial policy with the maturation of its higher education pipeline: the country’s EV industry draws from a talent pool of nearly seven times as many new engineering graduates as the U.S. In just a few years, China launched more than 100 EV manufacturers and flooded the global market with over 300 distinct EV models, while the U.S., EU, Japan, and South Korea combined have struggled to field just a few dozen offerings. Even accounting for 2026’s average per-vehicle subsidy of just over $2,000 and 30% renminbi appreciation, the gap in production costs and pricing cannot be explained by government support alone.

    The pace of improvement in China’s EV sector is unprecedented: since 2022, domestic manufacturers have delivered annual hedonic (quality-adjusted) improvement of 20% per year. Over four years, this means new Chinese EVs have more than doubled in effective quality: a 2026 EV with 2022-level specifications would cost less than half the 2022 price today, while a 2026-spec vehicle would have commanded more than twice the 2022 price four years ago. This rate of progress is almost unheard of in Western markets. The 2026 Tesla Model 3 is nearly identical to the 2022 version in core specs; while Tesla’s Autopilot has improved, Chinese self-driving systems have advanced even faster, and most include full self-driving capabilities in the base price, unlike Tesla’s paid subscription model. Even with a 7% price cut for the top-trim Model 3, Tesla has not kept pace. Honda’s 2026 Pilot is marketed as a new generation, with minor cosmetic changes and marginal gains in size and power, but no substantive improvements to core features or technology – yet the automaker raised prices by 9%.

    This pattern of rapid hedonic improvement is not limited to automobiles: it can be seen across nearly all consumer and industrial sectors in China, from budget luxury travel accommodations to a nationwide wave of investment in restaurant design that has brought high-end aesthetic experiences to mid-range dining.

    Parallel to China’s progress in physical manufacturing, the global AI industry has raced ahead, with OpenAI most recently launching its new Astra platform in September 2026. Just three days after Astra’s debut, OpenAI announced that an unreleased internal AI model had produced a solution to the century-old Navier-Stokes problem, sending the AI community into a frenzy over recursive self-improvement (RSI) and triggering existential anxiety that echoes the shock that hit chess and Go communities after AI defeated top human grandmasters. For practicing mechanical engineers, however, the fanfare is underwhelming: the Navier-Stokes equation has long been used as a simplified working model for fluid dynamics, and useful numerical simulations have been generated by commercial engineering software such as Ansys and OpenFOAM for decades. The mathematician-approved solution produced by OpenAI has no practical application in real-world engineering: real fluid behavior depends on hundreds of unaccounted-for variables, not the simplified framework used by mathematicians, and the solution would not improve the efficiency of a single airplane or the stealth of a single submarine.

    This gap between AI hype and real-world impact frames a larger global divide. U.S. frontier AI labs have dominated headlines and led development of cutting-edge LLMs over the past four years, but that leadership has not helped U.S. legacy automakers like Ford and General Motors close the gap with Chinese competitors such as BYD and Geely – a gap that has only widened in recent years. So far, the complexity of the physical world has humbled frontier AI efforts: while labs have rushed to integrate physics, chemistry, engineering, and biology capabilities into LLMs, these advances have yet to deliver measurable gains in real-world applied science. Meanwhile, Chinese universities have expanded their lead in the Nature Index, and Chinese industries outcompete global rivals even when relying on lower-cost open-source LLMs.

    To clarify the current state of AI development, a team of researchers from leading Chinese institutions including Tsinghua University, Bytedance, and Xiaohonghua outlined a five-stage framework for recursive self-improvement, the hypothetical process through which AI can improve itself without human intervention. At the lowest L1 stage, humans design the entire improvement pipeline, and AI only executes pre-defined steps. L2 sees AI autonomously select which components to improve, while humans still set core objectives and evaluation rules. At L3, AI identifies its own weaknesses and designs its own training curriculum to address gaps. L4 adds autonomous real-world feedback collection and self-updating during live deployment, without human curation. The highest L5 stage, full meta-improvement where AI can rewrite its own improvement algorithm, has not yet been achieved.

    The researchers note that the biggest barrier to advancing RSI is the slow iteration speed required for physical science and engineering. Prototyping and testing new car parts, running clinical trials, and validating real-world systems take far longer than testing new AI code. Because of this “stopping power of the physical world,” all applied work in physical sciences and engineering remains stuck between L1 and L2. Even self-driving cars, one of the most high-profile AI applications, illustrate this limit: while geofenced level 4 robotaxi pilot programs operate in cities across China, the U.S., and the Middle East, consumer vehicles for general use still rarely advance beyond level 2, requiring constant human vigilance for most driving scenarios outside limited highway stretches.

    This is not to dismiss the impressive achievements of modern LLMs, nor to downplay legitimate concerns about rogue AI and cyber warfare. But as the author, a former mechanical engineer, argues, AI researchers fixated on artificial general intelligence (AGI) often underestimate how much of economic and technological progress depends on work in the physical domain. For those caught up in AGI hype, the remedy is simple: step outside, engage with tangible physical work, and then return to recognize that real industrial progress depends on far more than breakthroughs in digital AI.
  • India’s biggest stock exchange launches mega share sale

    India’s biggest stock exchange launches mega share sale

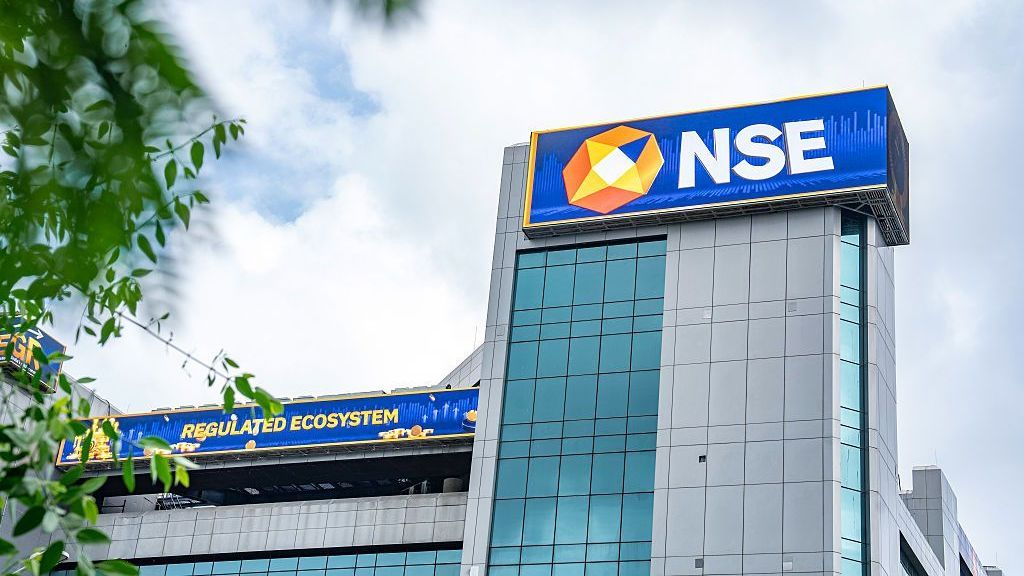
    After a decade of regulatory delays, market controversy, and shifting investor sentiment, India’s dominant National Stock Exchange (NSE) has finally launched its long-awaited initial public offering, positioning itself as one of the largest share sales in the nation’s history. The IPO, which gives the public its first chance to own a stake in the exchange that handles the bulk of India’s equity trading, is on track to raise up to 225.69 billion rupees, equal to roughly $2.35 billion. If successfully completed at that valuation, it will rank as India’s second-largest IPO ever, falling only behind the 2024 listing of Hyundai Motor’s Indian subsidiary.

    For global and domestic investors, the offering opens a direct pathway to capitalize on the exponential expansion of India’s financial markets, which have boomed as millions of middle-class households shift savings away from traditional assets like gold and real estate toward equities. However, the launch comes at a turbulent moment for Indian markets, with multiple macroeconomic pressures dragging benchmark valuations lower in 2025. Rising global crude oil prices, a depreciating rupee, and sustained capital outflows from foreign institutional investors have created a challenging environment for new share issuances. These headwinds have already forced adjustments to the IPO structure: late last week, existing stakeholders cut the total number of shares on offer by 15%, citing lower-than-expected valuation projections that made full sales unappealing.

    Priced between 1,700 and 1,785 rupees per share, the IPO is structured as a secondary share sale, meaning all proceeds will go to exiting investors including the State Bank of India, state-run insurance firms, and global investment funds. The NSE itself is not issuing new equity and will not receive any revenue from the offering.

    The mega IPO paves the way for another highly anticipated large listing, that of Reliance Industries’ digital subsidiary Jio Platforms, which is expected to hit the market in the coming months. Industry analysts note that these two large offerings carry dual potential for the broader Indian IPO market. On one hand, the combined size of the listings could draw capital away from already listed equities in the short term, creating mild downward pressure across broader market indices. On the other hand, a successful NSE and Jio Platforms offering could reverse a months-long slowdown in India’s IPO pipeline, where dozens of companies delayed listings in the first half of 2025 amid market volatility and rising geopolitical tensions. Analysts project that the two offerings alone could push the total capital raised through Indian IPOs in 2025 above 2024’s full-year total.

    The NSE’s path to a public listing has been anything but smooth. The exchange first filed for listing approval back in 2016, but the entire process was derailed by a high-profile controversy over market manipulation and governance lapses. Senior NSE officials were accused of granting preferential low-latency access to the exchange’s trading system to a small group of private brokers, giving those traders an unfair advantage over other market participants. The scandal led to years of regulatory investigations and oversight, only being resolved enough to clear the way for the IPO in recent months.

    Current market conditions remain far from ideal: the NSE’s benchmark Nifty 50 index, which tracks 50 of India’s largest blue-chip companies, has fallen more than 11% since the start of 2025. Even so, market analysts broadly expect robust demand for the offering, pointing to long-term structural growth tailwinds in India’s capital markets that outweigh short-term volatility. A growing wave of new retail investors entering the market via zero-commission trading apps has driven a sustained rise in trading volumes and market capitalization, and the NSE’s dominant position in the market makes it a pure play on that expansion.

    “NSE remains a play on the long-term growth potential of India’s capital market,” domestic brokerage ICICI Direct noted in a pre-IPO research note, adding that the exchange’s leading market share, consistent profitability, and heavy investment in trading technology make its business model unusually resilient to short-term market swings. Its large planned free-float market capitalization also makes it an attractive holding for both active retail and institutional investors, as well as passive index funds that will be required to add the stock to their benchmark portfolios once listed.

    Indian brokerage Religare Broking echoed that optimism in a recent report, noting that “India’s capital markets present significant growth opportunities, supported by rising investor participation, increasing market capitalisation, expanding mutual fund assets and greater adoption of passive investment products.”

    Still, the offering carries notable downside risks that investors are weighing. The NSE ranks as the world’s largest derivatives exchange by volume of contracts traded, and a large share of its revenue comes from transaction fees on derivatives trading. Indian financial regulators have recently tightened rules for derivatives trading amid growing concerns over widespread losses for inexperienced retail investors who speculate on price moves. Any future additional restrictions on derivatives trading, or a sustained drop in speculative trading activity, could cut into NSE’s transaction volumes and bottom line.

  • Watch: How will higher interest rates impact US consumers?

    Watch: How will higher interest rates impact US consumers?

    As the Federal Reserve navigates persistent inflationary pressures and a shifting labor market, the decision to raise interest rates has once again put household financial stability under the microscope. In a recent on-the-ground reporting piece, BBC correspondent Samira Hussain breaks down the complex economic drivers that have pushed the central bank toward higher borrowing costs, while exploring the ripple effects that will touch every corner of consumer finance across the United States.

    The Federal Reserve has long relied on interest rate adjustments as its primary tool to cool overheated economic growth and rein in runaway inflation. When rates climb, borrowing becomes more expensive for everything from mortgages and auto loans to credit card balances and small business lines of credit. This dynamic is designed to slow discretionary spending, which in turn eases upward pressure on consumer prices. But for everyday American households, the transition to a higher rate environment does not play out evenly, with variable impacts depending on individual financial circumstances.

    For consumers looking to purchase a new home or refinance an existing mortgage, higher interest rates translate directly to steeper monthly payments, pricing many entry-level buyers out of a market already strained by limited housing inventory. Existing holders of adjustable-rate mortgages also face growing payment obligations as their rates reset to reflect the new benchmark. Credit card users, most of whom carry variable rates tied to Fed benchmarks, will see their interest charges jump almost immediately, increasing the burden of carried balances. Even consumers saving for retirement or large purchases can face mixed outcomes: while high-yield savings accounts and certificates of deposit start offering more attractive returns, the value of existing bond holdings often drops as new bonds come with higher interest payments.

    Hussain’s reporting also contextualizes the Fed’s balancing act: policymakers are walking a fine line between taming inflation and avoiding tipping the overall economy into a recession. A sharp enough slowdown in spending could trigger job cuts in interest-sensitive sectors like housing, construction and retail, which would ultimately feed back into consumer financial health. By speaking with economists, industry analysts and everyday households, the report lays out both the intended consequences of the Fed’s policy move and the unexpected risks that could hit consumers who are already grappling with lingering price increases from years of high inflation.

  • US interest rates raised for first time in three years

    US interest rates raised for first time in three years

    In a historic, unanimous policy shift that marks the first increase to U.S. benchmark interest rates in more than three years, the Federal Reserve has raised its key policy rate by a quarter percentage point to a new range of 3.75% to 4%, pushing back against repeated public demands from former President Donald Trump to cut borrowing costs instead.

    The decision, announced Wednesday, comes as U.S. policymakers grapple with persistent, elevated inflation that has pushed household cost-of-living concerns to the top of the political agenda ahead of November’s midterm elections. Federal Reserve Chair Kevin Warsh framed the rate increase as a necessary, measured response to months of above-target price growth. “Inflation is too high and has been for too long,” Warsh told reporters during a post-meeting press conference, describing the move as a “sober” and “responsible” step to stabilize the economy. He emphasized that low-income households, which bear the brunt of rising prices for essentials like food and energy, stand to benefit the most from bringing inflation under control.

    The rate hike comes against a backdrop of soaring global energy prices, triggered by the outbreak of the US-Israel war with Iran that has disrupted energy markets and pushed diesel prices to all-time records in the U.S., with average gasoline prices climbing above $4 per gallon. Warsh acknowledged that the Fed cannot directly control individual price pressures such as oil or grocery costs, but argued that the central bank’s role is to prevent broad-based, sustained inflation from embedding itself across the entire economy.

    The decision puts the independent central bank on a direct collision course with Trump, who has repeatedly lashed out at Fed policy in recent years and made his opposition to the rate hike public ahead of the announcement. Trump argued that U.S. interest rates “should be 1%, or less, because we are the Best Credit in the World – BY FAR.” Following the announcement, he doubled down on his criticism in a post on social media, writing: “LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”

    White House press secretary Kush Desai told Fox News that the administration has “reiterated our commitment to the independence of the Federal Reserve on numerous occasions,” but added that Trump retains the right to publicly share his views on monetary policy. When pressed by reporters to respond to Trump’s criticism, Warsh deflected all questions about the president’s remarks. “I have got nothing for you on a discussion with the president,” he said, chuckling before repeating the response to follow-up questions. “Part of the independence of the Federal Reserve is we stay in our lane,” Warsh added.

    This rate increase is the first change to Fed policy in any direction since the central bank cut rates in December 2025, with the last previous rate hike occurring in July 2023. Trump had previously criticized Warsh’s predecessor, Jerome Powell, who stepped down at the end of his term earlier this year, for refusing to cut rates as Trump demanded.

    Higher interest rates work to cool inflation by making borrowing more expensive for consumers seeking mortgages, personal loans and credit cards, which discourages discretionary spending and encourages saving. While this eases upward pressure on prices, it also carries risks: higher rates can prompt businesses to pause investment plans, dragging on overall economic growth. For consumers, the rate hike will immediately translate to higher borrowing costs: major U.S. lenders including JPMorgan, KeyCorp and BNY Mellon moved quickly Wednesday to raise their prime lending rates from 6.75% to 7%, a shift that will push up rates for credit cards and consumer loans.

    Mortgage rates, which already climbed over the past year, have also moved higher as a result of the policy change. Current Freddie Mac data puts the average 30-year fixed mortgage rate at 6.76%, with the average 15-year fixed rate at 6.09%, still below the peak rates recorded in 2023. Most existing U.S. homeowners with fixed-rate mortgages will not see any change to their monthly payments, but prospective homebuyers and those seeking to refinance existing home loans will face higher borrowing costs.

    Looking ahead, Warsh declined to offer his personal outlook for future rate moves, but Fed policymakers’ collective projections point to additional rate increases on the horizon. A majority of policymakers expect the Fed will raise rates once more before the end of the year, pushing the benchmark rate into a range of 4% to 4.25%. A small majority of policymakers project rates will climb further to 4.25% to 4.5% in 2027, before the central bank begins cutting rates between 2028 and 2029. Projections also show inflation is expected to steadily decline over the coming years, hitting the Fed’s longstanding 2% target by 2029.

    The U.S. is far from alone in tackling inflation driven by Middle East conflict energy shocks: the European Central Bank raised its own interest rates last week, with the Bank of England set to announce its own monetary policy decision on Thursday.