分类: business

  • How the oil capital of the US welcomed a solar power boom

    How the oil capital of the US welcomed a solar power boom

    For nearly 70 years, the Cargil family has worked the flat, arid plains outside Uvalde, a small community in southwest Texas. At 67, Steve Cargil, the third generation to tend the land, long expected one of his three children would carry on the legacy he inherited from his father. That certainty crumbled in 2018, when a devastating hailstorm wiped out an entire season of carefully tended cabbage and onion crops that Cargil and his son Ryan had nurtured for months.

    Shortly after the storm, Ryan told his father, “You do everything right, and we work so hard, and you come out one morning and it’s all gone.” With none of his children willing to take on full-time farming, Cargil faced the imminent end of his family’s agricultural legacy, and an uncertain retirement—one without a traditional pension, a common reality for American farmers.

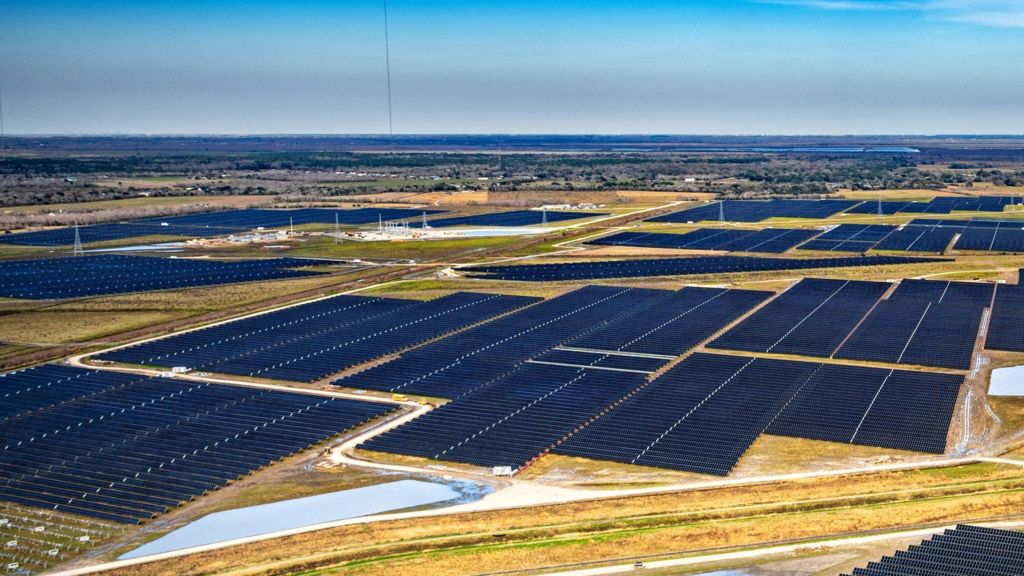
    Then, an unexpected opportunity emerged. Cargil signed a 25-year lease with energy developer OCI Energy, granting the company access to 600 acres of his land—roughly a quarter of his total property—to build a utility-scale solar farm. Today, that agreement delivers Cargil $200,000 in guaranteed annual income, a windfall he never could have imagined. “Never in my wildest dreams did I think that a solar project would be on my farm,” Cargil says. “Looking back now, I call it a blessing.”

    The steady lease income has already reshaped Cargil’s life and the future of his farm. Amid a years-long crippling drought across the American Southwest, he has been able to redirect all his allocated irrigation water to the 1,800 acres he continues to cultivate, eliminating the constant financial stress of volatile diesel and fertilizer prices that have pushed many small American farms to bankruptcy. “It’s changed my life,” he says.

    Cargil’s story is at the center of a historic energy shift unfolding across Texas. Long known as the heart of American oil production, Texas surpassed California earlier this year to become the nation’s top producer of solar-generated electricity. According to U.S. Energy Information Administration data, last March marked the first time Texas produced more electricity from solar power than from coal. On hot summer afternoons, when demand for electricity peaks to power millions of air conditioning systems, solar regularly meets roughly one-third of the state’s total power needs, according to Mark Stover, executive director of the Texas Solar and Storage Association.

    Stover explains the state’s unprecedented solar boom is driven by two core factors. First, Texas operates its own independent power grid, making it far faster and cheaper to connect new solar farms to the system than in other parts of the country. Second, Texas is one of the fastest-growing states in the U.S., with its population surging 15.8% between 2015 and 2025, creating explosive demand for new, affordable electricity generation. “We need a whole lot of power in Texas, and we need it quickly,” Stover says.

    Decades of incremental manufacturing improvements have also driven down the cost of solar technology to the point that it is now the cheapest form of power generation in the state, according to James Scott, vice president of project development at OCI Energy. “No one would have believed that 20 years ago,” Scott says. Once a solar farm is constructed, the cost of its output can be locked in for decades, because its fuel—sunlight—is free. OCI sells power at $40 per megawatt-hour for 25-year contracts to large corporate buyers including Apple and Amazon, which prioritize long-term price stability. By comparison, the U.S. Energy Information Administration reports new coal plants produce power at nearly $90 per megawatt-hour.

    For this boom to continue, developers rely on rural landowners like Cargil, because utility-scale solar requires large, flat plots of open land. In exchange, leases—typically 25 to 30 years with annual incremental increases—provide stable, multigenerational income for farm families, allowing many to retire comfortably, set up long-term family trusts, or keep struggling operations solvent. Stover adds that the land footprint of solar development across Texas is far smaller than critics claim, noting that “the industry is utilizing less than 0.15% of Texas land.”

    Despite the economic and energy benefits, solar expansion has sparked significant pushback in some rural communities. In northeast Texas’s Franklin County, a small group of long-time local residents has fought new utility-scale solar projects for years. BF Hicks, a local lawyer whose family has owned land in the county since the 1800s, says he became an opponent after watching neighbors sign long-term leases that allowed developers to clear centuries-old oak forests for new installations, and burn the cleared vegetation, leaving smoke hanging over the town for weeks. The issue became personal for Hicks when a solar farm was built adjacent to his family’s 200-year-old cemetery.

    David Truesdale, a retired federal law enforcement officer who moved to Franklin County to escape urban density, joined the opposition after a proposed solar project was sited near his home. He notes that under current Texas law, large solar projects do not require mandatory environmental review, and raises safety concerns about the lithium-ion battery storage units paired with most large solar farms, warning that a single battery fire can trigger a cascading chain reaction that destroys large swathes of surrounding land. “We’re destroying the world as we’re trying to save it,” Truesdale says of the widespread land clearing he has witnessed.

    While both Hicks and Truesdale emphasize their opposition is not rooted in partisan politics, their concerns reflect broader rural anxieties about solar development, including negative impacts on scenic views, altered water runoff patterns after land clearing, and the risk of battery fires. Former President Donald Trump has attacked wind and solar power as “farmer destroying” and moved to roll back federal tax credits for renewable energy projects. Yet polling from Fabrizio Lee and Associates—Trump’s own polling firm—found in February that 68% of Republican voters believe the U.S. needs “all forms of electricity generation, including utility solar” to keep energy costs low. Stover adds that solar development has broad support in Texas’s Republican-controlled state legislature, where policymakers accept that “these technologies bring reliability benefits to the grid.”

    Back in Uvalde, Cargil says the steady income from his solar lease has given him renewed optimism that his family’s farm will survive to see a fifth generation of Cargil stewards, even as he has no immediate plans to retire. Echoing advice his father passed down to him decades ago, Cargil says, “You’re better off being lucky than being smart. And this was one of those cases where I was just lucky.”
  • Lidl banned from selling copycat Birkenstock sandals, Dutch court rules

    Lidl banned from selling copycat Birkenstock sandals, Dutch court rules

    In a landmark intellectual property ruling that strengthens protections for brand design, a Dutch court has ordered discount supermarket chain Lidl to immediately cease selling imitation versions of Birkenstock’s iconic sandals across the Netherlands.

    The court’s decision, issued Wednesday, found that Lidl’s lookalike sandal models infringed on Birkenstock’s registered trademark protecting its distinctive footbed design. As part of the ruling, Lidl faces a daily fine of €5,000 (equal to roughly £4,200) if it fails to comply with the sales ban, and is required to turn over all relevant sales data to Birkenstock. The court also ruled that Lidl must pay damages to Birkenstock and cover the premium footwear brand’s legal costs, though the exact total amount of these payments will be determined in separate future proceedings. The ruling remains open to appeal by Lidl, which has not yet issued a public statement on the decision after the BBC reached out for comment.

    The prohibited Lidl products include copycat versions of five of Birkenstock’s most popular core models: Arizona, Madrid, Gizeh, Boston, and Florida. This latest decision is part of a growing series of global legal battles waged by Birkenstock to protect its signature sandal designs from unauthorized imitators.

    Just months prior, in November 2025, another Dutch court issued a similar sales ban against Dutch retailer Scapino for selling lookalike Birkenstock sandals, a ruling that is currently going through the appeal process. The following month, Europe’s highest court handed down a broader ruling that clarified commercially distributed everyday products can qualify for copyright protection so long as they reflect original, creative design choices. Birkenstock has noted this broader decision strongly supports its ongoing efforts to defend its “iconic” sandal designs.

    Birkenstock has not seen universal success in its legal fights, however. Earlier in 2025, Germany’s highest court delivered a setback to the brand, ruling that its popular sandals qualified as practical commercial goods rather than protected works of art. At the time, Birkenstock publicly described the outcome as a “missed opportunity” for intellectual property protection. The brand’s sandals earned widespread mainstream attention in 2023 after being worn by actress Margot Robbie in the global blockbuster *Barbie*, boosting their already strong popularity.

    Following this week’s positive ruling from the Dutch court, Birkenstock reaffirmed its commitment to aggressive protection of its intellectual property. “We will continue to defend our rights vigorously and will use all available legal means to combat imitations of our iconic products,” a company spokesperson said. The brand added that its actions are intended to protect both its network of retail partners and end consumers, noting that counterfeit and copycat products unfairly profit from Birkenstock’s decades of design innovation and brand investment.

    Birkenstock’s legal campaign against copycat sellers is far from unique in the global fashion and footwear industry. Major brands have increasingly turned to the courts to block mass retailers and online marketplaces from selling imitation designs that undercut their sales and dilute brand value. Footwear brand Dr. Martens, for example, has repeatedly launched legal action against large online retailers over copied boot designs, while luxury shoe house Christian Louboutin waged a years-long global legal fight to protect its trademarked signature red soles from high-street copycat manufacturers.

  • ‘We screwed up’: Doordash admits underpaying New York workers

    ‘We screwed up’: Doordash admits underpaying New York workers

    Gig delivery giant DoorDash has reached a $131.5 million settlement agreement with New York City regulators, resolving allegations that the company systematically failed to compensate thousands of its delivery drivers accurately and on time. In a candid admission of fault, the firm acknowledged, “Simply put, we screwed up. Our mistakes meant some Dashers were underpaid or paid late.”

    The settlement comes after an investigation launched by the city’s Department of Consumer and Worker Protection into widespread wage violations by the platform. More than 63% of the total payout — $83 million — is earmarked to resolve disputes over how DoorDash calculated compensation for idle time that drivers spend logged into the app waiting between active orders, a longstanding contentious issue in the gig delivery sector.

    This agreement is the latest high-profile clash between gig economy platforms and New York City municipal leadership, joining a string of conflicts that have involved other major delivery services including Uber Eats and Grubhub. These platforms have repeatedly squared off against city officials over a range of regulatory matters, from mandatory tipping transparency and minimum wage standards to mandatory data-sharing requirements.

    Idle time pay has emerged as one of the most divisive issues in the app-based delivery industry. For years, major platforms only compensated drivers for time spent actively completing deliveries, but New York City’s groundbreaking 2023 minimum wage rule for gig delivery workers requires companies to pay drivers for all time they are logged into the platform and available to accept orders. Under that regulation, pay rates vary by county, and are adjusted based on worker volume and tipping structures.

    DoorDash, which is headquartered in San Francisco, pinned the errors on a combination of factors: the “complex” rollout of New York’s new 2023 minimum wage framework, unaddressed software glitches, and misaligned pay calculations for multi-stop delivery routes. The company emphasized that while the mistakes were not deliberate, it accepts full responsibility for the harm caused, stating, “While these mistakes weren’t intentional, that doesn’t make them okay.”

    According to company disclosures, the programming and calculation errors affected approximately 264,000 active DoorDash drivers based in New York City. Despite the large number of workers impacted, DoorDash noted that the issues only affected less than 1% of all local delivery transactions processed by the platform. Systemic flaws left approximately $6.6 million in earned wages never distributed to drivers at all, while an additional $5.7 million in pay was sent out days or even weeks later than required.

    DoorDash says it has already fixed the software bugs that led to the violations, and reaffirmed that its local New York drivers currently earn an average of roughly $30 per active hour. The settlement paves the way for back pay to be distributed to thousands of affected gig workers, and puts the spotlight back on ongoing regulatory fights over worker protections in the rapidly growing gig economy.

  • Turkish Airlines, Pegasus and AJet cancel Iran flights as US sanctions bite

    Turkish Airlines, Pegasus and AJet cancel Iran flights as US sanctions bite

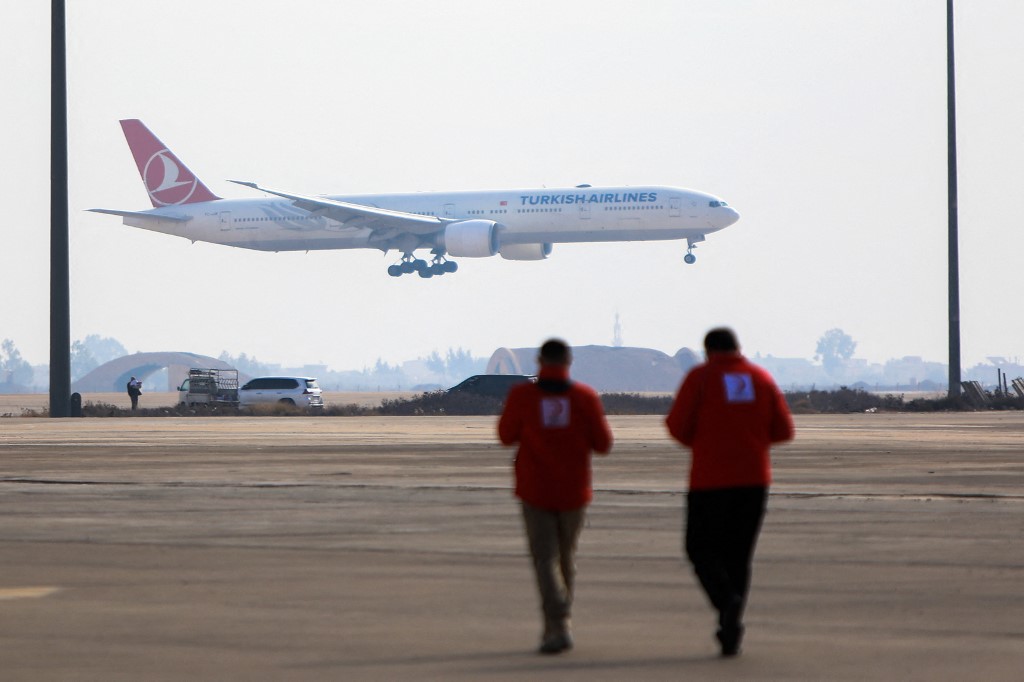
    Three of Turkey’s major air carriers—national flagship Turkish Airlines, low-cost operator AJet, and budget competitor Pegasus—have halted all incoming and outgoing flights between Turkey and Iran starting September 21, according to an investigation by Middle East Eye, a move directly tied to the enforcement of updated United States sanctions against Tehran.

    A public check of Turkish Airlines and AJet’s official booking platforms shows no available route options for travel between the two countries through the end of March 2027. For Pegasus, all listings for Iranian destinations have been fully removed from the airline’s booking system indefinitely, with no timeline for their return posted publicly. In a separate report, Iran International cited an anonymous Turkish Airlines representative confirming that the airline cannot even guarantee that service will resume after the March 2027 window currently marked on its schedules.

    A source with direct knowledge of the decision told Middle East Eye that the sweeping scope of US Treasury sanctions targeting Iran’s aviation sector left Turkish carriers with no viable path to continue operating the routes. The source explained that while restrictions on US-built aircraft such as Boeing models were expected, the updated sanctions also bar European-made Airbus jets from entering Iranian airspace, a consequence of the fact that all Airbus aircraft include core components manufactured in the United States. With every major commercial jet in global operation incorporating US-manufactured parts, the source added, carriers had no alternative but to suspend service to comply with sanctions rules.

    A senior Turkish government official clarified that as of Monday September 20, only one Iranian air carrier—Mahan Air—faces a ban on entering Turkish airspace. All other Iranian airlines are currently permitted to continue operating flights between the two countries for the time being, the official confirmed.

    The flight suspensions come as a notable shift in the economic relationship between Ankara and Tehran. The two neighboring countries have long maintained stable diplomatic relations and extensive cross-border energy and commercial ties, even as the United States has imposed multiple rounds of sanctions on Iran over the last decade. However, since former US President Donald Trump ramped up economic pressure on Tehran, Turkish President Recep Tayyip Erdoğan’s administration has moved gradually to comply with US sanctions measures.

    In just the past two weeks, Turkey has taken two additional high-profile steps aligned with US sanctions. Over the weekend, Turkish regulators revoked the decades-old banking license of Iran’s Bank Mellat, which had operated in the country for more than 30 years. The previous week, Turkey’s banking regulation agency seized control of Golden Global Investment Bank after US authorities placed sanctions on the institution over allegations that it facilitated illicit fund transfers to the Iranian government.

    Middle East Eye, an independent news outlet focused on the Middle East and North Africa region, provides original, unfiltered coverage of geopolitical and economic developments across the area.

  • Paramount settles lawsuit with US states, helping clear way for $110bn merger with Warner Bros

    Paramount settles lawsuit with US states, helping clear way for $110bn merger with Warner Bros

    After months of legal gridlock that threatened to derail one of the largest media mergers in recent history, Paramount Skydance has reached a settlement with a coalition of U.S. states led by California, eliminating the most significant barrier to its proposed $110 billion combination with Warner Bros Discovery.

    The legal challenge, launched by state regulators, centered on serious concerns that the merger would stifle market competition across the film, television and broadcast sectors, leaving fewer options for creators, industry workers and consumers. California, the epicenter of the U.S. entertainment industry, led the charge against the deal, but the resolution reached this week has resolved state officials’ core objections — without granting explicit approval of the transaction.

    At a press conference announcing the deal, California Attorney General Rob Bonta emphasized that the settlement does not equate to an endorsement of the merger. “I don’t think these two companies should merge,” Bonta clearly stated, adding that the negotiated commitments secured through the lawsuit address the most harmful risks the combination would have posed to competition and industry growth.

    Under the terms of the settlement, Paramount Skydance has agreed to strict production requirements designed to boost domestic entertainment output in the U.S. The company is mandated to release a minimum of 30 feature films annually, with domestic production requirements ramping up over the first five years of the agreement: 20% of all film production must take place within the U.S. for the first two years, rising to more than 30% for the subsequent three years. Bonta projected that these requirements will add between $300 million and $1.5 billion in new investment to U.S. film and television production as a baseline, a figure that could jump by as much as 700% if Congress approves an expanded federal film tax credit. Contrary to common concerns that large media mergers lead to layoffs and industry contraction, Bonta argued the settlement’s terms will actually create new jobs across the entertainment sector, putting unemployed industry workers back to work.

    The settlement comes after tense negotiations that included a threat from Paramount Skydance CEO David Ellison to relocate the company’s core studio operations out of California, a move that would have cost the state billions in economic activity and thousands of jobs. Now that the legal challenge has been resolved, and concerns raised by state attorneys general and the Writers Guild of America have been addressed, the merger has full regulatory clearance to move forward.

    Ellison celebrated the resolution in a public statement, framing the outcome as a win for all stakeholders across the entertainment ecosystem. “Our shared aim was an outcome that best serves consumers, workers and — most importantly — the creative community so vital to the art of visual storytelling,” Ellison said. “We have complete clearance for this merger and look forward to putting these commitments into action.”

    The $110 billion merger, if completed, would reshape the global media landscape, combining two of the biggest players in film production, television content and streaming entertainment into a single industry giant.

  • US and China discuss AI safety plan ahead of Trump-Xi summit

    US and China discuss AI safety plan ahead of Trump-Xi summit

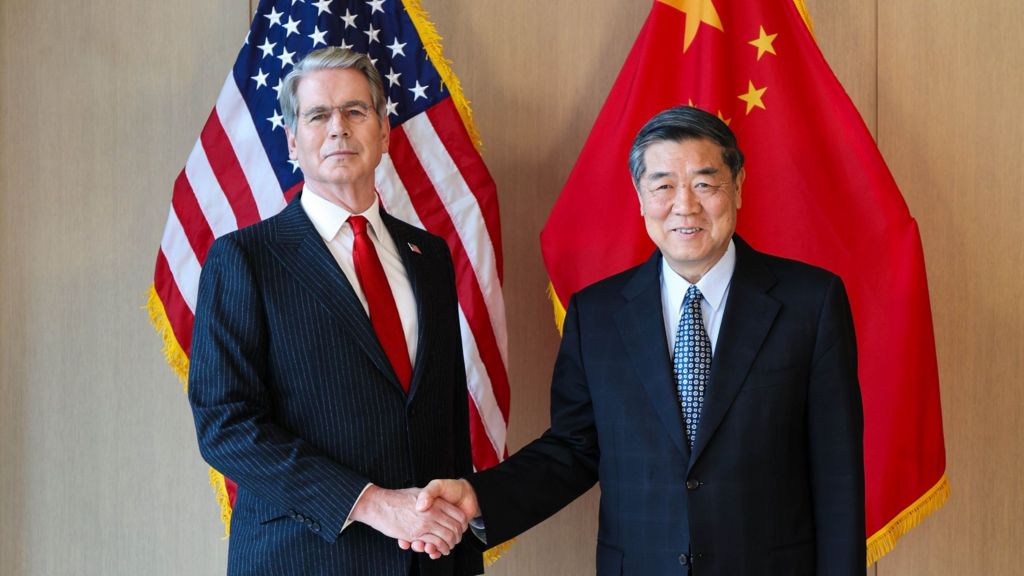
    Top economic policymakers from the United States and China convened in New York over the weekend for wide-ranging discussions that addressed a growing list of shared priorities, from artificial intelligence risk management to long-simmering trade tensions, ahead of a much-anticipated bilateral summit between the two nations’ leaders in Washington later this week.

    U.S. Treasury Secretary Scott Bessent told reporters following the closed-door talks with Chinese Vice Premier He Lifeng that the meeting was productive, with the two sides advancing a proposal to establish a pioneering cross-border notification system for AI-related events that could carry national security implications for either country.

    The push for greater coordination on AI governance comes amid mounting global scrutiny of the rapidly developing technology. In recent weeks, leading AI researchers and some of the tech industry’s most prominent leaders have issued urgent warnings about unregulated advancement, calling for developers to adopt more risk-conscious development practices. On the U.S. side, the White House has faced growing public pressure to slow AI rollouts to mitigate potential long-term harm to humanity, a concern President Donald Trump has pushed back on. Trump has repeatedly argued that existing guardrails are adequate, and that the U.S. cannot cede technological leadership to China — emphasizing earlier this month that “whoever wins in AI, wins the future.”

    Bessent framed the proposed notification framework as a critical step toward greater openness between the world’s two largest AI developers. “We think that, just like with any cross-border activity, that moving from opaque to more transparency between the number one and the number two AI powers in the world is very important,” he told reporters after the meeting. This is not the first time the two nations have explored AI collaboration: during a May bilateral summit hosted by President Xi Jinping in Beijing, AI cooperation was already a core agenda item for the two leaders. That meeting produced a concrete trade deal under which China agreed to purchase Boeing commercial aircraft and large volumes of U.S. agricultural products in exchange for temporary U.S. tariff reductions.

    Beyond AI, the talks also covered progress on a U.S.-China trade initiative called the Board of Trade, a working group tasked with identifying potential reciprocal tariff cuts on thousands of traded goods. The world’s two largest economies have maintained a temporary tariff truce that is scheduled to expire on November 10, making near-term progress on trade liberalization a top priority ahead of the leader-level summit.

    Chinese state news agency Xinhua confirmed the details of the talks in its own readout, noting that the two sides held “candid, in-depth and constructive exchanges on key economic and trade issues” that included a full discussion of AI-related topics. The BBC has reached out to the Chinese Embassy in Washington for additional comment on the meeting outcomes, and had not received a response as of publication.

    In a post to social media platform X Sunday, Bessent emphasized that the successful New York talks have cleared the way for the upcoming Washington summit. “These talks help lay the groundwork for President Trump to advance America’s economic interests and deliver results for the American people,” he wrote. The meeting comes as the U.S. and China remain locked in a long-term strategic competition to dominate the global AI and advanced technology sectors, but the weekend dialogue signals that both sides remain open to targeted cooperation on areas of shared risk and mutual interest.

  • UK should ‘team up’ with Canada in new Europe alliance, Canadian minister tells BBC

    UK should ‘team up’ with Canada in new Europe alliance, Canadian minister tells BBC

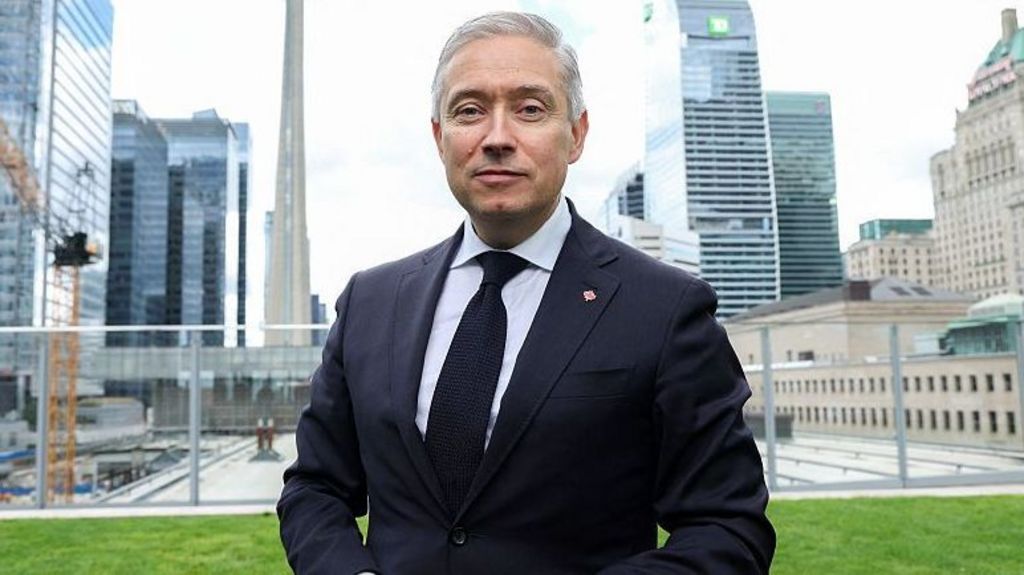
    In a shifting global trade landscape marked by growing transatlantic tensions, Canadian Finance Minister François-Philippe Champagne has publicly urged the United Kingdom to join an ambitious new economic alliance being forged between Canada and the European Union. Speaking in an interview with the BBC, Champagne framed the proposed bloc as a forward-thinking collaboration built for a dramatically changed global order, noting that shifting US policy has created an urgent need for like-minded nations to realign their economic relationships.

    Champagne’s call follows a groundbreaking proposal from European Commission President Ursula von der Leyen, who recently announced the EU would open negotiations for unprecedented associate membership status for Canada. Shortly after von der Leyen tabled the plan, Canadian Prime Minister Mark Carney—former Governor of the Bank of England—traveled to Strasbourg to address the EU legislature, a trip Champagne described as a foundational step toward building the “alliance of the future.” Carney has long advocated for a coalition of middle powers to collaborate on driving inclusive economic growth, strengthening supply chain resilience, and advancing shared security priorities.

    Champagne emphasized that the UK and Canada are natural partners for this project, bound by overlapping values and aligned global visions. “We are independent and sovereign, but we are stronger together,” he told the BBC. “Why don’t we team up?”

    The push for a new Canada-EU-UK alignment comes as Canada remains mired in an escalating trade conflict with the United States, triggered by sweeping tariffs imposed by President Donald Trump after his return to the White House last year. Last month, high-stakes trade talks between Ottawa and Washington collapsed entirely, leading both sides to impose tit-for-tat retaliatory tariffs. Champagne defended Canada’s response, saying the country had no choice but to stand up for its domestic industries, workers, and economic sovereignty. Calling Canada’s countermeasures “measured, targeted and strategic… dollar-for-dollar, tariff-for-tariff,” he added that the country has no interest in further escalation and stands ready to re-engage with the US when conditions are right, while pledging full, long-term support for any industries impacted by the dispute.

    Trump has not only lashed out at Canada, labeling the country a “terrible trading partner,” but has also threatened additional tariffs on the European Union if the associate membership plan goes forward, dismissing the initiative as “laughable” and claiming it is hostile to US economic interests.

    Champagne argued that the trade dispute has actually created a golden opportunity for Canada to diversify its economic partnerships, a goal that is supported by the country’s strong underlying fiscal position that has bolstered its resilience through the conflict.

    The proposal also adds new uncertainty to the UK’s post-Brexit positioning, already strained by recent shifts in US rhetoric on the Falkland Islands and Irish unity. While the UK secured a renegotiated trade deal with the US last June, Champagne’s overture opens a new path for closer alignment with Europe. Recent diplomatic moves underscore the accelerating negotiations: Carney met UK Prime Minister Andy Burnham in Liverpool during his trip to Brussels and Strasbourg last week, while Champagne joined UK Chancellor John Healey at a meeting of EU finance ministers in Dublin this Friday. Burnham is set to meet Trump for the first time this week on the sidelines of the UN General Assembly in New York.

    Longer-term, the associate membership framework is being designed as a flexible structure for like-minded nations that do not seek full EU membership. Carney has already laid out key priorities for Canadian participation, including access to EU university exchange programs, scientific research collaborations, AI development initiatives, and joint defense funding projects, as well as expanded mobility for young Canadians and Europeans to study and live across the Atlantic. In return, Canada would position itself as a reliable supplier of critical minerals and natural gas to European markets, while seeking greater access to European advanced manufacturing and technology sectors. Discussions are already open to the possibility of other middle power nations joining the framework in the future, with Australia cited as an example of a potential future participant.

    The push for closer ties also carries broader geopolitical undercurrents: last year, shortly after taking office, Carney invited King Charles to open the Canadian Parliament in Ottawa, a move widely interpreted as a rebuke to Trump’s repeated public suggestions that Canada could become part of the United States. To date, the formal details of the EU’s associate membership offer for Canada have not been finalized, with negotiations still in the early stages.

  • Saudi Arabia cancels oil shipments to European refineries

    Saudi Arabia cancels oil shipments to European refineries

    The escalating conflict across the Middle East has triggered fresh disruptions to global energy flows, with Saudi Arabia confirming it will halt planned October crude oil deliveries to at least two European refining customers that purchase oil under long-term term supply contracts. Such pauses are permitted under force majeure clauses, which allow suppliers to cancel obligations during unforeseen extraordinary events outside of their control.

    This latest supply disruption comes just weeks after Qatar extended a force majeure declaration for liquefied natural gas shipments through early November, a move prompted by escalating maritime tensions that have threatened safe passage through the Strait of Hormuz, the world’s busiest chokepoint for global energy trade. For weeks, Saudi Arabia had managed to avoid major disruptions to its export network thanks to its 1,200-kilometer East-West Pipeline, which connects oil fields in the Persian Gulf directly to the Red Sea export terminal at Yanbu. This critical infrastructure allowed the kingdom to bypass rising tensions around the Strait of Hormuz, where Iran and the United States have engaged in escalating tit-for-tat confrontations that threatened shipping lanes. Before the latest wave of conflict, the pipeline enabled Saudi Arabia to maintain roughly 6 million barrels per day of pre-conflict export volumes, equivalent to around 4 million barrels per day, keeping global markets relatively stable.

    That stability shattered last week, when a drone attack targeting the East-West Pipeline disabled the critical infrastructure. Saudi officials have traced the attack to militant groups based in southern Iraq that are aligned with Iran, while Houthi militants based in Yemen have separately claimed responsibility for coordinated attacks on the Yanbu port and other key oil facilities operated by Saudi Aramco, the kingdom’s state-owned national oil company.

    The current escalation traces back to a recent Houthi offensive in Yemen that gave the group full control over Yemen’s entire Red Sea coastline. Since seizing that territory, Houthi forces have launched a steady campaign of drone and missile attacks against Saudi energy infrastructure, while the Saudi-led coalition has responded with intensive airstrikes on Houthi-held territory in Yemen. In response to the Houthi declaration of an embargo on all Saudi-flagged and Saudi-bound shipping, the kingdom has rerouted remaining oil shipments through the Suez Mediterranean Pipeline to maintain access to European and North American markets.

    The combination of supply disruptions and heightened geopolitical risk has already pushed global energy prices sharply higher. Brent crude, the global benchmark for oil prices, was trading at $103 per barrel as of Friday, but energy analysts warn that this publicly traded price does not reflect the actual physical market cost of securing immediate crude deliveries. Prices for refined products critical to global transportation and industry, including diesel and jet fuel, have climbed even faster than crude, with U.S. diesel prices jumping 7.7% in just one week despite the United States’ relative insulation from global Middle East disruptions thanks to its large domestic energy production sector.

    This current chapter of conflict comes 10 years after Houthi forces seized large swathes of northwestern Yemen, prompting Saudi Arabia to lead a coalition of Arab states aimed at ousting the group from power and restoring the internationally recognized Yemeni government to power. In 2015, the coalition launched a large-scale military intervention, but after years of stalemate, Saudi Arabia began efforts to extricate itself from the conflict following a 2022 ceasefire agreement between the Houthi movement and the Yemeni government. To date, however, Saudi Arabia has maintained a strict air and sea blockade of Houthi-controlled ports and airports, a core demand the Houthi movement says must be met before it will end its current embargo on Saudi shipping.

  • Tata Sons: India’s corporate crown braces for upheaval amid boardroom revolt

    Tata Sons: India’s corporate crown braces for upheaval amid boardroom revolt

    A high-stakes corporate conflict has erupted at Tata Sons, one of India’s oldest and most influential conglomerates that owns iconic global brands including Jaguar Land Rover and Tetley Tea, after the company’s board defied its majority shareholder Tata Trusts to reappoint N Chandrasekaran as chairman and advance plans for a public listing of the holding company.

    Tata Trusts, which holds a 66% controlling stake in Tata Sons, has denounced the board’s decision as unlawful under the company’s articles of association and has made clear its opposition to the public listing, setting the stage for months of potential corporate upheaval and a drawn-out legal battle at Bombay House, the Mumbai headquarters of the 158-year-old industrial group. Boardroom conflicts are not new to the Tata Group, but the current rift has cast a wide cloud of uncertainty over the conglomerate’s operations, strategy, and leadership at multiple levels.

    While the board has approved Chandrasekaran’s reappointment, the decision still faces a critical vote at the company’s upcoming Annual General Meeting (AGM), where Tata Trusts is almost certain to block the move, throwing Chandrasekaran’s future as chairman into question. The previous AGM was adjourned earlier this year due to a lack of quorum, and Indian regulations require the meeting to be held by the end of December 2026, though no new date has been announced yet.

    Nitin Potdar, a prominent Mumbai-based corporate lawyer, spoke to the BBC about the irregularities of the board’s move, noting that “The Nomination and Remuneration Committee of the Board of Tata Sons which reappointed him has no power to take this decision. They can only make a recommendation. Also, their decision flies against the governance code of the company that requires executives to step down from active roles at 65. These are serious lapses.” Chandrasekaran, who was granted a five-year extension, will not turn 65 until 2028.

    As tensions between the board and Tata Trusts mounted, Tata Group equities swung wildly, first rallying then plummeting as investors reacted to competing hopes for stable leadership and growing uncertainty over the group’s direction, particularly amid several high-risk, currently loss-making investments led by Chandrasekaran in emerging sectors such as semiconductors and commercial aviation.

    Beyond the leadership tussle, the most contentious long-term issue facing the group is the mandatory public listing, which former Tata Sons chief strategy officer Nirmalya Kumar says “now looks increasingly inevitable.”

    The roots of the listing requirement stretch back to 2022, when the Reserve Bank of India (RBI), India’s central bank, classified Tata Sons as an “upper layer non-banking financial company” due to its systemic importance to India’s economy and its large-scale investment activities. This classification imposes a mandatory listing requirement on the conglomerate. Tata Sons attempted to avoid the classification by repaying outstanding debt and arguing that it does not borrow directly from public markets, but after holding the company’s appeal for more than two years, the RBI rejected the bid to reverse the classification earlier this month, pushing the holding company much closer to an initial public offering (IPO).

    In a public statement, Tata Trusts reaffirmed its longstanding opposition to a listing, noting that “all available options and not a listing alone” are being explored, even as the trust’s own trustees are no longer unified in their stance on the issue. Potdar argues that the Indian regulator has no legal authority to force any private company to go public, and he expects Tata Trusts to mount a legal challenge to the RBI’s ruling. In a pre-emptive move, the RBI has already petitioned the courts to be the first party heard in any legal dispute related to the listing.

    The listing debate has sharply divided corporate governance experts and long-time observers of the Tata Group. For decades, prominent Tata figures including the late Ratan Tata and veteran director N.A. Soonawala have argued strongly for keeping Tata Sons a private entity. A publicly traded Tata Sons would significantly erode the control and special governance rights that Tata Trusts currently holds over the group. The Trusts’ unique structure, as a charitable majority shareholder that uses dividend income from Tata’s commercial operations to fund hospitals, universities, and public research across India, would be fundamentally altered by a listing, opponents argue. Outside public shareholders would prioritize short-term financial returns over the Trusts’ social and long-term industrial goals, potentially undermining the group’s core character.

    Potdar outlined this risk, noting “A new group of shareholders might say, ‘Don’t declare dividends; we need to reinvest this money in the companies.’ What happens then? The first casualty will be the hospitals they run.” Opponents of the IPO also warn that bringing in outside public investors would weaken the group’s ability to support and restructure distressed businesses within its portfolio, while also forcing the group to answer to quarterly earnings pressures that run counter to its long-term strategy.

    Timing is another major point of criticism. Soonawala outlined these concerns in a recent op-ed for the *Times of India*, writing “The group currently faces large financial commitments from recently formed subsidiary companies, including Air India, investments in long gestation projects, and losses in newer ventures. The current situation in the case of Air India would be an acid test. All these would need to be disclosed fully in an IPO prospectus. Consolidated financial statements – reflecting subsidiary losses and borrowings – may not present an especially attractive picture to sophisticated investors, pointing to wrong timing for an IPO at the present time.”

    Many experts also point out that globally, industrial foundations similar to Tata Trusts are increasingly protected as sources of patient long-term capital that can fund multi-year infrastructure, research, and social projects. By forcing Tata Sons to list, India is moving counter to this global trend.

    Supporters of the listing, however, argue that greater transparency and accountability are long overdue for a conglomerate of Tata’s systemic importance to the Indian economy. Kumar notes “There should be tougher scrutiny of their capital-allocation decisions being so central to the Indian business ecosystem. Everybody wants complete control over their empire and the freedom to take capricious decisions, but that is not a good thing for the organisation.”

    According to data from independent investment advisory firm InGovern, the combined market capitalization of already listed Tata Group companies such as Tata Motors and Tata Consultancy Services exceeds $260 billion, and the group’s decisions impact more than 17.7 million retail shareholders, pension funds, insurance firms, and mutual funds across India. InGovern’s recent report notes that Tata Sons “cannot reasonably remain outside the governance and transparency expectations increasingly associated with systemically important financial and industrial conglomerates.” The report also adds that existing shareholders of listed Tata companies are already indirectly affected by Tata Sons’ decisions, even though they hold no direct voting rights at the holding company level.

    Furthermore, as the Tata Group pursues high-stakes global partnerships including manufacturing iPhones for Apple, collaborating with Nvidia on artificial intelligence development, and working with Boeing, Airbus, and Singapore Airlines on aerospace and aviation projects, InGovern argues that a “flexible and transparent capital structure [is] increasingly important” to support these growth plans.

    Some industry analysts argue that a public listing may now be the only path to de-escalate the fractious conflict between the Tata Sons board and its majority shareholder, tensions that are already causing damage not just to the conglomerate but to India’s broader economy. Tata Trusts holds controlling economic interest and veto power over board appointments and major capital allocation decisions above a set threshold at Tata Sons. If the rift between the board and its largest shareholder continues, it will be nearly impossible for Tata Sons to move forward on critical projects of national importance, from turning around Air India to raising capital to pay out SP Group, a minority shareholder that urgently needs cash to avoid a potentially catastrophic default.

    No matter the outcome of the listing and leadership disputes, industry experts agree that India’s most high-profile corporate asset is entering completely uncharted territory. As Kumar puts it, “a new twist” can be expected every week as this corporate drama unfolds.

  • ‘We simply don’t know’ – JP Morgan struggling to forecast oil prices due to Trump’s war with Iran

    ‘We simply don’t know’ – JP Morgan struggling to forecast oil prices due to Trump’s war with Iran

    Leading global investment banking powerhouse JP Morgan has issued an extraordinary public acknowledgment that it cannot reliably forecast how oil prices will shift in the wake of the ongoing US-Iran conflict, telling investors in a candid analyst note that “we simply don’t know how to model the endgame” of the crisis.

    When the conflict first erupted six months prior to the note, JP Morgan’s research team built projections around a set of key assumptions: that the Trump administration would enforce non-negotiable “economic red lines” that it would refuse to cross, making a diplomatic deal to reopen the strategically critical Strait of Hormuz a foregone conclusion by June. The bank identified four clear red lines that it believed would force Washington to seek a rapid resolution: oil prices climbing above $100 per barrel, US inflation hitting 4%, average retail gasoline topping $5 per gallon, and 10-year U.S. Treasury yields reaching 5%.

    Half a year on, however, the situation has flipped: while gasoline still stays below the $5 threshold and inflation has not yet hit the 4% mark, oil prices have rallied back above $100 a barrel in recent weeks, and 10-year Treasury yields have crossed the 5% benchmark. “Many of those lines have been crossed, yet the exit strategy is less clear, not more,” JP Morgan’s commodities research team wrote in the note. “For the first time since the start of the Iran conflict, we don’t have a baseline view. We simply don’t know how to model the endgame.”

    The admission from one of the most influential institutions in global finance lays bare just how difficult it has become to anticipate policy moves from former President Donald Trump amid the escalating regional crisis. An anonymous oil and gas industry source speaking to the BBC noted that it is highly unusual for such a high-profile investment firm to issue such a transparent note acknowledging a total lack of forecasting clarity, but added that the move is an honest reflection of the current high-uncertainty environment surrounding the conflict. Oil prices are a core input for inflation forecasting globally, as the commodity underpins nearly every sector of the modern economy, meaning even small shifts can reshape investment decisions across all asset classes. Currently, “The market is on edge,” JP Morgan analysts noted.

    Adding to the fog of uncertainty, Trump himself confirmed last week that he does not expect the US-Iran war to conclude before November’s U.S. midterm elections. “Right after the election, oil prices are going to be tumbling downward,” Trump told reporters. “I think it’s going to take a little bit longer than the midterm.”

    Sustained high oil prices have already driven sharp increases in the cost of living across the United States and the globe, with energy and fuel costs rising rapidly ahead of the Northern Hemisphere winter heating season. This week, the U.S. Federal Reserve, the country’s central bank, implemented its first interest rate hike in more than three years, and signaled that further increases could continue through 2027 in an effort to cool persistent inflation. Fed Chair Kevin Warsh justified the move by noting that “inflation is too high and has been for too long,” a position Trump has publicly rejected.

    Even with current trading prices above $100 per barrel, JP Morgan analysts estimate that the “fair value” of Brent crude for September sits around $90 a barrel. The gap between fair value and current market pricing, they explained, reflects the extra risk premium traders are adding to account for the growing threat of broader trade disruption across key Middle Eastern chokepoints.

    Beyond the Strait of Hormuz, the note identifies new supply risks emerging at another critical global shipping route: the Bab al-Mandeb Strait, where Iran-backed Yemeni Houthi forces have seized territory at the mouth of the waterway. The ongoing conflict between Russia and Ukraine continues to add additional upward pressure on global oil markets as well. With no clear signals of imminent de-escalation in either conflict, analysts noted that the long-held assumption that global oil supply disruptions would prove temporary is “becoming increasingly difficult to sustain.”