分类: business

  • RBA boss warns mortgage holders that rate rises will be used again

    RBA boss warns mortgage holders that rate rises will be used again

    Australian households holding mortgages are facing a stark new warning from the Reserve Bank of Australia (RBA): the central bank stands ready to resume interest rate hikes if persistent high inflation and emerging upside risks do not ease in the coming months.

    Delivering remarks at the Queensland Futures Institute Annual Regions Summit in Brisbane, RBA Deputy Governor Andrew Hauser laid out the central bank’s position just one week after policymakers voted to hold the official cash rate steady at its August meeting. While the board opted to pause hikes for a second consecutive gathering, Hauser emphasized that the status quo is far from permanent, as inflation remains well above the RBA’s mandated target range.

    “While we concluded last week that interest rates are okay where they are for now, we are worried about the inflationary outlook and we are worried about the upside risk to inflation,” Hauser told attendees.

    Hauser outlined three key threats that could push inflation higher than current projections, derailing the central bank’s progress toward price stability. The first is the ongoing crisis in the Middle East, which carries significant risk of escalation that could drive global energy and supply chain costs upward. Second, the rapid, unexpected boom currently unfolding across the global technology sector threatens to import fresh inflationary pressure from international markets. Third, domestic constraints, including sluggish supply and weak productivity growth, remain a persistent concern for policymakers.

    “If those upside risks to inflation crystallise and we don’t see inflation coming down, we will have to raise interest rates again and we will do so,” Hauser said.

    The RBA’s August pause matched broad market expectations, following an aggressive tightening cycle so far in 2026. Across three of the five scheduled monetary policy meetings this year, the central bank has lifted the cash rate by a cumulative 75 basis points, pushing the benchmark from 3.60 percent to its current level of 4.35 percent. Since those three hikes, the RBA has opted to hold rates steady at back-to-back meetings to assess the cumulative impact of previous tightening on the economy.

    Current inflation data underscores the challenge facing the RBA. The central bank’s preferred trimmed mean inflation measure, which excludes the most volatile 15 percent of price movements in both directions, came in at 3.60 percent for the 12-month period ending in June. That reading remains noticeably above the RBA’s statutory target range of 2 to 3 percent.

    Hauser reiterated the central bank’s dual mandate: returning inflation to the 2-3 percent target while sustaining full employment for Australian workers. He emphasized that stubbornly high inflation remains the most pressing threat to household and economic stability, noting that cost-of-living pressures are being felt across the country, even if some inflationary pressure originates outside Australia’s borders.

    “Our message is simple, inflation is too high,” he said. “Everywhere you look people say prices are too high, cost pressures are too strong and while some of that is not home grown … but some of it does come from Australia.”

    The deputy governor also acknowledged that bringing inflation back to target will require a period of below-trend economic growth, pushing back against expectations that the RBA can achieve price stability without any cooling in domestic activity. He explained that monetary policy works by tempering excess demand and capacity pressure in the economy, a process that inevitably translates to slower consumption and employment growth than Australia has seen in recent years.

    “Monetary policy needs to bring inflation down, that is why we have raised rates three times this year, but here is the bad bit, it can only do so by reducing pressure on capacity and demand on the economy,” he said. “That means slightly slower growth in consumption, slightly slower growth in employment. We’ve seen a little bit of that so far, but we are going to need to see more to get inflation back.”

    Hauser was quick to clarify that the projected slowdown is not a forecast for a deep recession or depression, stressing that the central bank expects only a moderate cooling of activity as inflation adjusts back to target. “That is not a slump, that is not a depression … but it is slower than growth in the past,” he added.
  • World shares mostly decline, hit by heavy selling of AI-related shares

    World shares mostly decline, hit by heavy selling of AI-related shares

    Global equity markets faced broad downward pressure on Wednesday, driven by a widespread selloff in artificial intelligence-linked stocks across Europe and Asia, as investors grew jittery over stretched valuations in the AI sector and layered macroeconomic risks.

    In European trading, losses were mixed but largely negative: Germany’s benchmark DAX index dipped 0.2% to close at 26,085.69, London’s FTSE 100 shed 0.2% to end at 10,707.36, while Paris’s CAC 40 bucked the regional trend with a 0.3% gain to 8,532.16. Futures contracts tracking Wall Street’s S&P 500 and Dow Jones Industrial Average held near flat, pointing to limited opening movement after U.S. markets closed lower a day earlier.

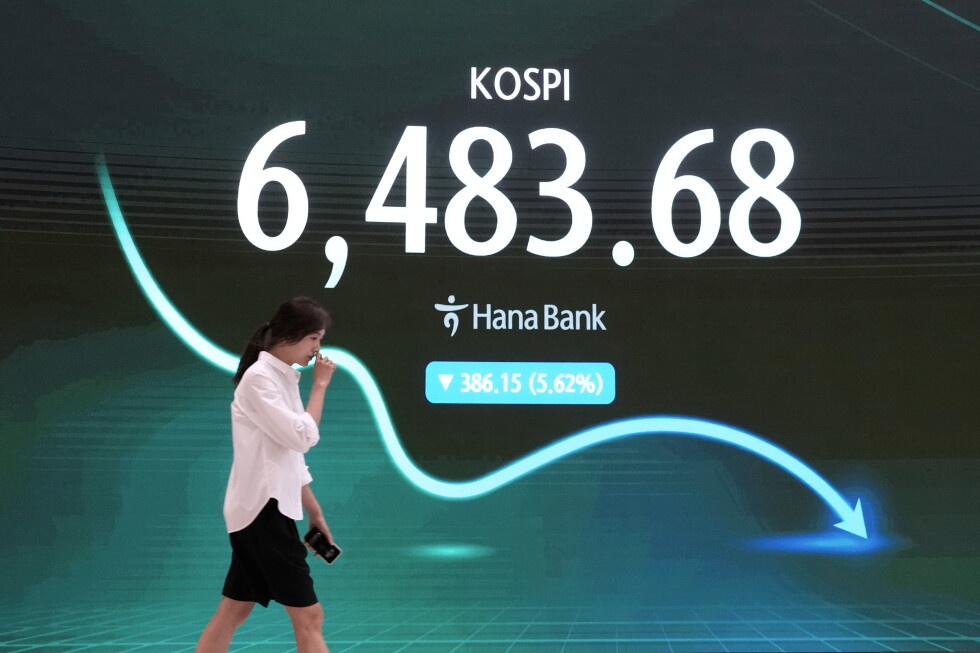
    Asian markets bore the brunt of the selling, with South Korea’s Kospi leading regional declines with a sharp 5.8% drop to 6,471.17. The two South Korean corporate giants that have reaped the biggest benefits from the AI boom followed steep losses from their U.S. tech and chipmaking peers: Samsung Electronics fell 7.8%, and leading memory chip manufacturer SK Hynix plummeted nearly 10% to end the session down 9.8%. Japan’s Nikkei 225 also tumbled 3.2% to 65,326.42, pulled lower by dual pressures of AI stock selling and growing market anxiety over rising government bond yields. The 10-year Japanese government bond yield has hovered near a 30-year high above 2.9%, as investors price in expectations that the Bank of Japan will soon lift its benchmark interest rate to tame persistent inflation.

    Mainland China’s Shanghai Composite Index fell 2.4% to 3,894.42, though the session brought one standout outlier: domestic humanoid robot manufacturer Unitree notched a historic trading debut on the Shanghai Stock Exchange’s STAR Market, the country’s tech-focused board modeled on the Nasdaq. The firm’s shares initially surged nearly 630% in early trading after raising roughly $900 million through its initial public offering, and closed the session still up a staggering 460%. By contrast, UBTech, another major Chinese humanoid robot maker listed in Hong Kong, dropped 10.7% on the day. Hong Kong’s Hang Seng Index posted a modest 0.1% gain to 25,495.07, while Taiwan’s Taiex fell 1.3% and Australia’s S&P/ASX 200 slipped 0.2% to 9,053.80.

    Multiple headwinds have combined to sour near-term market sentiment. First, investors have begun reassessing the sky-high valuations of AI-linked stocks, which have run up sharply over the past year amid the global AI boom. Market participants have grown increasingly concerned that projected demand for memory chips, processors and other core data center components could soften if the AI sector fails to deliver the outsized profits investors have already priced in. On Tuesday, that unease filtered through to Wall Street, pulling major indices further from their recent all-time highs: the S&P 500 lost 0.7% for its third consecutive modest loss, the Dow Jones Industrial Average dipped 0.2%, and the Nasdaq Composite sank 1.3%. Leading the U.S. selloff were the same big AI winners that have driven market gains for months: memory chip maker Micron Technology dropped 7% in the prior session, making it one of the heaviest drags on the S&P 500, while Nvidia fell 2.3% and Broadcom sank 3.2%.

    A second key pressure comes from volatile and rising oil prices, which have added to global inflationary worries. Crude markets have swung sharply amid ongoing geopolitical uncertainty over whether the U.S. and Iran will reach an agreement to reopen the Persian Gulf for unobstructed oil tanker traffic. On Wednesday, international benchmark Brent crude added 0.8% to $91.78 per barrel, up sharply from $72.87 per barrel shortly before the latest Middle Eastern conflict began. U.S. benchmark West Texas Intermediate crude gained 1% to $84.86 per barrel.

    Rising inflation expectations have in turn pushed government bond yields sharply higher, creating a third major headwind for equities. The 10-year U.S. Treasury yield edged down slightly to 4.70% on Wednesday from 4.72% late Monday, but it remains far above the 3.97% level recorded just before the outbreak of new hostilities in the Middle East. The 30-year U.S. Treasury yield also ticked slightly lower but still hovers near its highest level since 2007. High bond yields make investors less willing to pay premium prices for risk assets like stocks, particularly the richly valued tech and AI shares that have led market gains in recent years. They have also pushed the average long-term U.S. mortgage rate near its highest level in a year, crippling demand in the housing sector, and could slow Big Tech companies’ ability to borrow to fund new data center construction – a major engine of current U.S. economic growth.

    In currency markets, the U.S. dollar weakened slightly against the Japanese yen, falling to 159.11 yen from 159.61 yen in prior trading. The euro ticked higher against the dollar, rising to $1.1607 from $1.1577.

    Associated Press Business Writer Chan Ho-him in Hong Kong contributed reporting to this article.

  • No $100m, $50m draws cut $350m from Lotto Corp revenue

    No $100m, $50m draws cut $350m from Lotto Corp revenue

    An unprecedented statistical anomaly, a outcome not seen in nearly half a century, has delivered a significant financial hit to Australia’s The Lottery Corporation, eroding millions in top-line revenue and driving a more than one-fifth drop in annual after-tax profits.

    The firm released its full-year financial results on Wednesday, revealing that the past 12 months marked the first time in five years that no $100 million Powerball jackpot was awarded, and the first stretch of nine years without a $50 million Powerball draw. This unusual gap in mega-jackpot draws drained $350 million from the company’s annual revenue, executives confirmed.

    Wayne Pickup, chief executive officer of The Lottery Corporation, described the absence of these high-value jackpots as a one-in-45-year statistical event. Despite the sharp hit to the bottom line, Pickup emphasized that the company’s core operations delivered solid performance across metrics the business can directly control.

    “Where we control the levers, we performed well, with healthy retention of price increases in our two largest games – Powerball and Saturday lotto – and continued growth in base games and Keno,” Pickup said in a statement accompanying the results. The CEO added that the company’s approach to cost control is a permanent structural adjustment, not a temporary one-off fix, freeing up capital to reinvest in key growth areas including digital infrastructure, artificial intelligence integration, new product development, and customer experience capabilities.

    Large jackpot draws are inherently variable in outcome, Pickup explained, noting that these fluctuations typically even out over longer time periods. For the full fiscal year, total revenue for The Lottery Corporation dipped 2.7% year-over-year to $3.58 billion, while after-tax profits fell 22.1% to $284.6 million.

    The financial damage from the lack of mega-jackpots was partially offset by a November price increase for Powerball tickets, which boosted margins and revenue. Long-term prospects for the business also received a boost earlier this year, when the company secured a 40-year extension of its lottery license with the state of Victoria, locking in operating rights for decades to come.

    For shareholders, the company maintained its dividend payout, approving a total fully franked ordinary dividend of 16 cents per share – matching the same payout level distributed in the prior financial year.

  • American Airlines to bring back TV screens on US flights

    American Airlines to bring back TV screens on US flights

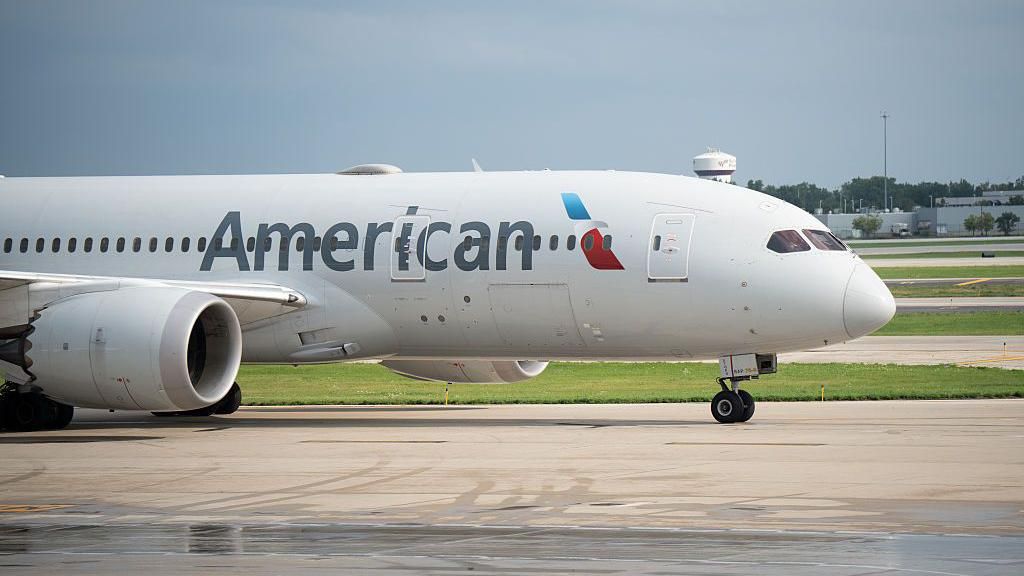
    Almost seven years after removing seatback televisions from all its U.S. domestic flights, American Airlines has announced a major course correction: the carrier will restore built-in seatback displays across its entire domestic fleet, alongside an expansion of premium seating offerings.

    The shift marks a full reversal of a cost-cutting efficiency strategy the airline rolled out throughout the 2010s. At the time, American Airlines argued that most travelers preferred to stream personal entertainment via their own smartphones, tablets, or laptops. Removing the heavy built-in screens also cut aircraft fuel consumption and reduced long-term maintenance costs, priorities for carriers chasing operational efficiency in a tight-margin industry.

    But the decision quickly sparked widespread passenger frustration that persisted for years. Frequent flyers repeatedly complained that relying on personal devices created a host of avoidable problems: drained batteries mid-flight, awkward cramped viewing angles, and inconsistent in-flight Wi-Fi that interrupted streaming content. The strategy also left American Airlines out of step with key competitors, who have taken the opposite approach in recent years. Rival Delta and United have poured investment into upgraded onboard entertainment to elevate their premium cabin experiences, while low-cost carrier JetBlue has retained seatback screens as a standard customer perk all along. Industry analysts note these competing choices have reshaped passenger expectations, repositioning seatback displays from an unnecessary luxury to a baseline expected amenity on most U.S. commercial flights.

    The restoration forms part of a broader cabin modernization investment American Airlines unveiled this week. The airline says the upgrades are designed to improve the overall customer travel experience while also driving higher revenue, a goal that comes as major U.S. carriers work to stabilize passenger demand in a cooling post-pandemic travel market.

    Advancements in display technology have also made the reversal feasible for the airline. Modern seatback screens are far lighter, use less power, and have lower upfront installation and maintenance costs than the models American Airlines removed years ago, making the investment far more justifiable for carriers today. American Airlines plans to begin rolling out the new displays immediately, with full installation across its domestic Boeing 737 and Airbus A320-family jets expected to be completed by the early 2030s.

    Raymond James industry analyst Savanthi Syth told the BBC that strategic positioning plays a key role in how quickly airlines roll out new customer amenities. Syth noted that Delta, which was the first major U.S. carrier to introduce a basic economy fare, has continued to roll out new customer offerings steadily, putting it further along in its commercial product development than many peers. For American Airlines, the decision to restore seatback screens reflects a push to stay competitive in an increasingly crowded market, betting that improved and more reliable onboard amenities will help the carrier win over both leisure and business travelers, while retaining appeal for budget-conscious passengers who still expect core in-flight comforts.

  • Australian sharemarket falls for fifth day despite surging healthcare stocks, record BHP profit

    Australian sharemarket falls for fifth day despite surging healthcare stocks, record BHP profit

    Australia’s benchmark share index has extended its downward run to five consecutive trading sessions, defying strong gains across the healthcare sector and a bumper full-year result from global mining giant BHP that failed to reverse broader market momentum on Tuesday. The flagship S&P/ASX 200 edged down 3.20 points, a marginal 0.04% drop, to close at 9070.00, while the broader All Ordinaries index fell 4.80 points, or 0.05%, to settle at 9274.20. The Australian dollar traded at roughly 70.97 U.S. cents by market close. The trading day delivered a deeply mixed session for Australia’s 11 market sectors, with five closing in positive territory and six finishing lower. Leading all gainers by a wide margin, the healthcare sector surged 7.81% overall, while the energy sector posted a more modest 0.99% rise. The materials sector also recorded mild growth, driven entirely by strong investor demand for BHP shares following the miner’s latest earnings release. BHP closed 2.65% higher at $63.85 per share, though other major local mining players failed to share in the upward momentum: Rio Tinto slipped 0.55% to $167.40, while Fortescue Metals Group fell 0.39% to $17.68. Even with BHP’s share gain, copper prices closed 0.55% lower at $6.57 per pound. Biotech and blood products giant CSL, the heaviest-weighted stock in the healthcare sector, led the sector’s explosive rally despite posting a significant annual net loss. CSL shares jumped 17.25% to close at $157.82, recovering a large portion of the losses the stock has recorded over the past 12 months. Cochlear, the leading implant manufacturer, saw its shares rally 7.58% to $141.20 after releasing an upbeat earnings update, while medical imaging tech firm Pro Medicus gained 11.88% to $196.75 following an annual report that showed a 24.1% rise in underlying profit to $144.7 million. Jamie Hannah, deputy head of investments and capital markets at VanEck, noted that the sharp rally in CSL shares was surprising given the company’s weak bottom-line results in the annual report. “CSL was slightly ahead of analyst expectations, but the market really latched onto the company’s guidance for strong growth next year, and that pushed shares up by a huge amount, nearly erasing the entire drop the stock has seen over the past year,” Hannah explained. “It’s quite incredible. I think you have to question whether the size of the market movement actually reflects the underlying earnings results we’ve seen this earnings season. Right now, companies are under enormous pressure to deliver strong results; if they don’t, investors punish them quite heavily on the market.” Hannah added that the small gain in the energy sector could be traced directly to a recent rally in global crude oil prices, which hit $91 U.S. per barrel ahead of Tuesday’s market close. “That always gives a boost to energy stocks broadly,” he said, “paired with BHP’s stronger-than-expected result, that was enough to keep the sector in positive territory.” The heavyweight financial sector was one of the biggest drags on the benchmark index, with Australia’s so-called Big Four banks all closing in negative territory. Commonwealth Bank of Australia fell 1.44%, ANZ dropped 0.53%, and Westpac declined 1.17%, while National Australia Bank also posted a small single-digit loss. In other individual company news, A2 Milk Company recovered 8.58% on Tuesday after falling 3.26% in the previous session following its own earnings release. Infrastructure firm Reliance Worldwide saw its shares soar 24.65% to $4.50 per share after Canadian global investment giant Brookfield announced a $4.1 billion takeover bid for the company.

  • Gold Coast-based eyewear brand worn by celebrities collapses into liquidation, brand facing $600k fire sale

    Gold Coast-based eyewear brand worn by celebrities collapses into liquidation, brand facing $600k fire sale

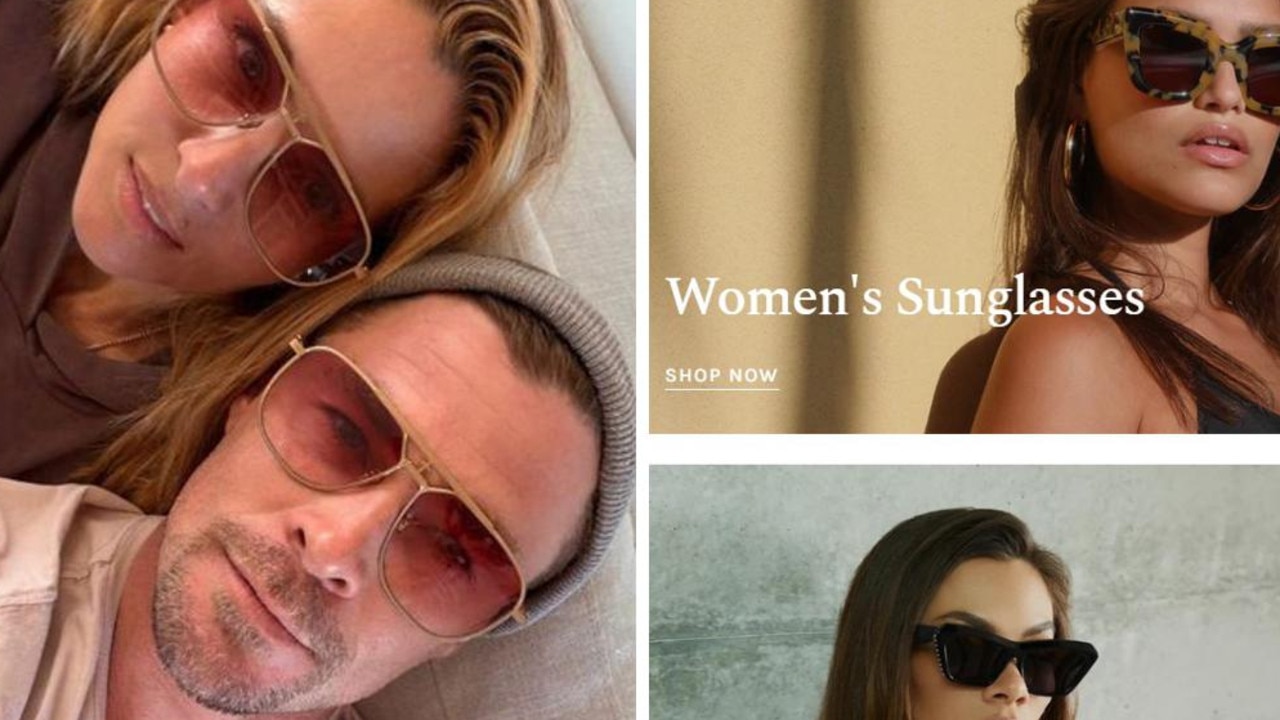
    Valley Eyewear, the Australian-founded sunglasses brand that counted A-list celebrities including Chris Hemsworth, Margot Robbie, and Kanye West among its high-profile wearers, has been placed into liquidation following a Federal Court order, launching an urgent fire sale of more than AU$600,000 in inventory and business assets.

    Established in 2011 on Australia’s Gold Coast by ex-Quiksilver marketing executive Michael Crawley, his wife Tenielle Crawley, and their long-time friend Matthew Grippo, the brand grew from a local startup to a globally recognized label, with distribution across more than 20 countries. It built a reputation for edgy, stylish designs that resonated with both consumers and famous figures, cementing its status as a popular accessories label both at home in Australia and abroad.

    But behind its public growth, tensions between the three co-founders escalated into a public court battle, ultimately leading to the court order for urgent liquidation and sale of the company. The liquidation order also extends to House of Valley, a sister entity registered earlier this year to open a new brick-and-mortar retail store and on-site optometry clinic in Burleigh Heads, which has now collapsed alongside the original brand.

    Federal Court appointed James Robba and Jason Bettles from insolvency firm Worrells to oversee the liquidation process. The full asset package up for sale includes not only the brand’s large inventory of new sunglasses and optical equipment, but also motor vehicles owned by the business, general plant and equipment, all intellectual property rights, existing customer databases, and the brand’s established digital and social media presence.

    Robba confirmed that the business will continue normal day-to-day operations while the urgent sale campaign progresses, noting that the insolvency team is working closely with company directors, employees, and other key stakeholders to facilitate a smooth process. “Our objective is to give interested parties the opportunity to acquire the business of the companies, while seeking to maximise the outcome for all stakeholders,” Robba told local outlet The Courier Mail.

    In a surprising development just two days before the liquidation order was issued, Tenielle Crawley registered a new entity named Valley Eyewear Group, with herself and Robert Fullagar listed as co-directors. On the same day, the Crawleys launched a second new firm, Crawley Family Holdings, which now holds a majority stake in the newly registered Valley Eyewear Group. Details on the future plans for the new entity have not been released to the public.

    While the full internal circumstances leading to the brand’s collapse have not been made public, this is not the first time the company has faced significant controversy. In 2018, Valley Eyewear drew widespread global backlash after it used the Spomenik Holocaust memorial in Croatia, a site honoring 70,000 people executed during World War II, as a backdrop for an advertising campaign for its “Black Zero” sunglasses collection. The brand quickly issued a public apology, removed all campaign content, and claimed it had been completely unaware of the historical sensitivity of the location at the time of shooting.

  • Bendigo Bank hit with new conditions over ‘longstanding’ management weaknesses

    Bendigo Bank hit with new conditions over ‘longstanding’ management weaknesses

    Australia’s top banking regulator has taken stiff enforcement action against one of the country’s major regional lenders, forcing it to commit an additional $70 million to fix widespread, long-standing failures in anti-money laundering (AML) and counter-terrorism financing (CTF) controls that slipped through years of internal remediation work.

    The Australian Prudential Regulation Authority (APRA) announced the new binding licence conditions for Bendigo and Adelaide Bank on Tuesday, capping off a 12-month industry probe that was triggered after the bank itself commissioned global consulting firm Deloitte to investigate suspicious activity at a single branch in late 2025. What investigators initially expected to be an isolated issue quickly expanded into a company-wide audit that uncovered systemic gaps in how the bank manages financial crime risk, spanning every core layer of its AML/CTF framework.

    Deloitte’s final root-cause analysis confirmed widespread failures across multiple critical functions: the bank’s approach to AML/CTF risk mapping, enhanced customer due diligence protocols, enterprise-wide risk oversight, automated transaction monitoring systems, and customer risk rating processes all fell short of regulatory requirements. The review also confirmed that the gaps left the bank vulnerable to potential compliance breaches between August 1, 2019 and August 1, 2025.

    APRA’s formal order lays out four distinct categories of material weaknesses that prompted the new regulatory action. First, deficiencies in non-financial risk management are embedded across the entire organization, not limited to a single division or branch. Second, the bank lacks a clear, comprehensive and accurate understanding of its own regulatory obligations, material risk exposures, and key internal controls. Third, there are significant gaps in governance structures, accountability frameworks, compliance management systems, and overall risk management capacity across the bank. Finally, these core weaknesses have persisted for years, even as the bank carried out a multi-year enterprise-wide risk transformation initiative known as BEN+.

    To address these failures, Bendigo and Adelaide Bank will invest $70 million over the next three years to overhaul its risk management systems, with the full cost already allocated to the bank’s 2026 financial year results. APRA is also retaining an existing $50 million financial penalty that it imposed on the bank in a previous enforcement action related to the same issues, bringing the total cost of the failures to $120 million for the lender.

    Therese McCarthy Hockey, APRA’s Deputy Chair, emphasized in a statement that the new licence conditions reflect the severity of the unaddressed risk gaps uncovered by the probe. “The weaknesses identified by the root cause analysis are significant, longstanding and require decisive action,” she said. McCarthy Hockey added that the regulator acknowledges the cooperative approach the bank has taken so far, and that APRA is encouraged by the board’s public commitment to resolving all identified concerns fully, promptly and effectively. She also confirmed that despite the risk management failures, the bank remains financially sound with no threat to its current operations or customer deposits.

    Richard Fennell, Bendigo and Adelaide Bank’s Chief Executive, acknowledged the severity of the gaps in an official response on Tuesday. “Our current non-financial risk management capabilities are clearly not where they need to be, and our risk rectification plan will be designed to drive a fundamental shift in our management of non-financial risk,” Fennell said. He added that the three-year remediation plan will deliver wholesale improvements to the bank’s risk governance and compliance infrastructure to bring the bank back into full alignment with Australian regulatory requirements.

  • Sinking AI stocks pull Wall Street further from its record

    Sinking AI stocks pull Wall Street further from its record

    A broad downturn gripped Wall Street on Tuesday, extending a three-day losing streak for the S&P 500 as high-flying artificial intelligence stocks reversed recent gains and pulled the benchmark index further from its all-time high set just last Thursday. As of 10:15 a.m. Eastern Time, the S&P 500 had dipped 0.5% from its previous close, while the Dow Jones Industrial Average edged down a modest 33 points, or 0.1%. The Nasdaq composite, which is heavily weighted toward technology and AI-linked stocks, posted a steeper 1.3% decline.

    The sharpest losses were concentrated among the stocks that have led this year’s AI-driven market boom, which have swung wildly through the summer months. Investors have grown increasingly jittery that valuations for these assets have outpaced actual fundamentals, fueled by an unrelenting hype around generative AI. Key concerns center on whether projected demand for data center components — from memory chips to advanced processors — will soften if AI fails to deliver the outsized profit growth that market enthusiasm has priced in.

    Micron Technology, a leading supplier of memory chips for AI infrastructure, tumbled 5.9%, marking one of the biggest individual drags on the S&P 500. Other major chipmakers followed the downward trend: Nvidia dropped 2.5%, and Broadcom fell 3.7%. Even with the recent pullback, all three stocks remain massive winners for 2024, with Micron alone more than tripling in value since January. That lofty valuation has drawn greater investor scrutiny at a time of sustained high interest rates, a trend that has held steady across global bond markets this week.

    The yield on the 10-year U.S. Treasury inched slightly lower to 4.71% on Tuesday, down from 4.72% at Monday’s close, but it remains far above the 3.97% level recorded just before the outbreak of the Iran conflict. The 30-year Treasury yield also ticked down but stays near its highest point since 2007. Yields have surged since the war began, as soaring oil prices have added upward pressure to inflation, forcing the Federal Reserve and other major central banks to keep interest rates higher for longer. Persistent concerns over large government debt loads and increased borrowing volumes have also kept yields elevated.

    While often overlooked by casual investors, the bond market wields enormous influence over global financial markets and even political leadership. When bond yields climb, investors become far less willing to pay premium prices for riskier assets, particularly the richly valued growth stocks that have led the AI rally. Oil prices, a key driver of recent yield movement, saw minor upticks on Tuesday: a barrel of Brent crude rose 0.1% to $91.00, up from $72.87 just before the Iran war began. Prices have swung wildly in recent weeks as markets wait for clarity on a potential agreement between the U.S. and Iran that would reopen the Persian Gulf to unobstructed oil tanker traffic.

    Sustained high yields have already pushed the average long-term U.S. mortgage rate near its highest level in a year, creating major headwinds for the U.S. housing sector. New data released on Tuesday showed housing starts slowed more than economists had projected last month, a sign that high borrowing costs are cooling residential construction activity.

    Even home improvement retail giant Home Depot, which reported better-than-expected quarterly profit and revenue that beat analyst forecasts, saw its gains held back by ongoing housing market weakness. CFO Richard McPhail noted that customers continued to prioritize smaller home improvement projects, rather than the larger, higher-margin renovations that drove sales during the pandemic housing boom. Beyond housing, high interest rates also threaten to curtail the massive borrowing that big tech firms have relied on to build out new AI data centers, a key driver of recent U.S. economic growth.

    Elsewhere on Wall Street, buy-now-pay-later fintech firm Klarna dropped 20.5% despite posting quarterly results that outperformed analyst expectations. The steep sell-off came after Klarna cut its 2026 full-year financial forecasts, citing weaker expected performance in Germany, its largest market by transaction volume. Meta Platforms also slid 3.8%, as opening statements got underway in a high-stakes antitrust trial in California federal court. A coalition of U.S. states is seeking billions of dollars in damages from Meta, alleging the company knowingly caused harm to children and teens through its social media platforms.

    International stock markets were mixed on Tuesday. South Korea’s Kospi index, which has seen extreme AI-driven volatility in recent weeks due to its heavy exposure to chip manufacturing giants Samsung Electronics and SK Hynix, fell 1.5% — a relatively modest move for the index, which had swung by at least 2.4% in each of the previous three trading sessions. European indexes also posted mixed results, with some benchmark indices posting minor gains while others dipped into negative territory.

  • Australian households ‘deeply pessimistic’ despite confidence boost from RBA rate hold

    Australian households ‘deeply pessimistic’ despite confidence boost from RBA rate hold

    Australia’s household economic sentiment has posted a minor uptick following the Reserve Bank of Australia’s (RBA) decision to hold official interest rates steady, yet broad-based pessimism about personal financial circumstances and the nation’s long-term economic trajectory remains deeply entrenched among Australian consumers.

    The latest monthly Westpac-Melbourne Institute Consumer Sentiment Index, one of the country’s most closely watched measures of household economic mood, recorded a 6% gain in August to reach 88.9. While this rise marks the first improvement in sentiment in months, the reading still sits well below the 100 threshold that divides prevailing pessimism from optimism, confirming that negative outlooks continue to dominate public opinion.

    Westpac’s chief economist Luci Ellis noted that cost-of-living pressures continue to squeeze household budgets across the country, even after the small improvement in mood. “This is still a weak result and noticeably lower than the readings recorded last year,” Ellis explained. “While consumers are feeling less pessimistic than last month, pessimists still outnumber optimists, especially about their current finances.”

    Survey data shows the shift in sentiment happened almost immediately after the RBA’s monetary policy board announced it would keep the official cash rate unchanged at 4.35% on August 6. Responses collected before the announcement showed no change from July’s weak reading, with the entire monthly gain coming from surveys completed after the decision was made public.

    The RBA’s announcement came with a hawkish undertone, however: Governor Michele Bullock confirmed that board members had discussed a potential rate hike during the meeting – a step the board did not take during its May 2024 gathering. Bullock also warned that additional rate increases remain on the table as the central bank works to prevent currently elevated inflation, which sits at 3.8%, from becoming permanently embedded in the Australian economy.

    Markets and economists broadly expect the RBA will hold rates steady again when the board next convenes for its September 28-29 policy meeting. A softer-than-expected labour market and only one new monthly inflation reading due before the gathering have reinforced expectations that policymakers will leave policy unchanged for another month. Ellis noted that the RBA already has lifted rates three times in 2024 to bring the cash rate to a restrictive level, giving policymakers room to pause and assess how previous tightening has impacted economic activity across the country.

    “Having already raised the cash rate three times this year to a restrictive level, the monetary policy board has scope to keep the cash rate on hold while it monitors the effect of policy tightening across the economy and confirms whether underlying inflation has peaked,” Ellis said.

    Most of the confidence gains were concentrated in assessments of current economic conditions, with attitudes toward long-term economic prospects remaining firmly negative. The report also revealed uneven sentiment shifts across demographic groups: sentiment among renters rose in the days after the RBA meeting, but weak readings from before the announcement left overall renter sentiment slightly lower for the month as a whole.

    Two key sub-indexes posted notable improvements in August: the gauge of attitudes toward major household purchases rose 8.1% from 86.8 in July to 93.8 this month, while the index measuring year-over-year changes in household financial pressure improved 12.6% to 80.0. Even with these gains, however, both measures remain in pessimistic territory, underscoring that Australian households are still feeling significant economic strain.

  • US-Canada trade talks ‘intense’ as new tariff deadline looms

    US-Canada trade talks ‘intense’ as new tariff deadline looms

    With less than 48 hours remaining before a new wave of US tariffs targeting Canadian goods takes effect, high-stakes trade negotiations between Canadian and American negotiators are entering a final, frantic stretch in Washington. Canadian bargaining teams have been stationed in the US capital for a full week, racing to lock in a breakthrough agreement that can block the planned 50% tariffs on roughly $20 billion in Canadian imports scheduled to go into force this Wednesday.

    Facing relentless questions from reporters on Monday, Canadian Prime Minister Mark Carney refused to disclose any details of the closed-door discussions, noting that the currently “very delicate and intense” negotiations leave no room for public bargaining. While Carney emphasized that Canada enters the talks from a position of strength, the stakes could not be higher for his government: the new tariffs would cover approximately 5% of all Canadian imports, delivering a fresh blow to already strained cross-border commerce.

    In spite of a packed schedule of meetings between Canadian negotiators and US Trade Representative Jamieson Greer over recent days, the two sides have so far failed to reach a final consensus. Leaving Greer’s office on Monday, Canadian Minister of US-Canada Trade Dominic LeBlanc acknowledged plainly that “Our job is not yet done.” Both sides have openly acknowledged the difficult nature of the talks. Former US President Donald Trump, whose administration is driving the new tariff push, has publicly labeled Canada “nasty” on trade — a description Carney did not fully reject, and Trump has already warned he will escalate trade pressure if no deal is reached by the deadline.

    Even if negotiators do hammer out a last-minute agreement, Carney faces significant domestic headwinds to sell any compromises to a Canadian public already frustrated and deeply skeptical of US trade policy. He will also need formal approval from Canada’s provincial governments for any deal that touches on areas under provincial jurisdiction.

    The United States has tabled a list of key demands for Canada, including the full removal of Canada’s remaining retaliatory tariffs on American automobiles, adjustments to Canada’s dairy import quota system, and the elimination of provincial bans on US alcohol sales. Those bans were implemented by most Canadian provinces early last year in direct retaliation for Trump’s earlier steel and aluminum tariffs, and authority over alcohol policy rests entirely with provincial governments, meaning any change requires provincial buy-in.

    Ontario Premier Doug Ford, who has long positioned himself as a hardliner on US trade, confirmed last week that any agreement to roll back the alcohol ban would be conditional on the US delivering meaningful concessions for Canadian key sectors. “If we get a fair deal that will protect our steel sector, our auto sector, our forestry sector, our agriculture sector, our manufacturing sector, then we’d be happy to bring booze back on the shelves,” Ford said.

    Canada, for its part, is seeking a deal that would see the US eliminate or roll back existing tariffs on Canadian steel, aluminum, automobiles and lumber — duties that have already caused significant damage to Canada’s national economy. Carney also faces major domestic pushback on any dairy concessions, particularly in Quebec, where Premier Christine Fréchette has reaffirmed that Canada’s supply management system for dairy is non-negotiable. Trump has repeatedly attacked the system, which sets production quotas, fixed domestic pricing, and import limits for dairy, eggs and poultry, arguing it is unfair to American farmers seeking greater access to the Canadian market.

    Public opinion in Canada leans heavily against offering major concessions to the US, even as most Canadians acknowledge a desire for greater trade stability. A recent poll from Abacus Data found that 74% of Canadian respondents say the ongoing trade dispute has impacted their household finances. Thirty-six percent support Canada responding to new US tariffs with new counter-tariffs, even if that brings additional domestic economic pain, while just 18% back concessions such as lifting the provincial alcohol ban to secure tariff reductions.

    Canadian media reports have also indicated that Canada’s chief negotiator Janice Charette has formally warned US counterparts that enacting the new tariffs this Wednesday would put future broader trade negotiations at serious risk. Carney has repeatedly stated he will not sign any deal that is not clearly beneficial to Canada, though he has declined to outline specific parameters for what qualifies as a good deal. On Monday, he only noted that “We’ll have opportunities over the next 48 hours to discuss in more detail as the negotiations go forward,” confirming he plans to speak directly with Trump before the Wednesday deadline and that his government has “plans for any situation that may arise” if talks collapse.

    Opposition Conservative trade critic Shuvaloy Majumdar released a statement Monday calling for an end to ongoing economic uncertainty for Canadian households. “We have grown tired of seeing our country used as a punching bag,” he said, adding that “Yet we share a common hope that Prime Minister Carney will deliver a genuine win at the negotiating table.”