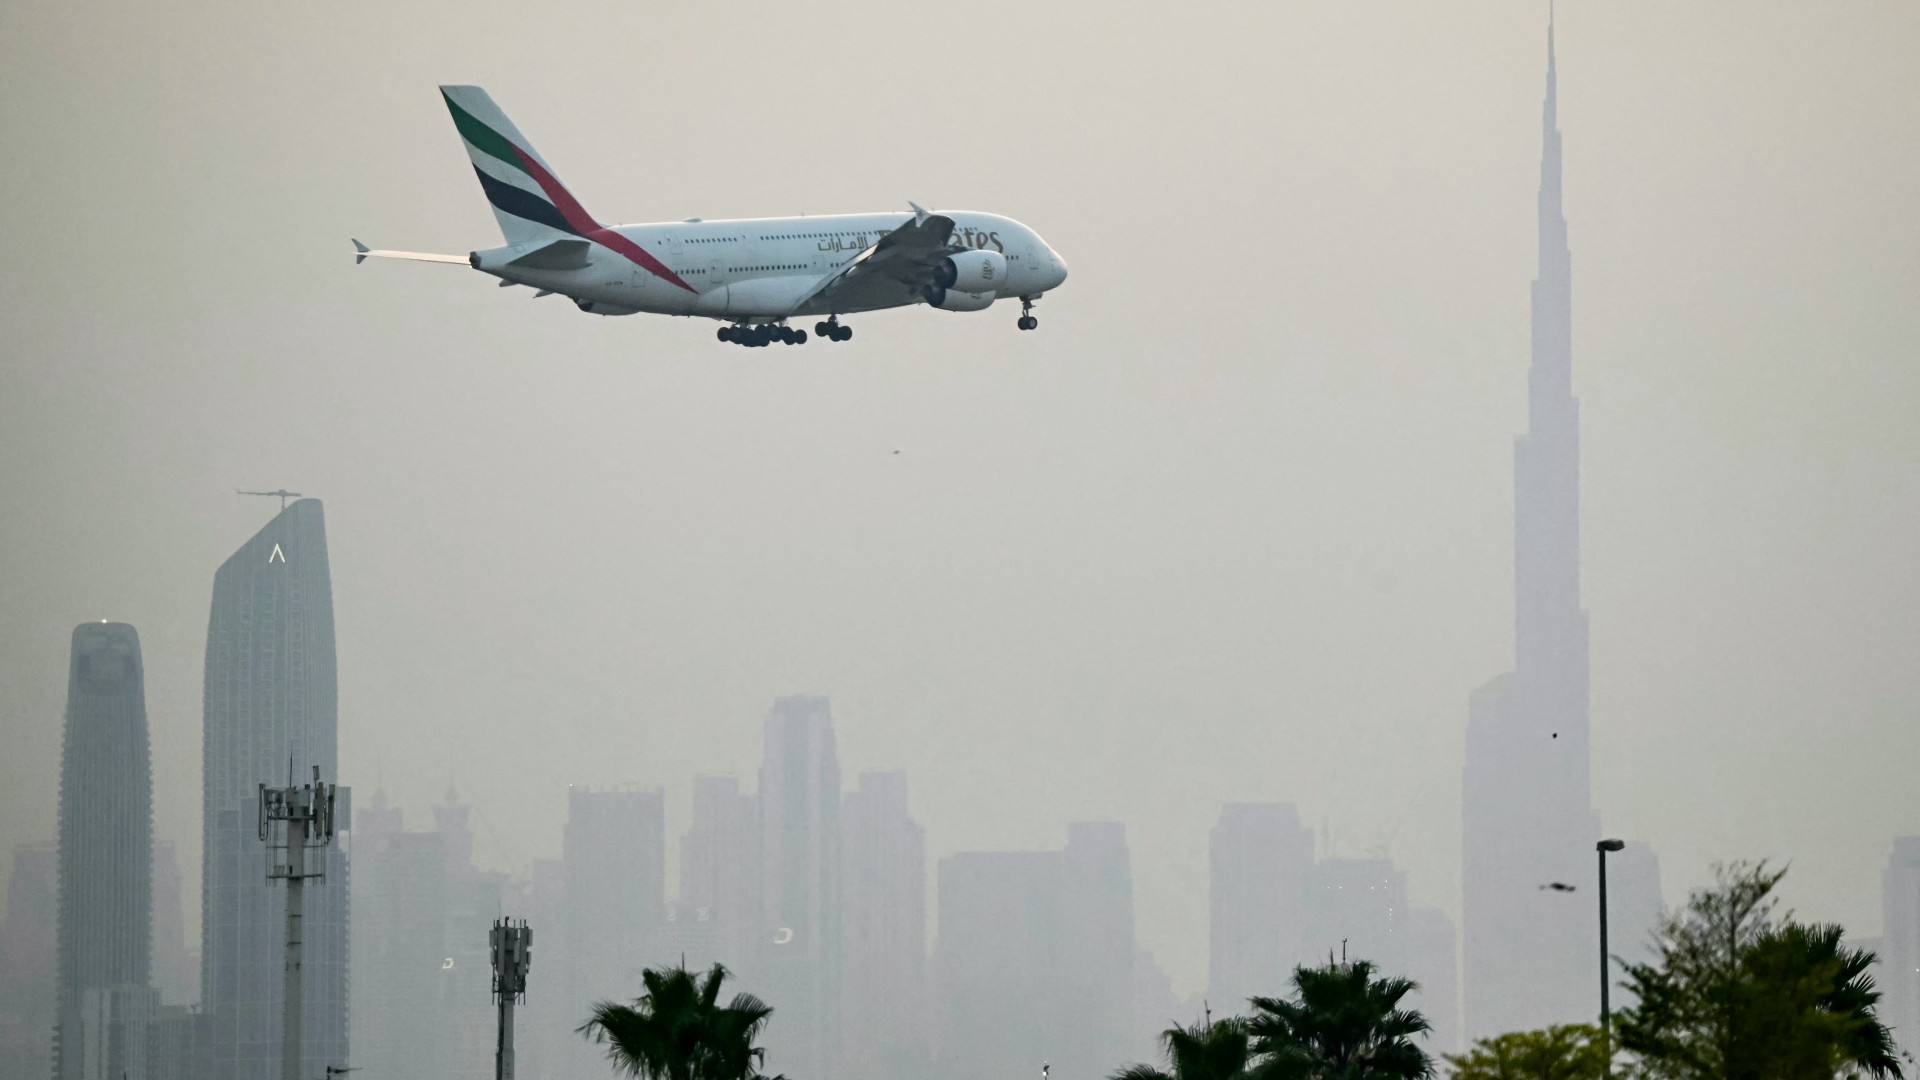
The February 28, 2026 escalation of military conflict between the US, Israel and Iran triggered a cascading crisis that has reshaped the global aviation industry, with the Gulf region at its epicenter. Following US-Israeli air strikes on Iranian territory, Iran launched retaliatory attacks targeting locations near US military installations across the Gulf, including sites in Qatar and the United Arab Emirates (UAE). Among the hit sites were key international airports: Dubai International, the world’s busiest hub for international passenger traffic, as well as airports serving Abu Dhabi, Kuwait City and Manama, Bahrain. In response to immediate safety risks, the UAE, Qatar, Bahrain and Kuwait moved quickly to close their entire airspaces to commercial traffic. While these airspaces were gradually reopened over the course of a week as hostilities de-escalated, the conflict left long-lasting damage to regional and global aviation that persists months later.
Industry data from the International Air Transport Association (IATA) illustrates the severity of the financial damage. In its June 2026 outlook, IATA projected that a projected $7.2 billion net profit for Middle Eastern-based airlines in 2026 would reverse to a $4.3 billion net loss, a stunning swing driven entirely by conflict-related disruption.
While major Gulf flagship carriers including Emirates, Etihad Airways and Qatar Airways have resumed commercial operations, none have returned to pre-conflict capacity. Emirates CEO Tim Clark confirmed in a June interview with the *Financial Times* that the airline is currently operating at only 75 percent of its pre-conflict flight schedule. In contrast, nearly all major European and Asian carriers have kept their flights to the region suspended, with staggered restart timelines stretching into late 2026 and early 2027. Air France plans to resume services in late August, Lufthansa in September, and British Airways, Cathay Pacific and Singapore Airlines have targeted late October for resumptions. Air Canada has gone further, announcing it will not restart regional services before mid-January 2027, and dozens of other global carriers have yet to announce any restart date at all.
Even after formal reopening, regional airspaces continue to face intermittent closures and unplanned disruptions. The European Union Aviation Safety Agency (EASA) latest public bulletin, published in August, continues to advise all commercial operators to avoid the airspace of Bahrain, Kuwait, Qatar, the UAE and portions of the Gulf of Oman through August 31, 2026. This ongoing caution has drastically limited travel options for passengers. For example, a one-week round-trip ticket between the UAE and London in September currently only has three available options: Emirates to Dubai, Etihad to Abu Dhabi, and Air Arabia to Sharjah. On matching dates between Doha and Tokyo, Qatar Airways is the only operating carrier available to book.
The conflict poses an existential threat to the core business model that has powered Gulf aviation’s rise over the past three decades: the hub-and-spoke system that leverages the region’s strategic geographic location between Europe and Asia to connect passengers between the two continents via a central Gulf hub. This model has long allowed Gulf carriers to offer connecting routes that are either unavailable via direct flights or cheaper than non-stop alternatives. But the conflict has exposed critical vulnerabilities in this system.
Naveed Kapadia, an aviation lecturer at Buckinghamshire New University, explained that while temporary reduced competition from suspended international carriers has allowed large Gulf airlines to capture incremental local market share and hold fares steady, their business model remains deeply vulnerable. “Gulf airlines are connecting carriers whose economics depend on moving large volumes of passengers efficiently through Dubai and Doha,” Kapadia told Middle East Eye. IATA data from June bears this out: regional passenger demand is down 13.9 percent year-over-year, while direct traffic between Europe and Asia has jumped 11 percent as carriers reroute to avoid Gulf airspace, creating immediate strain on Gulf hub operations.
This rerouting creates cascading cost increases across all operations. Flights that are forced to take longer, less efficient routes burn more jet fuel, require longer crew duty periods, and reduce overall aircraft utilization. The extra fuel carriers now carry as a buffer against unexpected airspace closures also directly cuts into the number of passengers or amount of cargo that can be carried on each flight. The hub-and-spoke model’s concentration of traffic through a single central hub also makes the entire network far more susceptible to cascading disruptions: a single grounded aircraft or stranded crew can trigger delays and cancellations across the entire global route network.
To rebuild passenger confidence and win back pre-conflict traffic, major Gulf carriers have rolled out unprecedented customer incentives. Emirates, the region’s largest carrier, introduced a new travel insurance policy that offers full coverage for flight cancellations related to conflict, a break from standard industry practice that typically excludes war-related disruption from coverage. If flights are canceled due to renewed hostilities, Emirates guarantees it will arrange repatriation for passengers on partner airlines if it cannot operate its own. “We would get you back irrespective [of whether it’s] on Emirates or not,” Clark told the *Financial Times*, framing the policy as a commitment to passenger safety. Beyond airline-specific incentives, Dubai’s tourism authority has launched broader campaigns to revive visitor numbers, offering complimentary travel packages for guests invited by Emirati citizens and free hotel stays for passengers on long connecting layovers.
The crisis has not been limited to passenger aviation: regional air cargo and private jet operations have also seen steep declines. Kapadia noted that regional air cargo demand grew only 5.6 percent year-over-year, roughly a third slower than the global industry average of 8.5 percent. IATA data shows traffic between Europe and the Middle East remains 41.1 percent below 2025 levels, while traffic between Asia and the Middle East is down 4.1 percent. While disruption to maritime shipping through the Strait of Hormuz has created new demand for air freight for urgent, high-value and time-sensitive shipments, Kapadia said this has not translated to a straightforward gain for Gulf cargo carriers, which collectively handle roughly 13 percent of global air cargo traffic. “The more important question is whether they can convert short-term urgency into sustained and profitable cargo flows,” he added.
Private jet activity originating in Gulf countries has also collapsed. Data from aviation analysts WINGX shows that as of August 10, total private jet traffic from Gulf nations was down 46.5 percent compared to pre-conflict levels. “The vast majority of flights stayed within the Middle East region, and volumes there are still down considerably,” said WINGX analyst Nick Koscinski. Gulf-to-Europe private flights, the second most popular route category, are down 40 percent year-over-year. Koscinski noted that Qatar Executive, one of the region’s largest private jet operators, has been more resilient than competitors based in the UAE or Saudi Arabia: its total traffic is only down 6.7 percent since the conflict began, compared to a 28.7 percent drop for a comparable UAE-based operator and a 39 percent drop for a leading Saudi operator. While private jet operators can often pass increased fuel costs through to customers via surcharges, Koscinski said lags in repricing and overall softer demand mean all regional private jet operators will still take a significant financial hit.
Jet fuel prices, a core input for all aviation operations, have remained far above pre-conflict levels despite temporary declines. Kapadia said prices fell 20 percent in June after Gulf oil flows temporarily stabilized, but remained 45.8 percent higher than June 2025. IATA forecasts that the 2026 average jet fuel price will be 70 percent higher than the 2025 average. Kapadia expects airfares in the region will remain elevated and volatile rather than rising uniformly: “Airlines will try to recover higher fuel and disruption costs through fares to some extent, but they cannot pass on every additional cost without weakening demand, particularly among price-sensitive leisure travellers.”
Low-cost carriers around the world have been hit hardest by the spike in fuel prices. US-based low-cost carrier Spirit Airlines ceased all operations on May 2, 2026, while European low-cost carriers Air Baltic and Wizz Air face growing bankruptcy risk and have been forced to restructure their operations to cut costs. A 2026 McKinsey report on aviation found that roughly 70 percent of jet fuel surcharges are passed directly to consumers, and airline margins only recover briefly when fuel prices fall. The report concluded that ongoing economic pressure will force the global industry to retire older, less fuel-efficient aircraft, cut low-demand routes, and further reduce overhead costs to remain solvent.
Not all regional carriers have suffered losses, however. Israel’s flag carrier El Al has reported record annual profits, more than double its previous yearly record. The gain comes as most international airlines have suspended service to Israel, leaving El Al as the near-exclusive option for international travel to and from the country, a position that has allowed the airline to raise fares sharply. Many passengers have publicly criticized the “outrageous” pricing that has come with the near-monopoly.
Industry consultants say the conflict will have long-term impacts on global aviation investment that will outlast the current hostilities. “Airport investment deals, geopolitical risk is increasingly being reflected in downside scenarios, valuation assumptions and risk premiums,” said Harsha Jaison, an aviation consultant at global advisory firm ICF. The changes to how the industry prices geopolitical risk, she added, are likely to become a permanent feature of aviation planning in the Middle East and globally.