分类: business

  • Big oil companies continue to post banner profits as fighting in Iran drives prices higher

    Big oil companies continue to post banner profits as fighting in Iran drives prices higher

    The ongoing military conflict in Iran has sent global energy markets into chaos, pushing oil and gasoline prices sharply upward — and delivering staggering windfall profits to the world’s largest oil companies, new corporate earnings reports show.

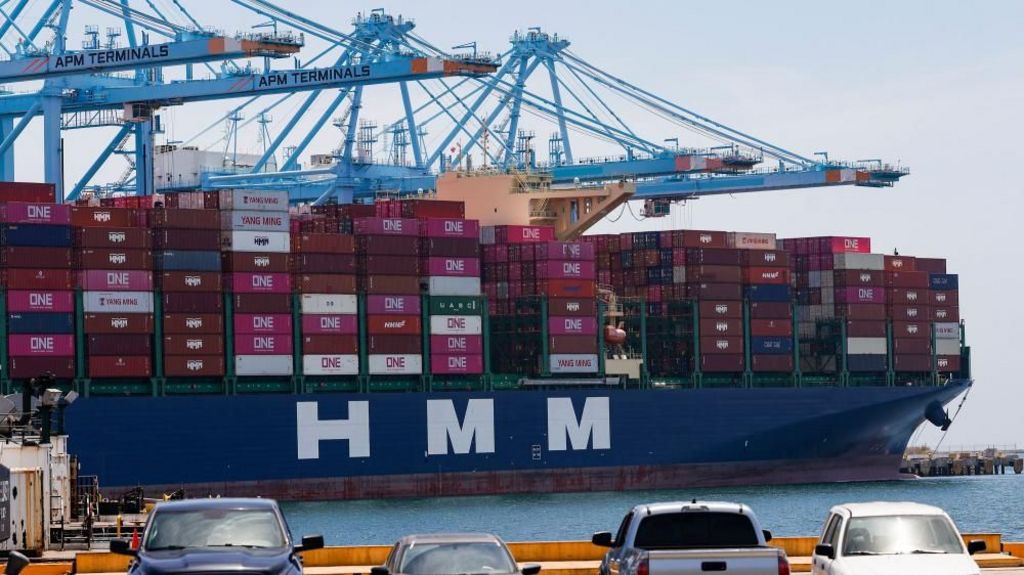
    Across Europe, the Middle East and North America, top oil producers have reported blowout profit growth in the first and second quarters of 2024, built on the back of elevated energy prices triggered by disrupted shipping through the Strait of Hormuz, the world’s busiest chokepoint for global oil trade. Roughly 20% of the planet’s daily oil supply moves through the strategic waterway, which has been largely closed to commercial tanker traffic since the outbreak of conflict in late February.

    Six of Europe’s biggest oil companies amassed a combined $22 billion in net profit during the first quarter, a jump of more than 40% compared to the same period last year. London-based BP extended that winning streak into the second quarter, announcing Tuesday that its profits more than doubled to $3.9 billion. Saudi Aramco, the world’s largest crude exporter, posted an even stronger performance: the state-owned energy giant notched a 44% year-over-year increase in second-quarter net profit, hitting $32.69 billion, lifted by rising prices for crude, refined fuels and chemical products.

    These blockbuster results from Middle Eastern and European oil majors follow similar blowout earnings reports from the largest U.S. oil drillers, released last week. Texas-based Exxon Mobil said Friday that its second-quarter profit doubled to $14.5 billion, fueled by record diesel production, with overall revenue climbing 42% to $116 billion. Houston-based Chevron saw an even steeper gain, with profits nearly quadrupling to $12 billion and revenue surging 56% to over $70 billion.

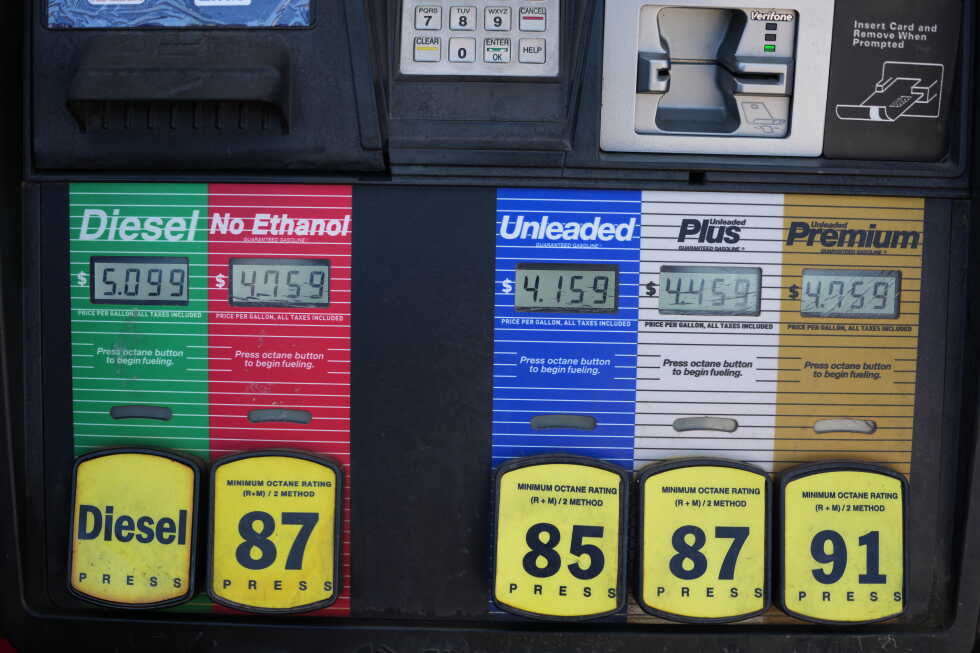
    For consumers worldwide, the energy market disruption has translated directly to higher everyday costs. Elevated oil prices have pushed up prices for gasoline, jet fuel and diesel, raising shipping costs for all goods that rely on ground, air or sea transport. In Western countries, this has translated to more expensive fill-ups at the gas pump and higher airfares for travelers. But the impact is far more severe across much of Asia, which relies disproportionately on oil exports that pass through the Strait of Hormuz. Several Asian nations have already faced acute fuel shortages, forcing governments to implement fuel rationing and temporarily close schools and public offices.

    The soaring profits of big oil have drawn sharp criticism from U.S. President Donald Trump, who slammed the companies this week for what he called outsized gains even after oil prices fell to a three-week low on Tuesday.

    “They made too much money, too much money,” Trump told reporters Monday. “They ought to give some of that back to the public, and they better cut the retail price.” Trump added that he was unhappy with the results posted by Chevron and Exxon Mobil, despite the fact that energy prices only spiked after the U.S.-backed military actions in Iran that led to the closure of the Strait of Hormuz.

    Oil prices dipped sharply this week, following comments from U.S. Treasury Secretary Scott Bessent, who told CNBC that a deal to reopen the Strait of Hormuz could come as soon as 24 hours. On Tuesday, U.S. crude fell 5.4% ($4.36) to settle at $75.98 per barrel, down from roughly $92 per barrel in late July, but still more than 13% higher than levels seen before the conflict began. International benchmark Brent crude also dropped 4.9% to $83.87 per barrel.

    A diplomatic resolution to the five-month-long conflict would allow hundreds of tankers carrying oil and energy products trapped in the Persian Gulf to resume their journey to global markets, easing supply shortages.

    Despite the recent pullback in oil prices, shares of major oil companies have outperformed broader markets by a wide margin this year, with stock values climbing between 20% and 30% — far outstripping the 13% gain logged by the S&P 500 index over the same period.
  • Japan’s Toyota reports hefty profit on cheap yen and solid car sales

    Japan’s Toyota reports hefty profit on cheap yen and solid car sales

    TOKYO – Japanese automotive giant Toyota Motor Corp. delivered a standout financial performance in the first quarter of its current fiscal year, with net profit almost doubling year-over-year, fueled by robust consumer demand across key North American and Asian markets and a favorable yen-dollar exchange rate that amplified overseas earnings for the exporter.

    For the April-June quarter, Toyota, which produces the popular Prius hybrid line and premium Lexus brand, reported net profit of 1.48 trillion Japanese yen, equal to roughly $9.4 billion. That marked a sharp climb from 841 billion yen in the same three-month period a year earlier. Quarterly revenue also grew by 10% year-on-year to hit 13.5 trillion yen, or around $85 billion.

    As one of Japan’s largest export-focused manufacturers, Toyota benefits disproportionately from a weaker yen relative to the U.S. dollar, since overseas revenue converts to more yen when repatriated to the company’s home base. During the 2025 fiscal first quarter, the dollar traded at roughly 145 yen, while this year’s corresponding quarter saw the dollar average around 160 yen. While recent joint currency intervention by U.S. and Japanese authorities in the second quarter has pulled the dollar back to around 158 yen, that shift came too late to impact the first quarter results. In total, favorable currency movements added 345 billion yen ($2.2 billion) to Toyota’s operating profit in the quarter, and the company has set its full-year forecast around an exchange rate of 160 yen to the dollar.

    Notably, the company’s total global vehicle sales dipped slightly to 2.39 million units in the quarter, down from 2.41 million units in the prior year’s first quarter. Despite that small quarterly dip, Toyota remains optimistic about full-year volume, projecting it will sell 9.7 million vehicles across the 12-month period – an increase from 9.595 million units sold in the previous full fiscal year.

    Toyota’s top leadership noted that ongoing strong consumer appetite for the company’s hybrid models has been a core growth driver across major global markets. In the U.S., two of the brand’s top sellers – the Camry midsize sedan and RAV4 compact SUV – continue to move off dealer lots at a brisk pace, while hybrid models including the Urban Cruiser and Innova Hycross have sustained high demand in India. The Yaris also maintains strong sales momentum in both Thailand and European markets, the company added. Toyota’s electric vehicle segment is also performing well, and the automaker has laid out long-term plans to ramp up production of both hybrids and hybrid batteries through 2030 while lowering production costs to improve accessibility.

    Despite the strong quarterly results, Toyota is navigating a set of ongoing and emerging headwinds that could impact performance through the rest of the fiscal year. Ongoing political instability in the Middle East has created disruptions for Japanese automakers, which rely heavily on shipping routes through the Strait of Hormuz, which has been effectively closed amid regional tensions. Toyota officials confirmed the company is already taking steps to mitigate these risks, including securing alternative shipping routes to avoid the conflict zone.

    More recently, a 7.1-magnitude earthquake that struck Kumamoto in southwestern Japan on July 28 has forced temporary production shutdowns at the company’s local facilities. Toyota’s Tahara plant has halted output for five days through the end of this week, and the shutdown will be extended through the end of July when the plant goes into a previously scheduled unrelated summer break, pushing all production offline through the end of the month. The full financial impact of the shutdown is still being assessed.

    Looking ahead to the full fiscal year ending in March 2027, Toyota is projecting total net profit of 3.25 trillion yen ($20.6 billion), which is lower than the 3.85 trillion yen ($24 billion) profit the company recorded in the prior fiscal year. Full-year sales are forecast to climb to 54 trillion yen ($342 billion), up from 50.7 trillion yen in the 12-month period that ended in March this year. In response to the earnings release, Toyota shares declined by nearly 2% during trading on the Tokyo Stock Exchange Tuesday.

  • ASX 200 soars to five-month high after Donald Trump peace talks on Iran

    ASX 200 soars to five-month high after Donald Trump peace talks on Iran

    A wave of investor optimism sparked by reports of ongoing US-Iran peace negotiations under former President Donald Trump has delivered a sharp boost to Australia’s benchmark stock index, pushing the ASX 200 to its highest level in five months. The key index climbed 126.50 points, a 1.40% gain, to close at 9145.80 on Tuesday, while the broader All Ordinaries index followed suit with a 1.45% jump of 133.50 points, finishing the trading session at 9311.90. The Australian dollar also strengthened against the US dollar, rising to 70.19 US cents by market close. Nearly all sectors recorded gains on the day, with 10 out of 11 industry groups finishing in positive territory, led by triple-digit growth in technology, healthcare and financial stocks. Tech stocks led the rally: logistics tech firm WiseTech Global rose 3.05% to $37.86, cloud accounting platform Xero gained 3.49% to hit $73.80, and data centre operator Next DC climbed 4.15% to close at $14.04. Healthcare stocks also posted robust gains: vaccine manufacturing giant CSL added 3.64%, medical imaging firm Pro Medicus outperformed many peers with a 4.94% rise to $172.82, and cochlear implant producer Cochlear gained 1.31% to reach $122.32. Australia’s four largest national banks all contributed to the financial sector’s 1.93% overall jump. National Australia Bank (NAB) led the pack with a 3.00% bounce to $42.85, ANZ rose 2.36% to $38.17, Westpac gained 1.70% to $38.82, and the Commonwealth Bank of Australia closed up 1.59% at $180.72. Tuesday’s bullish trading on the Australian exchange followed a positive overnight session on Wall Street, which rallied after Trump announced that negotiations to end escalated conflict with Iran and reopen the strategically critical Strait of Hormuz were underway. Tony Sycamore, senior market analyst for global financial services firm IG, noted that market participants have reacted strongly to signals of de-escalation in the Middle East. “The ASX200 hit the turbochargers today,” he explained, adding that the local exchange benefited not just from a solid Wall Street lead, but also from more stable market positioning after last week’s sharp sell-off in tech stocks, combined with easing geopolitical tension following Trump’s decision to pause planned military strikes on Iran. While de-escalation typically puts downward pressure on oil prices, Brent crude edged up slightly to near $85 a barrel on Tuesday, a small recovery following a sharp price drop the previous trading day. Samara Hammoud, international economics foreign exchange strategist for the Commonwealth Bank, explained that the modest oil gain came even as Trump offered Iran what he described as a “last chance” for diplomacy after calling off what he said would have been the largest military attack on the country since World War II. Hammoud also noted that Iran has denied holding direct negotiations with the US, but confirmed that talks mediated by Oman to reopen the Strait of Hormuz – currently closed to commercial shipping – are making progress. The small uptick in crude prices helped lift the energy sector, with major Australian producer Woodside Energy gaining 1.38% to $32.95 and competitor Santos adding 0.91% to $7.76. Not all stocks recorded gains on the session. Debt collection firm Credit Corp fell 6.98% to $12.79, despite reporting a 12% rise in quarterly profits driven by strong growth in its US debt-buying division. Investors sold off the stock over concerns that its recent rapid price growth was unsustainable. Mining giant BHP recorded a modest 0.33% drop to $60.52, after trade unions confirmed planned 48-hour strike action set for August 8 and 9 over an ongoing pay dispute. Infrastructure firm Atac Arteria also slipped 0.79% to $5.05 after the company announced it was abandoning plans to sell its German motorway assets.

  • US states sue to block Trump tariffs impacting dozens of countries

    US states sue to block Trump tariffs impacting dozens of countries

    In a direct legal challenge to the Trump White House’s latest trade agenda, a coalition of 25 Democratic-led U.S. states filed a lawsuit Monday against the administration over sweeping new tariffs imposed on trading partners across the globe. The levies, which set rates between 10% and 12.5%, went into effect last month, and the White House has defended the measures as a necessary response to the failure of major economies including the European Union, the United Kingdom, and China to crack down on forced labor in global supply chains.

    The legal filing, reviewed by the BBC, argues that the Trump administration’s tariff decision is “arbitrary, capricious, and contrary to law.” The coalition goes further, accusing the White House of using forced labor concerns as a pretext to advance an illegal tariff scheme that exceeds the scope of existing U.S. trade legislation. According to the complaint, the breadth of the tariffs — which cover 99.4% of all U.S. imports, per data from the Office of the U.S. Trade Representative — directly undermines the stated goal of targeting forced labor and renders the underlying 1974 Trade Act Section 301 authority the administration invoked meaningless.

    New York Governor Kathy Hochul, one of the lead voices behind the lawsuit, framed the measures as an unlawful tax that falls squarely on everyday American households. Oregon Attorney General Dan Rayfield echoed that criticism, noting that both working families and domestic Oregon businesses are bearing the cost of the administration’s trade chaos, rather than the foreign governments the tariffs are meant to pressure.

    In an official response, White House spokesman Kush Desai defended the policy, emphasizing that the U.S. is acting within its lawful authority to address unfair trade practices that harm American businesses. Desai added that allowing goods produced with forced labor to enter U.S. markets is unreasonable, and the administration is right to take action to curb the practice.

    The legal challenge comes amid growing international pushback against the new tariffs. Governments of Brazil and Japan have each labeled the measures unjustified, while China’s foreign ministry spokesperson Mao Ning dismissed the forced labor framing as an excuse for political manipulation. The new tariffs come amid a long-running tit-for-tat trade war between Washington and Beijing that has been paused for months.

    Industry and trade analysts have also raised critical questions about the policy. Alex Capri, a business lecturer at the National University of Singapore, told the BBC the lawsuit poses a formidable challenge to the administration’s levies. Capri also noted that there is a lack of credible evidence supporting the administration’s claims that trading partners have harmed U.S. firms by failing to enforce forced labor regulations, and he expects the scope of the tariffs will gradually be narrowed through exemptions and rollbacks that reduce their economic impact.

    This latest legal fight is the continuation of a pattern of trade policy clashes that have followed Trump’s return to the Oval Office in January 2025. Earlier this year, the U.S. Supreme Court struck down the broad “Liberation Day” tariffs Trump rolled out in April 2025, a decision that required the government to issue tens of billions of dollars in refunds to U.S. companies that had paid the levies. After those tariffs were struck down, the administration replaced them with a temporary 10% levy on all global imports that expired in July, clearing the way for the current round of tariffs now facing legal challenge.

    Trump has consistently argued that tariffs are a critical tool to protect American workers and strengthen the U.S. economy. Looking ahead, more trade friction may be on the horizon: the administration is currently conducting investigations into 16 countries over allegations of manufacturing overcapacity, which could pave the way for additional tariffs in the coming months.

  • Asian shares mostly dip after US stocks rally

    Asian shares mostly dip after US stocks rally

    On Tuesday, most major Asian stock markets finished the trading session in negative territory, even as a strong rally unfolded on Wall Street one day earlier, driven by falling global oil prices that calmed persistent investor concerns over rising inflation. The downturn across much of Asia came as regional market participants continued to assess the long-term implications of the recent coordinated currency intervention carried out jointly by the United States and Japan to shore up the weakening Japanese yen.

    Japan’s benchmark Nikkei 225 index slipped 0.6% to close at 63,369.85, as the U.S. dollar edged slightly higher against the yen, rising to 157.63 yen from 157.18 yen in previous trading. The euro saw barely any movement against the dollar, holding at $1.1511 compared to $1.1514 from the prior session. Before the joint intervention, the dollar had traded as high as the 160-yen mark, a level that triggered policymakers’ action to reverse the yen’s steep decline.

    Market analysts remain divided over the long-term effectiveness of the intervention, with many pointing out that the action fails to address the core economic drivers behind the yen’s slump, including divergent inflation trends, a wide gap in interest rates between the U.S. and Japan, and the relative uneven strength of the two nations’ economies.

    A research report from BMI, a division of Fitch Solutions, noted that a coordinated intervention backed by the United States carries far greater symbolic signaling power than an intervention carried out by Tokyo alone. The report added that the public pledge of additional future action is likely to make currency speculators pause before betting further against the yen, but any large-scale sustained contribution from U.S. authorities will probably be limited in scope.

    Matthew Ryan, head of market strategy at global financial services firm Ebury, offered a more optimistic take, arguing that the latest joint intervention signals a genuine shift in monetary policy stances rather than just a one-off defensive move. He called the development “historic and meaningful” for the yen, adding that it materially improves confidence in his firm’s prediction that the yen will see moderate gains in coming months.

    Across other regional markets, South Korea’s Kospi index ticked down by less than 0.1% to 6,254.76. Australia’s S&P/ASX 200 bucked the regional downtrend, climbing 1.2% to close at 9,128.60. Hong Kong’s Hang Seng index fell 0.5% to 25,881.99, while mainland China’s Shanghai Composite slipped 0.2% to 3,802.61.

    On Monday, U.S. stocks notched strong gains after easing oil prices helped ease investor fears that inflation would accelerate further. The broad S&P 500 jumped 1.5%, ending the day just 0.1% below the all-time record it set earlier this summer. The Dow Jones Industrial Average, which tracks 30 large U.S. corporations, gained 693 points or 1.3% to hit a new all-time closing high, while the tech-heavy Nasdaq composite rose 2.1%.

    In early Asian energy trading on Tuesday, benchmark U.S. crude added 50 cents to reach $80.84 a barrel. Brent crude, the global benchmark for oil pricing, rose 63 cents to $84.40 a barrel. A day earlier, Brent prices fell after former U.S. President Donald Trump announced over the weekend that he would delay planned military strikes against Iran, following urging from regional allies. Over the past month, Brent crude prices swung wildly between $72 and $102 a barrel, as market sentiment shifted back and forth over escalating tensions in the Middle East and uncertainty around when oil tankers would be able to resume safe transit through the Persian Gulf to deliver crude to global markets.

    The yield on the 10-year U.S. Treasury note fell to 4.68% from 4.75% recorded late Friday, but it remains well above the 3.97% level seen before the outbreak of military tensions with Iran.

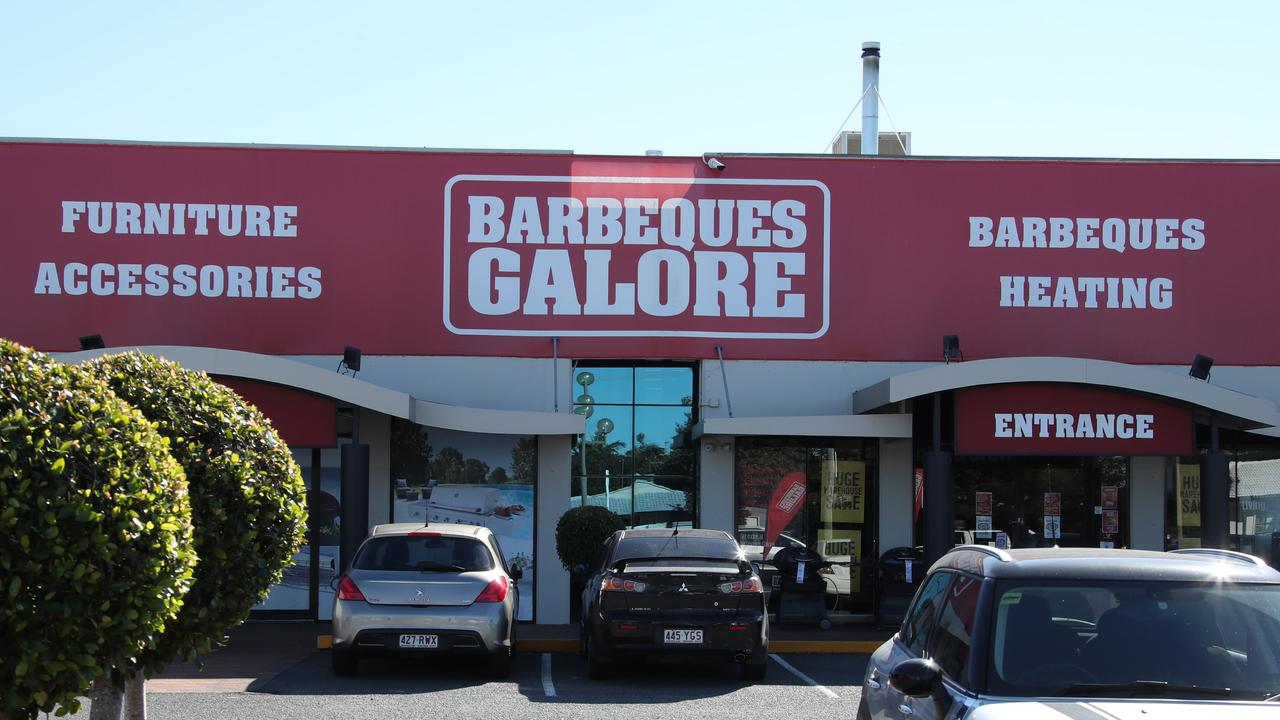
  • Iconic retailer Barbeques Galore sold in last-minute rescue deal, but all company-owned stores to shut

    Iconic retailer Barbeques Galore sold in last-minute rescue deal, but all company-owned stores to shut

    One of Australia’s most iconic outdoor lifestyle retail brands, Barbeques Galore, has narrowly avoided total collapse after a Victorian-based wholesale firm Acom International sealed an 11th-hour acquisition deal, but the rescue comes with significant caveats that underscore ongoing pressures facing brick-and-mortar retail across the country.

    Acom International confirmed the purchase on Monday, revealing it has acquired Barbeques Galore’s full intellectual property holdings, established brand portfolio, and existing wholesale inventory from the business’s receivers. The acquisition covers the company’s entire stable of well-known regional brands, including Ziegler Brown, Ziggy, Turbo, Beefmaster, Firehawk, Arrosto Pizza Ovens, Downunder, Saxon, Maxiheat, and Kent.

    Under the new ownership structure, Barbeques Galore will transition to a hybrid operating model focused on a refreshed national online platform and expanded wholesale distribution, rather than retaining company-operated physical storefronts. The terms of the deal require the permanent closure of all company-owned retail locations, though independently franchised Barbeques Galore outlets will be permitted to continue operations under their existing licensing agreements.

    Since the retailer first entered voluntary administration in February, putting roughly 500 Australian jobs at risk, the future of those positions remains unresolved following the latest acquisition. No details have been released on how many roles will be retained through the transition to the new operating model.

    As part of the deal, long-time Barbeques Galore executive Mike Ainsworth has been appointed as the business’s new chief executive officer. Outlining Acom’s strategic vision for the brand, Ainsworth said the company’s core goal is to make Barbeques Galore and its popular line of barbecue and wood-heating products accessible to more consumers across Australia. “We will do that by supporting our independent Barbeques Galore stores, expanding distribution through wholesale customers and other retailers, growing our export markets, and maintaining a strong national online presence,” he added.

    Monday’s successful acquisition marks the second attempt to rescue the struggling retailer after a prior last-ditch rescue plan fell through in June. Barbeques Galore first entered voluntary insolvency protection in February, and by June, U.S.-based investment firm Gordon Brothers had tabled a recapitalization proposal that would have also shuttered all 62 company-owned stores. Though the Gordon Brothers plan won backing from the retailer’s creditors, negotiations failed to secure acceptable commercial trading terms with key stakeholders including suppliers and property landlords. The $5 million creditor payment that was central to the original proposal will now never be disbursed, as the deal collapsed entirely before implementation.

    The outcome of the Barbeques Galore rescue highlights the ongoing challenges facing traditional physical retail in Australia, even when iconic local brands are able to avoid full liquidation through acquisition.

  • Qantas eyes cutting 1000 office jobs in major artificial intelligence overhaul

    Qantas eyes cutting 1000 office jobs in major artificial intelligence overhaul

    Australian aviation giant Qantas is once again at the center of industrial controversy, as reports emerge that the company is considering cutting or offshoring up to 1,000 back-office roles to India amid a company-wide push to integrate artificial intelligence into core operations. The airline has confirmed it is in early-stage consulting discussions with global professional services firm Accenture around an initiative dubbed Project iQ, which focuses on optimizing operational workflows through expanded AI adoption. A final decision on restructuring roles across marketing, finance, human resources and other corporate support departments is expected to be finalized by the end of 2024. In a statement to NewsWire, a Qantas spokesperson emphasized the company’s goal of modernizing work processes to improve outcomes for both customers and employees, noting that no formal partnership agreement or final restructuring decisions have been reached to date. The company also pushed back on criticism of its employment strategy, pointing to thousands of new operational roles added across Australia in recent years, as well as a new 400-position technology hub currently being developed in Adelaide. The airline is set to release its full-year 2024 financial results in late August, after reporting a largely flat first-half performance that delivered a statutory after-tax profit of $925 million – a marginal $2 million increase compared to the same period in 2023. The proposed restructuring has drawn sharp condemnation from the Australian Services Union (ASU), which has warned it will mount a vigorous campaign to protect every at-risk position. ASU Assistant National Secretary Scott Cowan called for urgent direct talks with Qantas Chief Executive Vanessa Hudson on Tuesday, noting that the airline has given public assurances that no Australian roles will be offshored. “If that commitment turns out to be empty, it will not just be a broken promise to our union – it will be a profound breach of trust with the Australian public, which stood by this airline through every crisis it has faced,” Cowan said. This is not the first time the union has had to seek formal guarantees from Qantas that AI integration will not be used as justification for layoffs, Cowan added, calling on the airline to use new AI tools to augment its skilled workforce rather than cut roles. The controversy also renews scrutiny of Qantas’ long history of outsourcing and offshoring, including a high-profile illegal layoff during the COVID-19 pandemic. In that case, Qantas outsourced 1,800 to 2,000 ground handling roles to third-party contractors, a move that Australian courts ultimately ruled unlawful. The company was ordered to pay a $90 million fine for the violation, making the current proposed cuts a particularly sensitive issue for both the union and the traveling public.

  • Credit Corp shares plummet 15 per cent on full-year results amid US debt spree fears

    Credit Corp shares plummet 15 per cent on full-year results amid US debt spree fears

    Australia’s largest debt collection and purchasing firm, Credit Corp, has seen a sharp sell-off of its publicly traded shares after the company’s full-year financial results revealed an aggressive expansion push into the U.S. debt market that has spooked market participants.

    Listed on the Australian Securities Exchange (ASX), Credit Corp released its annual earnings report on Tuesday. Even with a solid 12.1% year-over-year jump in full-year profit and a 14% increase in total annual dividends compared to 2023, investor sentiment turned bearish almost immediately after the results hit markets. Within the first hour of trading, the company’s share price dropped 9%, and by midday local time, losses had deepened to 15%. The steep decline stands out against a broader market uptick, with the benchmark ASX 200 hitting a five-month intraday high on the same trading day.

    Credit Corp operates across four key markets: Australia, New Zealand, the United Kingdom and the United States. The firm specializes in two core lines of business: collecting outstanding delinquent debt, and extending lending to consumers who are considered too high-risk to access credit from mainstream banks and large lending institutions. Over the past 12 months, the company’s total lending volume surged 15% to reach AU$510.5 million. In its home region of Australia and New Zealand, annual debt collection revenue grew 4% to AU$260 million, according to the results. The most notable takeaway from the report, however, was the large volume of U.S. debt purchased by the company as part of its international growth strategy.

    In comments accompanying the earnings release, Credit Corp chief executive Thomas Beregi addressed ongoing macroeconomic pressures, pointing to the global cost of living crunch while highlighting the company’s strong record on consumer protection. “The impact of elevated costs of living has served to sharpen our focus on ensuring we respond to consumer hardship appropriately and engage respectfully with our customers,” Beregi said. He added that independent reporting from leading Australian financial counselling groups has ranked Credit Corp’s Australian debt purchasing division as the top-performing credit provider for consumer hardship response for three consecutive years. The company also maintains the lowest external dispute resolution complaint rate among large Australian debt buyers, a track record Beregi said the firm would preserve as it expands.

    Contrary to widespread concerns about rising consumer defaults amid cost of living pressures, Credit Corp’s financial results show that payment arrears and loan losses have remained within projected forecast levels, even as the company’s total loan book and purchased debt portfolio has expanded. “Arrears and losses remained within pro-forma levels despite the growth in the book and broader macro-economic uncertainty with continued cost-of-living pressures,” the report noted.

    Despite these reassuring metrics on consumer default risk, investors have focused heavily on the risks associated with the company’s U.S. debt buying spree. Industry analysts point to a key structural feature of the debt purchasing business that has left investors nervous: returns from newly acquired debt do not materialize until years after the purchase is made. “Debt buying earnings lag purchasing, so this is an FY2028 collections problem,” PAC Partners senior trader James Nicolaou explained in a market note following the earnings release. Nicolaou also noted that the stock had already rallied 25.7% over the three months leading up to the results, leaving it overpriced for an earnings report that failed to beat consensus analyst expectations. He added that earnings per share revisions had already been trending downward before Tuesday’s report.

    On a positive note for shareholders, the company declared a fully franked final dividend of 45.5 Australian cents per share. When combined with the earlier interim dividend of 32 cents per share, total annual dividends come in 14% higher than the previous year, outpacing the company’s profit growth for the period.

  • US regulators grant long-awaited Boeing 737 MAX 7 certificate

    US regulators grant long-awaited Boeing 737 MAX 7 certificate

    More than eight years after its first test flight took to the skies, Boeing’s 737 MAX 7 has officially received airworthiness certification from U.S. regulators, marking a long-awaited milestone for the aerospace giant after years of crisis and regulatory scrutiny. The Federal Aviation Administration (FAA) announced the approval of the MAX 7, the smallest and newest member of Boeing’s troubled single-aisle MAX jet family, on Monday. The certification process was stretched far beyond original timelines by strict new regulatory requirements imposed after two deadly 737 MAX crashes in 2018 and 2019 that killed 346 people and shook global confidence in Boeing’s safety oversight.

    The green light, which had been widely expected by industry observers and company insiders in recent weeks, immediately sent Boeing’s share price surging 8 percent in trading. This certification marks the first new Boeing aircraft model to win regulatory approval since the 2018-2019 crisis pushed the company into a years-long period of reputational and financial damage.

    “This important certification validates the rigor of our airplane’s design and recognizes the determination and resilience of our 737 MAX development team,” said Stephanie Pope, president of Boeing Commercial Airplanes. “Our team stayed focused on completing all requirements and delivering a safe and more capable airplane to our customers.”

    In its own statement, the FAA confirmed that the approval followed “almost a decade of extensive review” and “years of sustained work to resolve complex technical issues” on the program. Boeing initially targeted 2019 for the first deliveries of the 172-seat MAX 7, a timeline that collapsed entirely after the two fatal crashes, and was further complicated by a mid-flight fuselage blowout on an Alaska Airlines 737 MAX 9 flight in January 2024 that reignited safety concerns across the MAX program.

    To earn certification, Boeing completed an exhaustive testing regimen including 441 separate flight tests totaling 686 hours of airborne evaluation. The 2018 and 2019 crashes were ultimately traced to a poorly designed anti-stall system called the Maneuvering Characteristics Augmentation System (MCAS), which was found to activate improperly and overpower pilot controls. U.S. prosecutors later charged that Boeing intentionally misled FAA regulators about MCAS, leaving the system unmentioned in flight manuals and pilot training materials. Congressional hearings also revealed weak FAA oversight of Boeing as a contributing cause of the crashes, leading to 2020 federal legislation that required Boeing to install upgraded angle-of-attack (AOA) sensors across the entire global fleet of more than 2,300 existing MAX aircraft within a two-year window.

    Boeing is now closing in on a second key certification milestone for the MAX family: approval for the MAX 10, the largest variant that can carry up to 230 passengers. The company is also continuing to work through regulatory processes for the long-delayed 777X widebody jet program.

    With certification of the MAX 7 secured, Boeing is moving forward with plans to ramp up MAX production to meet years of accumulated backlogged orders. The company confirmed Monday it is already preparing the first customer aircraft for delivery to launch operator Southwest Airlines, which welcomed the FAA’s decision and said it expects to introduce the MAX 7 into revenue service “in the coming months.”

    Boeing CEO Kelly Ortberg, who took the helm in August 2024 in the wake of the Alaska Airlines incident, has centered his leadership on strict quality control and hitting incremental production targets. The FAA has already approved gradual production increases for the MAX line, raising monthly output from 38 aircraft to 42, and most recently to 47 jets per month. Last week, Ortberg told financial analysts he does not expect major supply chain disruptions to slow the company’s plan to lift monthly MAX production to 52 jets, though he acknowledged challenges ahead as output climbs further.

    “I think it’s going to get harder as we go from 52 to 57 and beyond that. We’ll just have to see how well we’re all collectively doing,” Ortberg said. “But look, we’re on our plan. Our plan’s working.”

    In July, Boeing opened a new MAX production line at its Everett, Washington facility that is designed to support the target of 52 monthly MAX deliveries. Reaching this output level is critical to the company’s medium-term financial recovery goals, which include generating $10 billion in annual free cash flow after years of underperforming earnings that have weighed heavily on shareholder returns.

  • Why is Trump Media selling early access to Trump’s Truth Social posts?

    Why is Trump Media selling early access to Trump’s Truth Social posts?

    In a surprising business move that has sparked widespread discussion across digital and political circles, Trump Media & Technology Group, the parent company of former U.S. President Donald Trump’s social platform Truth Social, has introduced a high-cost premium service that grants elite subscribers early access to posts from high-profile accounts on the network.

    According to industry reports, the exclusive offering can cost eligible participants as much as $100,000 (equivalent to roughly £74,170) per calendar month for the privilege. The core perk of this premium tier is a significant time advantage: paying subscribers receive the content from influential Truth Social accounts milliseconds before those posts are made visible to the general public on the platform.

    For context, Truth Social was launched in 2022 as an alternative social media platform after Donald Trump was banned from major mainstream platforms including Twitter (now X) and Facebook following the 2021 Capitol riot. Since its launch, the platform has worked to build a loyal user base and generate consistent revenue to support its operations and growth goals. The launch of this high-priced early access program marks one of the most unconventional monetization strategies adopted by a major social media platform in recent years, drawing attention both to the company’s revenue priorities and the potential implications of pay-to-play early access for social media information dynamics.