分类: business

  • China meets initial soybean purchase goal, but Trump’s shifting trade policy could disrupt deal

    China meets initial soybean purchase goal, but Trump’s shifting trade policy could disrupt deal

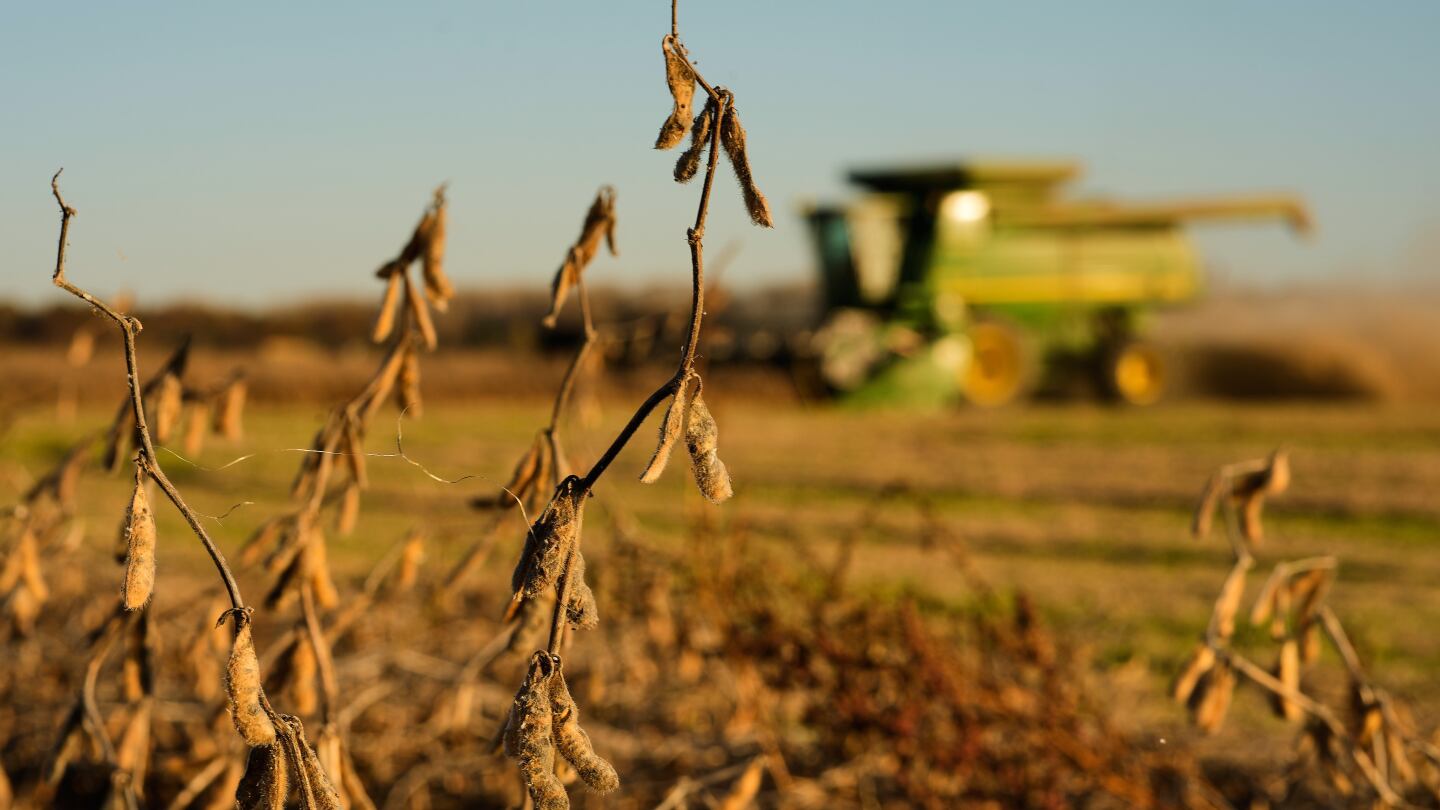
    Despite China fulfilling its initial commitment to purchase 12 million metric tons of American soybeans, the sustainability of the October trade agreement remains uncertain due to the Trump administration’s volatile trade policies. Treasury Secretary Scott Bessent confirmed China’s compliance during the World Economic Forum in Davos, where he met with Chinese Vice President He Lifeng, who reaffirmed Beijing’s commitment to future purchases.

    The agreement, forged after Trump and Xi Jinping’s meeting in South Korea ended last summer’s purchasing halt, requires China to buy 25 million metric tons annually over the next three years. However, recent policy shifts—including threatened tariffs on countries trading with Iran and proposed levies on European allies—create instability that agricultural economists warn could jeopardize the deal.

    American farmers continue struggling with soaring production costs for fertilizer, seeds, and labor, despite approximately $12 billion in federal aid. Soybean prices briefly surged to $11.50 per bushel post-agreement but have since fallen to $10.56—insufficient to cover most operational expenses. China’s strategic diversification toward Brazilian and Argentine suppliers, which now account for over 70% of its imports compared to America’s 21% share, further complicates long-term trade prospects.

    Agricultural experts like Iowa State’s Chad Hart and University of Nebraska’s Cory Walters emphasize that market unpredictability and evolving tariff landscapes are crippling farmers’ decision-making capabilities and financial stability.
  • Malawi raises fuel prices by more than 40%

    Malawi raises fuel prices by more than 40%

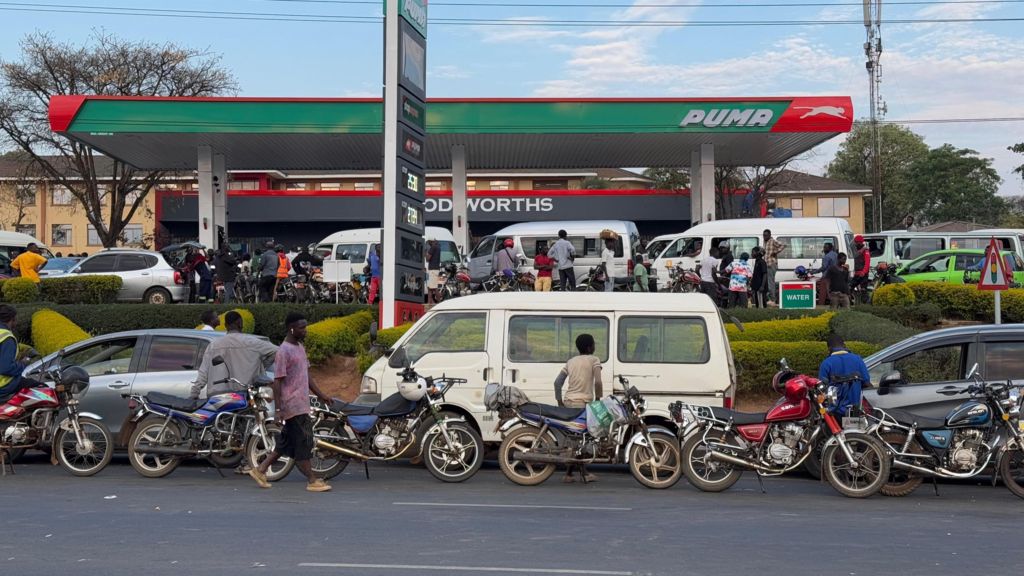
    Malawi’s Energy Regulatory Authority (Mera) has announced substantial increases in fuel prices, elevating petrol and diesel costs by over 40% in its latest adjustment. This development marks the second significant price hike within a four-month period, intensifying economic pressures on citizens already grappling with a cost-of-living crisis.

    The regulatory body justified Tuesday’s decision by declaring the previous administration’s fixed pricing mechanism ‘unsustainable,’ citing substantial financial losses under that system. Since President Peter Mutharika assumed office in October, cumulative fuel price increases have reached alarming levels—95% for petrol and 80% for diesel.

    Mera has transitioned to an automatic pricing mechanism that aligns fuel costs with international market fluctuations and shipping expenses. Dad Chinthambi, Mera’s acting CEO, emphasized that the adjustment is essential for maintaining sustainable fuel supplies, supporting electricity services, and funding critical infrastructure projects including road maintenance and rural electrification initiatives.

    Despite improvements in fuel availability compared to the severe shortages experienced under former President Lazarus Chakwera, the price surge has triggered immediate economic repercussions. Transportation fares have risen sharply nationwide, with anticipated increases in food prices and other essential goods following previous fuel and sales tax adjustments.

    The Human Rights Defenders Coalition, a Malawian civil society organization, warned that ‘fuel is not a luxury commodity’ and that any increase produces cascading effects throughout the economy. Many citizens have expressed disappointment through social media and radio programs, expecting the current administration to improve economic conditions rather than replicate previous outcomes.

    The government continues to pursue financial stabilization measures and is negotiating potential assistance packages with the International Monetary Fund amid growing economic challenges.

  • Türkiye’s gateway to global agriculture opens doors to MENA and international partnerships

    Türkiye’s gateway to global agriculture opens doors to MENA and international partnerships

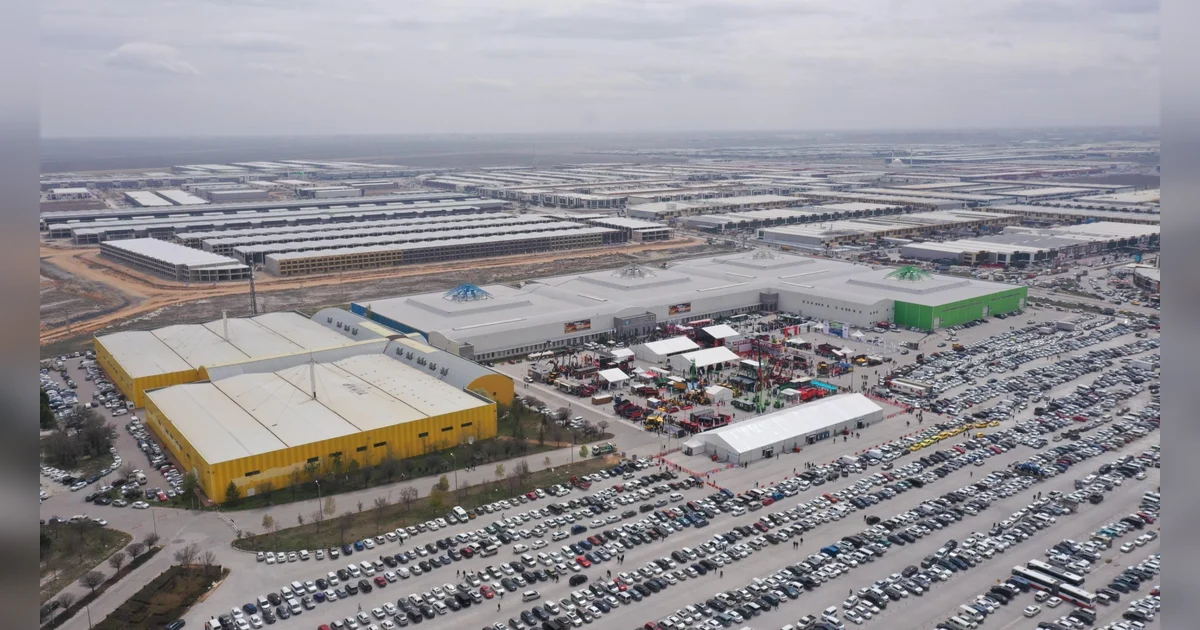
    Konya is poised to become the epicenter of agricultural technological advancement as Türkiye prepares to host its premier agricultural exposition in April 2026. The 22nd International Konya Agriculture, Agricultural Mechanization and Field Technologies Fair will convene at the Tüyap Konya International Fair Center from April 7-11, establishing itself as the nation’s most significant gathering for agricultural innovation and cross-border collaboration.

    Organized through a strategic partnership between Tüyap Exhibitions Group and the Turkish Agricultural Machinery and Equipment Manufacturers Association (TARMAKBİR), the event builds upon its remarkable 2025 achievement of attracting 251,000 visitors from 80 nations alongside 432 exhibitors representing 20 countries. This demonstrates the fair’s growing international significance within global agricultural circles.

    The 2026 edition occupies an expansive 96,000 square meter exhibition space, featuring cutting-edge agricultural technologies ranging from precision farming systems and smart irrigation solutions to advanced harvesting equipment and sustainable farming applications. The comprehensive showcase highlights Türkiye’s sophisticated industrial capabilities while addressing the pressing agricultural modernization needs of MENA nations.

    Water-stressed Middle Eastern and North African countries facing population growth and food security challenges represent a particularly crucial market segment. The event specifically targets agricultural professionals, investors, and public sector representatives from 17 MENA countries including Saudi Arabia, UAE, Egypt, Qatar, and Morocco through structured B2B matchmaking sessions and technology demonstrations.

    Supported by Türkiye’s Ministry of Agriculture and Forestry, the Turkish Chamber of Agriculture, Konya Metropolitan Municipality, and Konya Chamber of Commerce, the fair creates an unparalleled platform for knowledge exchange, technology transfer, and international partnership development. Visitors can explore the complete spectrum of agricultural mechanization from established equipment to revolutionary smart farming technologies during the five-day event.

    The strategic timing and location in Konya—Türkiye’s agricultural heartland—positions this event as a critical nexus for global agricultural stakeholders seeking to leverage technological innovation for enhanced food system resilience and sustainable farming practices across regions.

  • India, UAE sign $3 billion LNG deal, agree to boost trade, defence ties

    India, UAE sign $3 billion LNG deal, agree to boost trade, defence ties

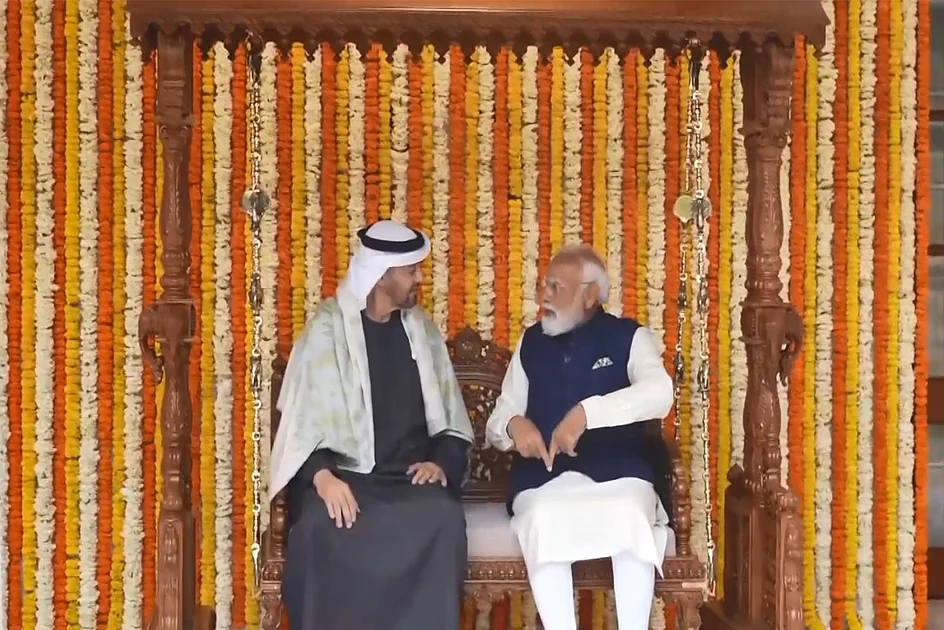
    India and the United Arab Emirates have solidified a landmark $3 billion liquefied natural gas agreement while committing to significantly expand their bilateral trade and defense cooperation. The deal was finalized during UAE President Sheikh Mohamed bin Zayed Al Nahyan’s brief but impactful two-hour visit to India for discussions with Prime Minister Narendra Modi.

    Abu Dhabi’s state energy giant Adnoc Gas will supply approximately 0.5 million metric tons of LNG annually to India’s Hindustan Petroleum Corporation Limited under a decade-long contract. This arrangement elevates India to the position of the UAE’s premier LNG customer and represents a substantial expansion of the energy partnership between the two nations. Adnoc Gas confirmed that this agreement brings their total contractual value with Indian partners to exceed $20 billion.

    The leadership summit yielded ambitious economic targets, with both countries pledging to double their bilateral trade volume to $200 billion within the next six years. The UAE currently stands as India’s third-largest trading partner, highlighting the significance of this enhanced economic commitment.

    Accompanied by a high-level delegation including defense and foreign ministers, the UAE leadership engaged in comprehensive talks that extended beyond energy cooperation. The two nations signed a letter of intent to establish a strategic defense partnership, though Indian Foreign Secretary Vikram Misri clarified that this enhanced security cooperation does not imply India’s involvement in regional conflicts.

    The brief but productive visit underscores the accelerating pace of Indo-Emirati relations, combining energy security with broader economic and strategic objectives that will shape the regional economic landscape for years to come.

  • 7 in 10 UAE residents plan to buy property this year: Are you one of them?

    7 in 10 UAE residents plan to buy property this year: Are you one of them?

    A significant majority of UAE residents are actively planning property acquisitions despite ongoing market price uncertainties, according to recent survey data. Property Finder’s bi-monthly Market Pulse research, conducted across November and December 2025 with 5,540 participants, reveals that seven out of ten residents intend to purchase real estate within the coming six-month period.

    The survey indicates a nuanced shift in buyer expectations regarding property valuations. During November, 40% of respondents anticipated price declines, while 32% projected increases and 28% expected market stability. By December, expectations moderated slightly with 39% forecasting decreases, 32% still predicting growth, and 29% anticipating unchanged prices. This represents a subtle but notable change from the September-October period when price decline expectations consistently ranged between 39-40%.

    Market analysts observe that while purchasers demonstrate heightened price consciousness, this awareness hasn’t substantially dampened acquisition intentions. The data suggests prospective buyers are proceeding with transactions rather than delaying decisions amid fluctuating market conditions.

    Driving this sustained demand is a demographic shift seeing increased participation from young professionals aged 25-35. This trend emerges from converging factors including escalating rental costs, mortgage payments that increasingly parallel leasing expenses, and more defined long-term residency options such as the Golden Visa program. Financial practicality now positions property ownership as a viable alternative to renting for many younger buyers seeking both financial security and flexibility.

    Industry experts simultaneously caution purchasers regarding substantial upfront capital requirements, typically representing 25-30% of property value for down payments and transaction fees not covered by mortgage financing. While improved affordability stems from easing interest rates and extended loan tenures, the initial financial outlay remains a significant consideration.

    Developers are responding with innovative payment solutions including reduced booking amounts, post-handover payment plans, and rent-to-own options designed to facilitate the renter-to-owner transition. Concurrently, financial institutions are enhancing market accessibility through digital tools like Mashreq’s recently launched fully digital home-loan pre-approval service. This platform provides salaried residents earning minimum Dh15,000 monthly with same-day preliminary approval based on income assessment, existing liabilities, and credit history, offering clearer budgetary parameters before purchase commitment.

  • Netflix updates Warner Bros bid to all-cash offer

    Netflix updates Warner Bros bid to all-cash offer

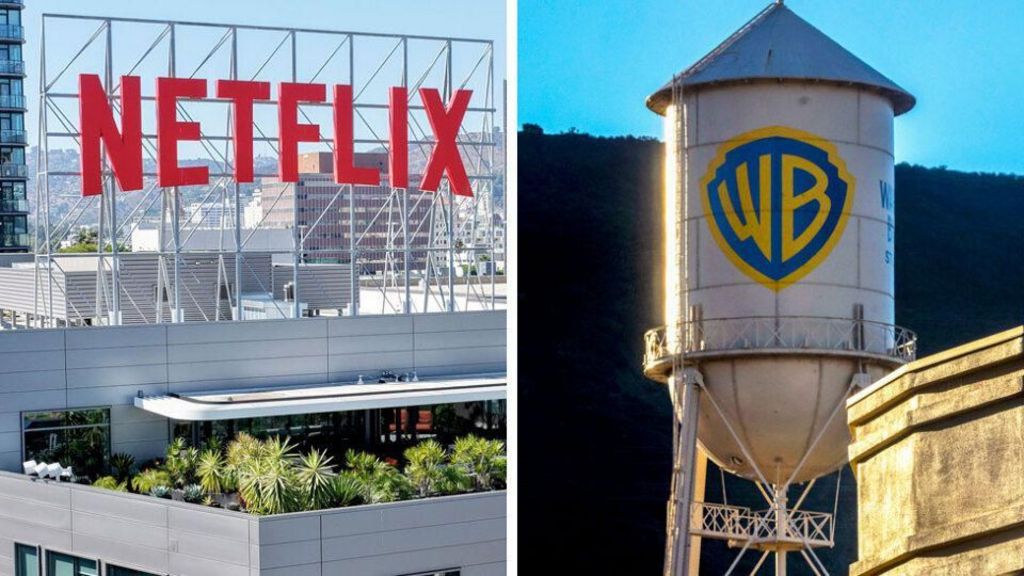
    In a significant escalation of the high-stakes battle for Warner Bros Discovery’s entertainment assets, Netflix has revised its acquisition proposal to an all-cash transaction valued at approximately $72 billion. This strategic move eliminates the previously proposed stock component, intensifying the streaming giant’s competition against Paramount Skydance for control of the prestigious Hollywood studio.

    The revised terms maintain the original $27.75 per share valuation for Warner Bros’ streaming and film divisions, which encompass the massively valuable HBO Max platform and legendary content libraries including the Harry Potter franchise and Game of Thrones universe. The total enterprise value, incorporating debt assumptions, reaches approximately $82 billion.

    Concurrently, Warner Bros shareholders would receive equity in the company’s remaining assets—including news network CNN—which are scheduled to become an independent publicly traded entity through a spinoff process.

    The amended agreement emerged as Paramount Skydance, backed by technology billionaire Larry Ellison and his family, continues its aggressive pursuit with a competing $108 billion overall valuation ($30 per share) offer. Paramount has maintained that Warner Bros’ non-entertainment assets are significantly overvalued, recently initiating legal action to force disclosure of financial details regarding Netflix’s proposal.

    Warner Bros leadership has consistently expressed preference for Netflix’s offer, citing greater certainty regarding financing and transaction execution. Samuel Di Piazza, Jr., Chair of the Warner Bros Discovery Board of Directors, stated: “Our amended agreement with Netflix demonstrates the board’s unwavering commitment to advancing stockholder interests. Transitioning to an all-cash offer delivers the tremendous value of our combination with Netflix with enhanced certainty.”

    Netflix executives positioned the acquisition as industry-positive, with co-CEO Ted Sarandos emphasizing: “This combination will provide broader choice and greater value to global audiences while expanding U.S. production capacity and driving substantial investment in original programming. This transaction represents growth and job creation for our industry’s future.”

    Despite criticism from some industry observers concerned about excessive market consolidation, the proposed merger continues advancing toward shareholder consideration, potentially reshaping the global entertainment landscape.

  • Ivory Coast will buy unsold cocoa stocks as prices plunge

    Ivory Coast will buy unsold cocoa stocks as prices plunge

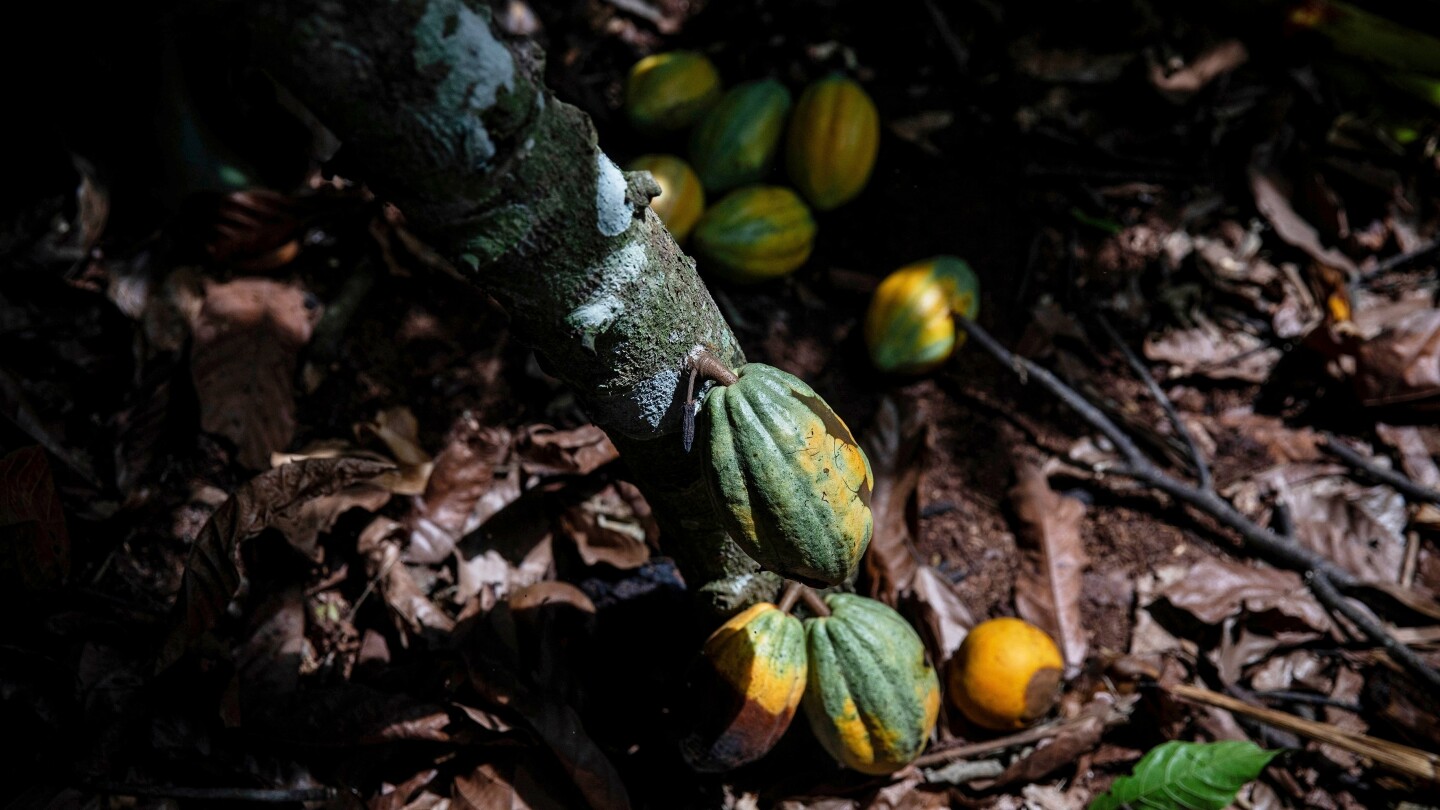
    ABIDJAN, Ivory Coast – The Ivorian government has announced emergency market intervention measures to address a severe crisis in its cocoa sector, the world’s largest. With approximately 700,000 tons of cocoa beans remaining unsold due to plummeting global prices, authorities will purchase existing stocks at guaranteed seasonal rates to maintain export operations and ensure farmer compensation.

    The crisis emerged in recent months as global cocoa prices sharply declined from record highs. According to Synapci, the nation’s primary cocoa farmers’ union, many agricultural producers have endured nearly two months without income, forcing some to sell at discounted rates or destroy spoiled inventory.

    Agriculture Minister Kobenan Kouassi Adjoumani sought to reassure stakeholders during a Tuesday press briefing. “We want to reassure them. The situation is now under control, and collection operations will begin in the coming days,” he stated, confirming the government’s commitment to market stabilization.

    Ivory Coast’s unique market structure differentiates it from most African nations. Through the Coffee and Cocoa Council, approximately 85% of the annual harvest (representing 2-2.5 million metric tons) is pre-sold at fixed prices to shield farmers from volatility. The current crisis involves the remaining 15% portion, which multinational buyers have refused to purchase following price declines.

    The government had set a record price of $5,000 per metric ton in October 2025 ahead of presidential elections, but global prices have since fallen to approximately $4,630. With the mid-crop season price announcement scheduled for April 1 expected to reflect further decreases, market uncertainty persists.

    Farmer representatives remain skeptical despite government assurances. Synapci President Moussa Koné questioned the implementation: “They are making nice promises, but what guarantees are they offering? And what about those who have already had to throw away cocoa that rotted because of the blockade?”

  • Dubai: Gold prices hit new record high on second consecutive day; 21K crosses Dh500

    Dubai: Gold prices hit new record high on second consecutive day; 21K crosses Dh500

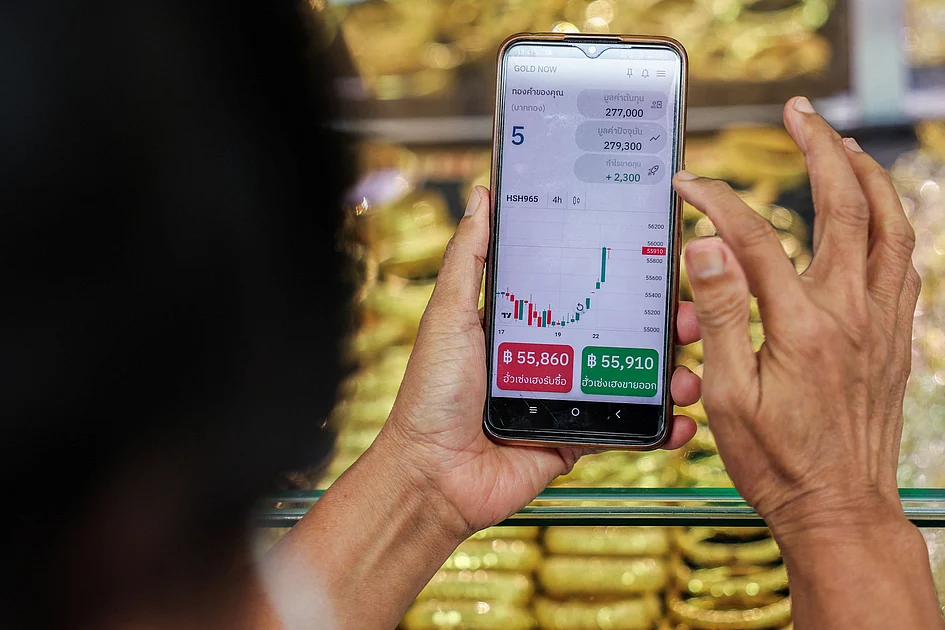
    Dubai’s gold market witnessed unprecedented milestones on Tuesday as prices surged to record-breaking heights for the second consecutive trading session. The precious metal’s remarkable rally saw 21K gold surpass Dh500 per gram for the first time in history, joining 24K and 22K variants that had previously breached this psychological barrier.

    Market data revealed 24K gold trading at an all-time high of Dh566 per gram, representing an increase of Dh3.75, while 22K reached Dh524.0 per gram with a gain of Dh3.25. The broader spectrum showed 18K and 14K gold trading at Dh430.75 and Dh336 per gram respectively, completing a comprehensive market upswing.

    According to Ahmad Assiri, Research Strategist at Pepperstone, this historic rally stems from escalating geopolitical tensions and renewed trade threats. Recent statements by the US President regarding potential tariffs of 10-25% on European goods have reignited global trade concerns within a broader geopolitical context that transcends traditional trade balance issues.

    European responses, particularly from France, have included discussions about activating the EU’s Anti-Coercion Instrument and preparing retaliatory tariffs worth approximately €93 billion on US goods. This escalating tension has positioned precious metals as primary beneficiaries of market uncertainty, with gold specifically maintaining its upward trajectory around the $4,700 per ounce threshold.

    Assiri identified three key drivers supporting gold’s rally: increased hedging demand, declining risk appetite in equity markets, and favorable macroeconomic factors including monetary policy expectations and a weakening US dollar. Globally, spot gold reached $4,714.34 per ounce at 10 AM UAE time, registering a 0.77% increase.

    The analyst projected that $5,000 per ounce represents a logical medium-term target rather than optimistic speculation, noting this price point remains approximately 7% above current levels. He emphasized that precious metals will likely maintain their defensive appeal until clearer negotiation pathways emerge, with gold positioned as the most prominent near-term beneficiary of ongoing political and economic uncertainty.

  • Skyscrapers set to redefine city skylines across the GCC

    Skyscrapers set to redefine city skylines across the GCC

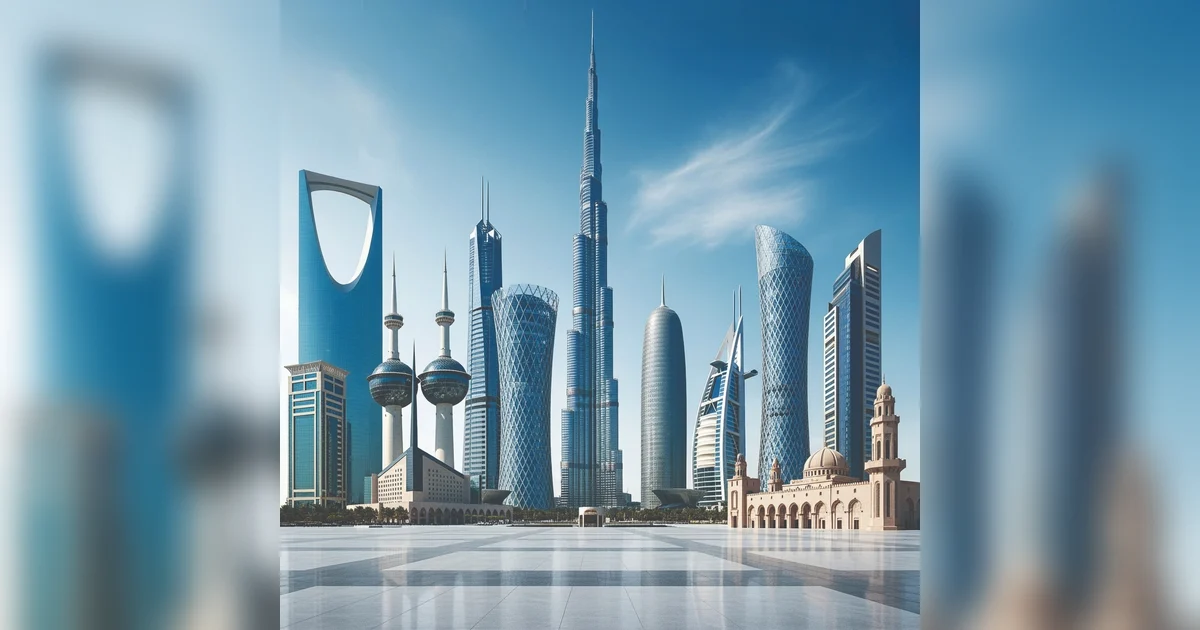
    The Gulf Cooperation Council (GCC) region is undergoing a transformative architectural renaissance, with skyscrapers evolving from symbolic landmarks into strategic infrastructure driving economic diversification. This vertical expansion represents a fundamental reimagining of urban development rather than mere height competition.

    Saudi Arabia has unveiled plans for an unprecedented architectural marvel—a two-kilometer tower in Riyadh that would double the height of Dubai’s Burj Khalifa. With an estimated $5 billion budget and a site selected near King Khalid International Airport, this project signals Riyadh’s ambition to become a global business hub. International architectural firms including Skidmore Owings and Merrill are already contributing conceptual designs for what would become the tallest structure in human history.

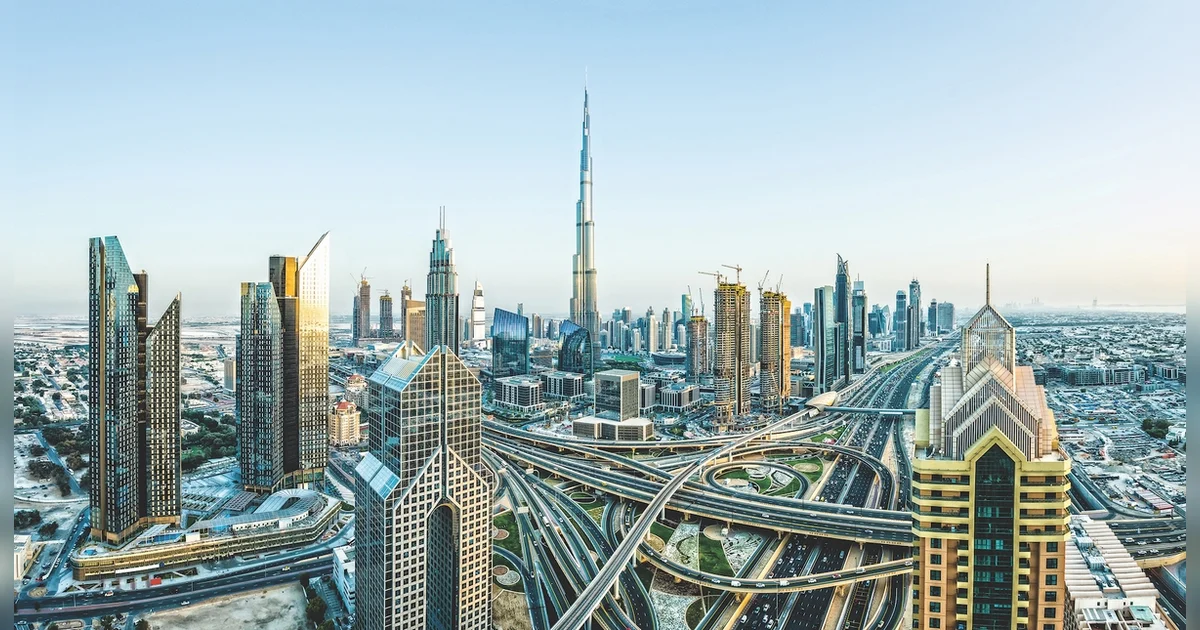
    Meanwhile, Dubai continues to reinforce its skyscraper expertise with Burj Azizi, a 725-meter vertical district featuring 130 floors of luxury residences, seven-star hotel suites, retail centers, and cultural spaces. The project’s commercial success was immediate, with a penthouse selling for Dh63 million on launch day, demonstrating sustained market demand for integrated vertical living environments.

    The United Arab Emirates has achieved global recognition, overtaking the United States as the second-ranking country for supertall buildings (exceeding 300 meters) according to the Council on Tall Buildings and Urban Habitat. With over 30 such structures—most built within the past decade—the UAE has established itself as a leader in futuristic design and engineering excellence.

    Beyond height records, GCC architects are developing culturally resonant designs. Dubai’s Muraba Veil tower, standing at 380 meters with a width of just 22.5 meters, represents this new direction. Designed by Pritz Prize-winning RCR Arquitectes, the tower incorporates regional architectural traditions through its stainless steel veil and internal courtyard design.

    This vertical transformation is driven by multiple structural factors: economic diversification requirements, population growth outpacing horizontal expansion capabilities, transit-oriented planning, and sustainability frameworks favoring compact cities. By 2030, the skylines of Riyadh, Jeddah, Dubai, Abu Dhabi, and Doha will reflect this strategic shift toward intentional, culturally grounded, and economically functional high-rise development that supports tourism, finance, and global business operations.

  • Hong Kong tourist arrivals up 12% in 2025

    Hong Kong tourist arrivals up 12% in 2025

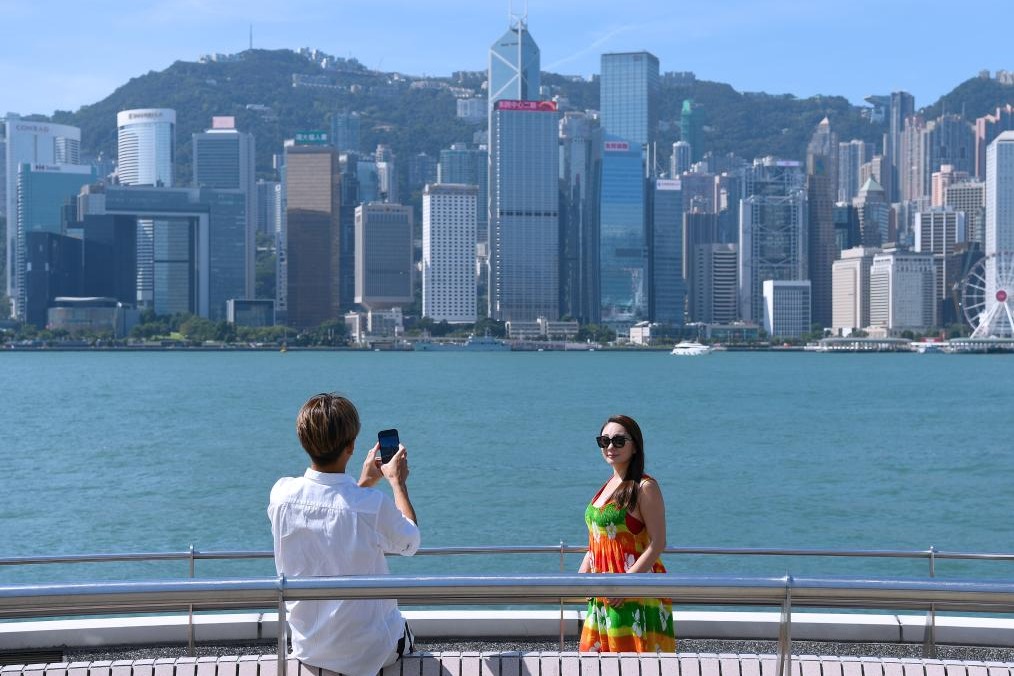
    Hong Kong’s tourism sector demonstrated robust recovery in 2025 with visitor arrivals reaching 49.9 million, marking a substantial 12% year-on-year increase according to official data released by the Hong Kong Tourism Board on January 20, 2026.

    The comprehensive statistics reveal particularly strong performance in December 2025, which saw 4.65 million tourist entries representing a 9% growth compared to the same period in the previous year. The data indicates a balanced recovery across source markets, with mainland Chinese visitors increasing by 11% to 37.8 million, while international arrivals from other global markets surged by 15% to 12.1 million.

    Notably, Japan and Australia emerged as the fastest-growing source markets, contributing significantly to the territory’s tourism rebound. The duration of stay metrics showed encouraging trends, with overnight visitors averaging 3.1 nights per stay. Tourist satisfaction levels reached impressive heights, scoring 8.9 out of 10 for overnight experiences.

    Looking ahead to 2026, Hong Kong tourism authorities are preparing for the Chinese New Year celebrations commencing February 17, featuring traditional attractions including fireworks displays, the International Chinese New Year Night Parade, and special horse racing events designed to attract global visitors.