In a strategic move mirroring U.S. trade practices, China has expanded its export control regulations, requiring foreign companies to seek Chinese government approval for exporting products containing even minimal amounts of China-originated rare earth materials or those produced using Chinese technology. This policy, announced this month, marks a significant escalation in the ongoing trade tensions between the world’s two largest economies. According to U.S. Trade Representative Jamieson Greer, this rule effectively grants China substantial control over the global technology supply chain, as even a South Korean smartphone manufacturer must now obtain Beijing’s permission to sell devices containing Chinese rare earth materials to markets like Australia. This development underscores China’s adoption of the U.S. foreign direct product rule, a decades-old policy that extends U.S. jurisdiction to foreign-made products, particularly those involving American technology. Neil Thomas, a fellow at the Asia Society Policy Institute’s Center for China Analysis, noted that Beijing is leveraging Washington’s playbook, having witnessed the effectiveness of U.S. export controls in constraining China’s economic and political options. The roots of this strategy trace back to 2018, when former U.S. President Donald Trump initiated a trade war with China, prompting Beijing to develop a robust toolkit of laws and policies to counter foreign sanctions and interventions. Measures such as China’s Unreliable Entity List and the anti-foreign sanction law, both modeled after U.S. practices, have been deployed to retaliate against U.S. trade actions. However, experts like Jeremy Daum of Yale Law School caution that such reciprocal measures risk escalating tensions and creating a race to the bottom, where neither side emerges victorious.
分类: business
-
Protests and food poisonings test Indonesian president’s first year in office
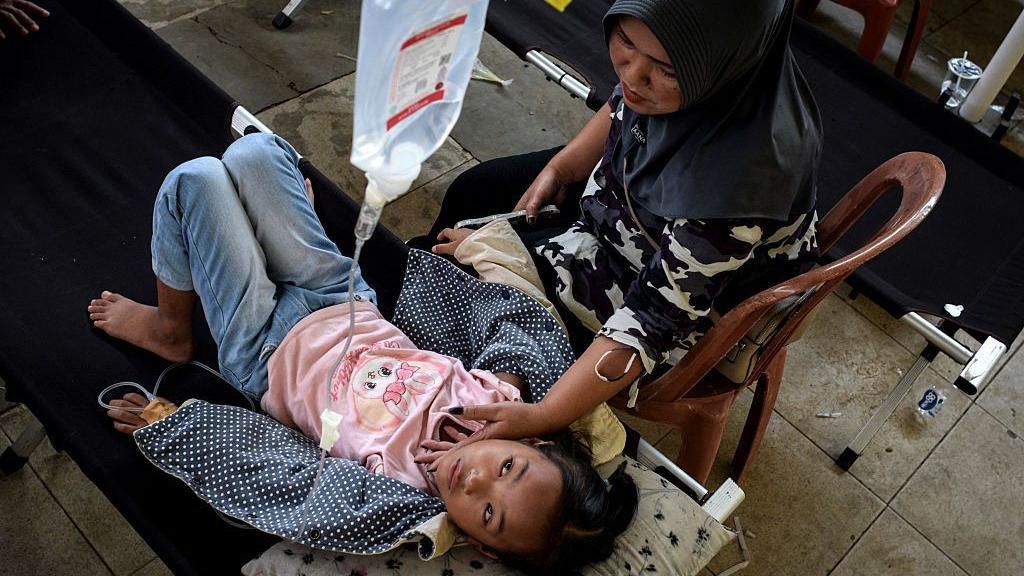
When Prabowo Subianto campaigned for Indonesia’s presidency, he promised transformative economic growth and significant social reforms. However, his first year in office has been marked by unmet expectations and growing public discontent. Despite steady annual growth of around 5%, Indonesia faces mounting pressures from slowing global demand, rising living costs, and regional competition from countries like Vietnam and Malaysia. These challenges have been exacerbated by widespread protests against corruption, inequality, and budget cuts in healthcare and education. Prabowo’s flagship free school meals program, aimed at addressing child malnutrition and improving education, has come under scrutiny following reports of mass food poisoning affecting over 9,000 children. Critics argue that the program, which costs $28 billion annually, is straining public resources and failing to deliver its intended benefits. Analysts warn that these issues highlight broader problems in public spending and oversight, pointing to deeper strains in Indonesia’s $1.4 trillion economy. Prabowo’s ambitious growth target of 8% by 2029 is seen as increasingly unrealistic, with economists citing falling car sales, shrinking foreign investment, and layoffs as signs of economic weakening. The abrupt dismissal of respected former finance minister Sri Mulyani Indrawati has further rattled investors, raising concerns about the government’s ability to manage public finances effectively. Despite these challenges, Indonesia continues to seek new trade partnerships, recently signing a long-negotiated deal with the European Union. However, the country’s ability to attract foreign investment and create jobs remains a critical issue, particularly in industries like manufacturing that have driven growth in neighboring countries. As Prabowo’s administration grapples with these economic hurdles, the future of Indonesia’s economy hangs in the balance.
-
Air Arabia flight plummets close to sea after takeoff; investigation launched
Italian aviation authorities have initiated a safety probe following a concerning incident involving an Air Arabia flight that descended perilously close to the Mediterranean Sea shortly after takeoff. The event, classified as a ‘serious incident’ by Italy’s Agenzia Nazionale Per La Sicurezza Del Volo (ANSV), occurred on September 20, 2025, when the Airbus A320 aircraft, operated by Air Arabia Maroc, departed from Catania Airport in Sicily, bound for Queen Alia International Airport in Jordan. The aircraft’s Ground Proximity Warning System (GPWS) alerted the pilots as it neared the sea surface, prompting immediate corrective action. The flight continued without further issues, and no passengers were onboard, though two pilots and four cabin crew members were present. Air Arabia Maroc has confirmed its full cooperation with the investigation, emphasizing its commitment to safety and transparency. This incident comes amid Air Arabia’s recent expansion, having received its first Airbus A320neo aircraft from a 120-plane order placed in 2019. The airline operates from six hubs across the Middle East, North Africa, and Europe. The investigation highlights ongoing concerns in aviation safety, particularly following a recent Air India crash near Ahmedabad in June 2025.
-
Crude oil at the crossroads: Brent risks $50 slide
The global oil market is teetering on the edge of a significant shift as Brent crude prices hover near $61 a barrel, with analysts warning of a potential collapse to $50 if demand softens further. The delicate balance between OPEC+ production increases and waning global consumption is under intense scrutiny, setting the stage for a pivotal moment in the energy landscape for 2026. Brent crude traded at $61.2 last week, while West Texas Intermediate (WTI) stood at $57.5, both benchmarks down nearly 15% year-to-date. Bank of America (BofA) remains optimistic, defending a $55 price floor, citing steady Asian demand and OPEC+ supply discipline. However, Citigroup predicts a deeper slide to $50, driven by fading economic momentum and geopolitical risk premiums. The International Energy Agency (IEA) reports global oil supply surged by 760,000 barrels per day (bpd) in September, reaching 108 million bpd—the highest since 2019. OPEC forecasts global demand at 105.1 million bpd in 2025 and 106.5 million bpd in 2026, with annual growth of 1.4%. OPEC+ recently approved a modest output hike of 137,000 bpd for November, contributing to rising oversupply concerns. The IEA warns that global inventories could hit record highs by 2026 unless demand accelerates. BofA expects Brent to average $61 in Q4 2025 and rise to $64 in early 2026, citing structural support at $55. Citigroup, however, sees a sharper decline, fueled by easing geopolitical tensions and weaker Chinese data. Geopolitical factors, including U.S.-China trade tensions and India’s resistance to curbing Russian crude imports, add further volatility. Technically, Brent is caught between support at $55 and resistance at $63.50–$64. A weekly close below $55 could validate Citigroup’s bearish outlook, while a move above $64 would support BofA’s stabilization thesis. Analysts anticipate consolidation rather than collapse, but sentiment remains fragile, with the market vulnerable to macroeconomic shocks.
-
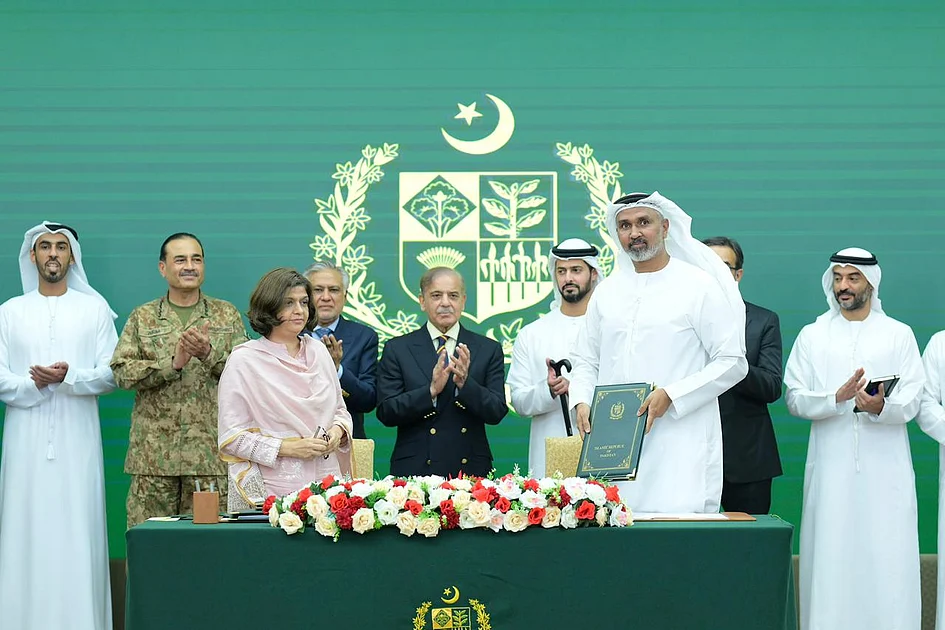
IHC acquires majority stake in First Women Bank, strengthening UAE–Pakistan economic partnership
In a landmark move to strengthen economic ties between the United Arab Emirates (UAE) and Pakistan, Abu Dhabi-based International Holding Company (IHC) has acquired a majority stake in Pakistan’s state-owned First Women Bank Limited (FWBL). The transaction, conducted under Pakistan’s Inter-Governmental Commercial Transactions Act of 2022, marks the first privatization of a bank in Pakistan under a government-to-government (G2G) framework. The announcement was made in the presence of Sheikh Zayed bin Hamdan bin Zayed Al Nahyan, Chairman of 2PointZero, and Pakistan’s Prime Minister Muhammad Shehbaz Sharif. Established in 1989, FWBL operates 42 branches nationwide, offering retail, SME, and corporate banking services. IHC’s investment aims to modernize the bank by integrating advanced technologies such as artificial intelligence (AI) and automation, enhancing its operational efficiency and expanding its footprint across Pakistan. The transformation strategy includes rebranding the bank to reflect its broader mandate of serving all societal segments and accelerating financial inclusion. Syed Basar Shueb, CEO of IHC, emphasized the company’s confidence in Pakistan’s financial potential and its commitment to fostering long-term economic growth. This acquisition follows IHC’s subsidiary, International Resources Holding (IRH), signing a joint venture with the Government of Balochistan in February 2025, further deepening UAE-Pakistan economic cooperation. Together, these initiatives underscore IHC’s vision of driving sustainable growth, technological transformation, and global economic connectivity.
-
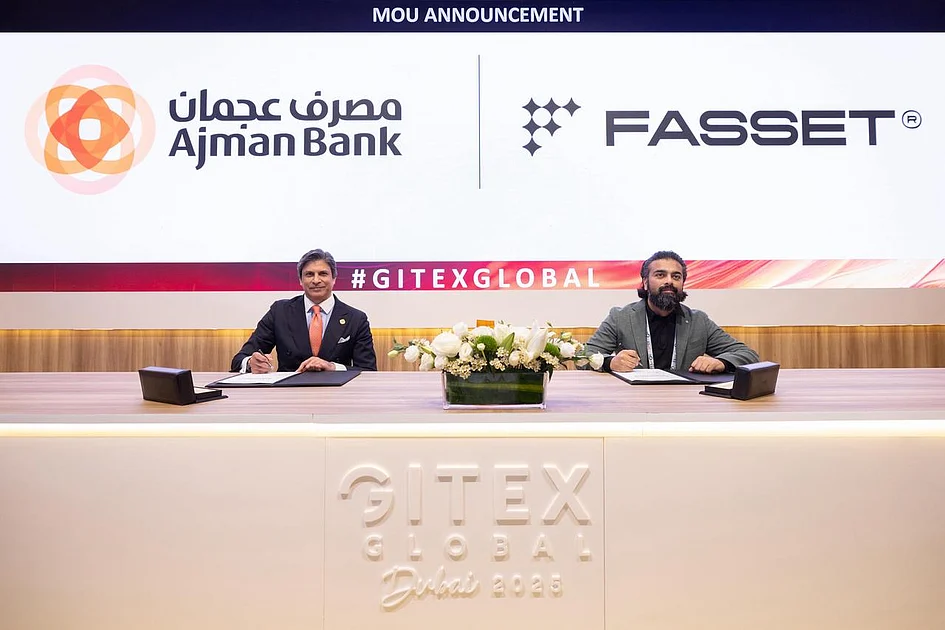
Fasset and Ajman Bank sign MoU to launch Shariah-compliant stablecoins and tokenised assets
In a groundbreaking move, Fasset, a prominent UAE-based digital asset platform, and Ajman Bank, a leading Islamic financial institution, have signed a Memorandum of Understanding (MoU) to introduce Shariah-compliant stablecoins and tokenized assets across the UAE. This collaboration marks a significant milestone in the evolution of Islamic finance, combining the reliability of a regulated Islamic bank with cutting-edge blockchain technology. Under the agreement, Ajman Bank will leverage Fasset’s comprehensive white-label solution to offer embedded digital asset capabilities to both retail and institutional clients. These offerings include access to tokenized real-world assets (RWAs) such as S&P Shariah ETFs, gold-backed financing, staking and savings products, and a private institutional trading desk. Additionally, the partnership will integrate stablecoin payment infrastructure to enhance cross-border efficiency. Fasset will develop the core infrastructure, including wallet solutions, KYC/B integrations, custody services, and regulatory compliance tools, to ensure secure and compliant operations. Mustafa Al Khalfawi, CEO of Ajman Bank, emphasized the partnership’s alignment with the institution’s values, stating that it enables customers to participate in the digital economy without compromising trust or principles. Mohammad Raafi Hossain, CEO and Co-Founder of Fasset, highlighted the collaboration’s focus on meaningful integration, embedding tokenized finance into everyday banking to make wealth creation more accessible and ethical. This partnership underscores the growing demand for compliant and inclusive digital financial products in the UAE and the broader Islamic world, paving the way for a new era in the global financial ecosystem.
-
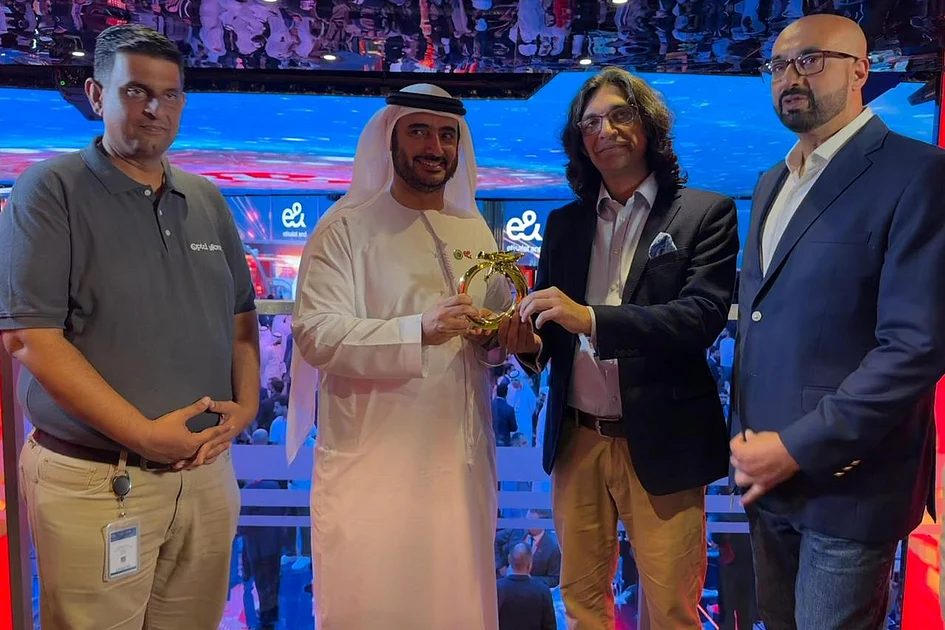
PTCL Group’s ‘Dil Se’ campaign wins gold for tackling water scarcity in Pakistan
PTCL Group’s ‘Dil Se’ campaign has been awarded the Gold Dragon Award at the Dragons of Asia awards in the Digital Campaigns category, recognizing its efforts to combat water scarcity in Pakistan. This accolade underscores the increasing importance of corporate-driven social impact initiatives in addressing critical issues like access to clean drinking water. In Pakistan, where water scarcity is a pressing concern, particularly in regions such as Thar and Southern Punjab, the ‘Dil Se’ campaign has been instrumental in providing sustainable water solutions to underserved communities. The campaign’s first phase, in collaboration with Shifa Foundation, involved the installation of water pumps in Thar, significantly improving the daily lives of nearly 15,000 residents. Many of these individuals, especially women and children, previously had to walk long distances to fetch water, which adversely affected their health, education, and livelihoods. Building on this success, PTCL Group has partnered with the Pakistan Poverty Alleviation Fund (PPAF) to launch Phase Two of the initiative. This phase aims to benefit approximately 200,000 people in water-stressed areas of Southern Punjab and Thar, making it one of the largest corporate-led clean water efforts in the country. Syed Atif Raza, Group Chief Commercial Officer at PTCL & Ufone 4G, expressed pride in the campaign’s impact, stating, ‘This platform represents our heartfelt commitment, just like its name, ‘Dil Se’. We’re proud of the difference it has made so far, but our journey doesn’t end here.’ The Dragons of Asia awards have been honoring marketing and CSR excellence across the Asia Pacific for over two decades. PTCL Group’s win not only marks a significant milestone for the company but also highlights Pakistan’s growing influence in regional social impact leadership.
-
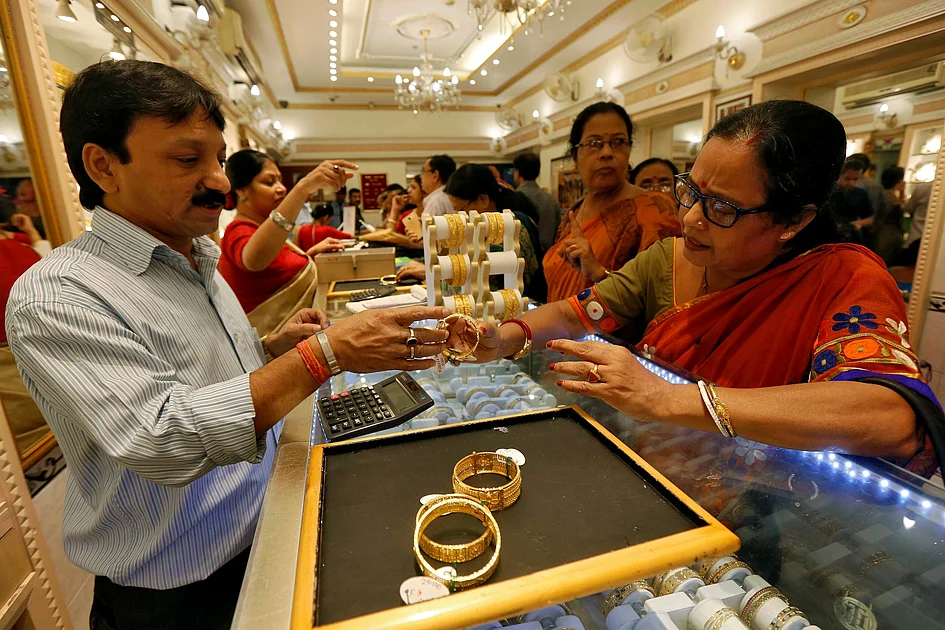
Gold shines this Diwali in UAE despite soaring prices; jewellers see strong sales
Despite skyrocketing gold prices, the UAE’s jewellery market has witnessed robust sales during the Diwali festival, driven by festive enthusiasm, strategic discounts, and innovative product offerings. Diwali, celebrated as the festival of light, symbolizes prosperity, family, and tradition, making it a prime season for gold purchases. Jewellers across the UAE have capitalized on this by launching exclusive collections and attractive offers tailored to the festive demand.
-
S&P lowers France credit rating to A+, citing risks of rising deficit
In a significant move, credit rating agency Standard & Poor’s (S&P) has downgraded France’s credit rating from AA to A+, citing heightened risks of the government failing to substantially reduce its deficit in the coming year. The decision, announced on Friday, underscores growing concerns over France’s fiscal stability and its ability to meet budgetary targets. S&P highlighted that despite the recent submission of the 2026 draft budget to parliament, uncertainty surrounding the nation’s public finances remains alarmingly high. The agency expressed skepticism about the government’s ability to achieve significant deficit reduction without additional measures, projecting a slower-than-expected fiscal consolidation over the forecast horizon. French Finance Minister Roland Lescure responded to the downgrade by reaffirming the government’s commitment to meeting the 2025 deficit target of 5.4% of GDP. He emphasized the collective responsibility of both the government and parliament to adopt a budget aligned with this framework. Separately, the finance ministry revealed that the 2026 draft budget aims to accelerate the reduction of the public deficit to 4.7% of GDP while safeguarding economic growth. This initiative is seen as a critical step toward fulfilling France’s pledge to bring the deficit below 3% of GDP by 2029. The downgrade comes amid political challenges for President Emmanuel Macron, who faces a divided parliament as he seeks to implement deep spending cuts. His new Prime Minister, Sebastien Lecornu, recently backtracked on a contentious pension reform to avoid a no-confidence vote, further complicating fiscal reforms.
-
GCC eyes slice of $2 trillion sports tourism market by 2030
The Gulf Cooperation Council (GCC) is positioning itself as a key contender in the rapidly expanding global sports tourism industry, which is forecasted to exceed $2 trillion by 2030. A recent report by PwC Middle East, titled ‘Game on for the GCC – Turning Sporting Ambition into Lasting Tourism Impact,’ highlights the region’s potential to capitalize on its increasing prominence as a host of world-class sporting events to foster a sustainable tourism economy. Currently, sports tourism represents 10% of global tourism expenditure, growing at a compound annual rate of 17.5%. The GCC’s strategic investments in sports infrastructure and events are setting the stage for substantial economic gains. Over recent years, the Middle East has successfully hosted major events such as the 2022 FIFA World Cup in Qatar and numerous Formula 1 Grand Prix weekends, significantly boosting the region’s global profile and contributing to a sports sector valued at $600 billion, with an annual growth rate of nearly 9%. Saudi Arabia is at the forefront of this initiative, with its sports market expected to triple to $22.4 billion by 2030, generating 39,000 jobs and adding $13.3 billion to the national GDP. Despite these advancements, the GCC currently captures only 5–7% of global sports tourism spending, indicating substantial growth potential. The report emphasizes the need for the GCC to transition from being a host of events to becoming a year-round destination for immersive sports experiences. Peter Daire, Senior Executive Advisor at PwC Middle East, stressed the importance of evolving beyond event hosting to create destinations that attract fans throughout the year through enriched experiences, enhanced digital engagement, and stronger regional connections. The report outlines three critical priorities for the region: developing experience-led destinations that integrate sport, retail, leisure, and culture to encourage longer stays and higher spending; fostering immersive fan engagement through digital platforms, storytelling, and multi-day festivals to turn spectators into repeat visitors; and building a connected regional ecosystem that links events and destinations across borders through streamlined travel and unified marketing. Jonathan Worsley, Chairman and CEO of The Bench, which organizes the Future Hospitality Summit, highlighted that sports tourism is now central to destination strategy and hospitality investment, driving infrastructure development, elevating brand visibility, and unlocking year-round demand. The report also advocates for increased investment in women’s sports, leisure activities, and workforce development, as well as better utilization of existing venues to extend the impact of flagship events. With over 60% of the region’s population under the age of 35, digital innovation and youth engagement are deemed crucial for shaping the future of sports tourism. As the GCC shifts its focus from hosting to experience creation, PwC suggests the region could emerge as one of the world’s most dynamic and resilient sports tourism hubs, attracting fans, athletes, and travelers who not only visit but return.