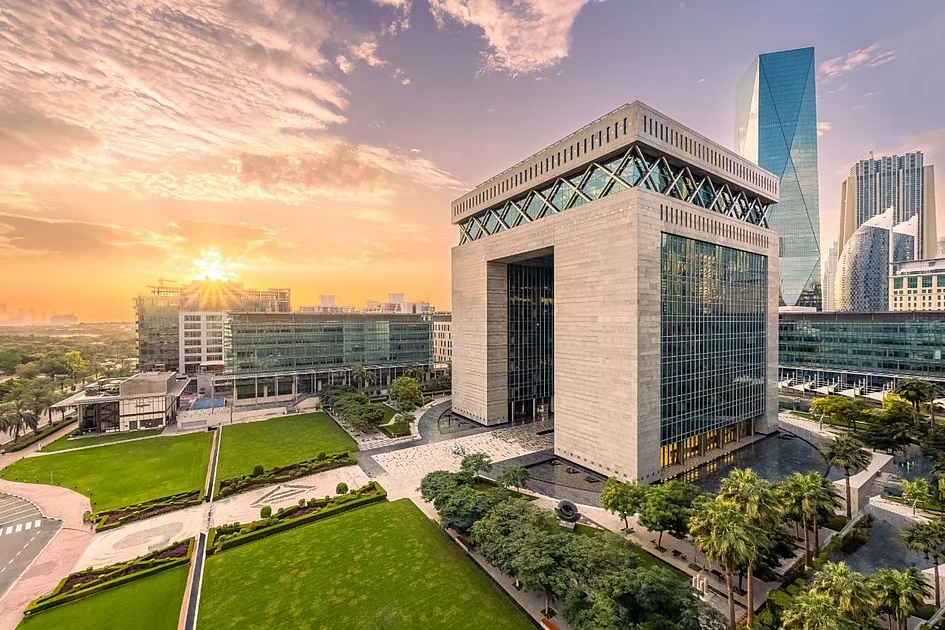
Dubai has further cemented its position as the premier financial hub for the Middle East, Africa, and South Asia (MEASA) region, with the Dubai International Financial Centre (DIFC) surpassing 8,000 active registered companies. This milestone includes over 1,000 entities regulated by the Dubai Financial Services Authority (DFSA), showcasing the Centre’s robust growth and influence. The DIFC’s banking assets have also surged to approximately $240 billion, marking a 200% increase since 2015. This achievement aligns with Dubai’s rise to 11th place in the Global Financial Centre Index, reinforcing its reputation as a top global FinTech hub and the region’s most credible financial centre. Essa Kazim, Governor of DIFC, emphasized the Centre’s pivotal role in advancing Dubai’s Economic Agenda (D33), stating, ‘DIFC’s success sets the benchmark for emerging financial centres, offering a business environment rooted in innovation, integrity, and global standards.’ Since its inception in 2004, the DIFC has attracted global financial institutions, innovators, and professional services firms, supported by its unique ecosystem of legal and regulatory certainty. Arif Amiri, CEO of DIFC Authority, highlighted the Centre’s diversity and scale, noting, ‘Exceeding 8,000 registered companies underscores DIFC’s unmatched position in the region, enabling us to shape the global financial services landscape and drive Dubai’s emergence as a technology innovation hub.’ The DFSA’s evolving regulatory framework, grounded in common law and benchmarked against global standards, continues to draw financial institutions seeking growth and connectivity. Mark Steward, Chief Executive of DFSA, remarked, ‘With over 1,000 regulated entities, DIFC is the region’s premier financial centre, connecting firms with global capital and growth opportunities.’ The DIFC Courts also reported significant activity, with over AED 17.5 billion in total claim values filed this year, reflecting growing trust in its legal framework. As Dubai expands its global influence, the DIFC remains central to its vision for the future of finance, combining scale, innovation, and regulatory excellence to support sustainable economic growth across the region and beyond.
分类: business
-
DGCX primed to lead new era of global precious metals trading
The Dubai Gold and Commodities Exchange (DGCX) is set to redefine the global precious metals trading landscape, leveraging a combination of robust market demand, regulatory support, and cutting-edge digital technologies. Established two decades ago as the region’s first derivatives exchange, DGCX has evolved into a cornerstone of the Middle East’s financial ecosystem, offering a diverse range of products, including currencies, commodities, and Sharia-compliant contracts. With gold prices surpassing $4,000 per ounce amid geopolitical uncertainty, the exchange is strategically positioned to capitalize on the precious metal’s resurgence as a safe-haven asset. The UAE Central Bank’s mandate requiring gold bullion to be stored in DMCC-approved vaults has further solidified the foundation of physical trade in the region. DGCX’s integration of AI-driven technologies enhances operational efficiency and scalability, enabling deeper liquidity, broader market access, and unparalleled physical integrity. The exchange is also introducing a dirham-denominated gold contract, designed to mitigate geopolitical risks and promote the UAE’s national currency in global trade settlements. Additionally, DGCX plans to launch a daily benchmark gold price, aligned with international standards, to provide market participants with precise pricing and hedging opportunities. The exchange’s commitment to operational excellence includes same-day or real-time settlement processes, reducing counterparty risk and improving capital efficiency. To ensure global connectivity, DGCX is exploring extended operating hours to align with key international markets, offering continuous trading opportunities across time zones. Furthermore, the exchange is democratizing gold investment through fractionalized tokenized gold and silver, allowing retail investors to participate with smaller denominations backed by physical assets. These initiatives underscore DGCX’s ambition to become a globally recognized hub for commodities and derivatives trading, driven by transparency, innovation, and stakeholder-centric strategies.
-
UAE leads in financial inclusion as digital push kicks in
The United Arab Emirates (UAE) has solidified its position as a global frontrunner in financial inclusion, driven by a robust digital transformation and strategic policy initiatives. According to the 2025 Global Financial Inclusion Index (GFII), the UAE achieved the most significant global improvement in the ‘financial-system support’ pillar, climbing five places with a 1.9-point score increase. This progress underscores the nation’s commitment to fostering a digitally inclusive financial ecosystem. The UAE also saw a remarkable leap in fintech development, rising seven spots to 14th globally, with over 320 fintech firms collectively valued at more than $3 billion. These advancements are bolstered by the UAE’s Digital Economy Strategy 2022, which has catalyzed innovation and accessibility in financial services. Access to capital surged by 16.6 points, reflecting strong momentum in SME growth and private-sector confidence. Additionally, the UAE ranks 4th globally in consumer protection, up 6.9 points, and 6th in government-provided financial education. The World Bank reports that 84.56% of UAE adults had formal financial accounts in 2021, well above the global average of 66%. The UAE Ministry of Finance and the Central Bank of the UAE (CBUAE) have jointly launched the National Financial Inclusion Strategy and National Financial Literacy Strategy, following a May 2025 policy forum in Abu Dhabi. Kamal Bhatia, President & CEO of Principal Asset Management, emphasized that the UAE’s progress transcends digital access, empowering individuals and businesses to build stronger financial futures. Pushpin Singh, Managing Economist at Cebr, highlighted the UAE’s real economic benefits, with access-to-capital scores jumping 16.6 points. Despite these strides, challenges remain, including ensuring meaningful economic participation among lower-income households and women. The UAE’s financial inclusion journey has evolved from ‘banking the unbanked’ to leveraging digital fintech platforms, regulatory frameworks, and literacy programmes to build a resilient, diversified, and inclusive economy.
-
Mbank’s millionaire campaign rewards over 7,000 prizes and a Dh1 million grand draw
Al Maryah Community Bank, the UAE’s pioneering fully integrated digital bank, has unveiled the ‘Mbank Millionaire’ campaign, a groundbreaking national savings initiative designed to foster a culture of intelligent and sustainable saving among individuals and families. This campaign, launched in anticipation of the bank’s fifth anniversary in 2026, stands as one of the most extensive savings drives in the UAE. It offers an impressive array of over 7,000 cash prizes, including 615 monthly winners who could receive up to Dh10,000 each, alongside three grand prizes of Dh100,000 each through special draws. The campaign will reach its zenith with a grand prize of Dh1 million, to be announced during the bank’s fifth-anniversary celebrations. All draws are meticulously supervised by the Abu Dhabi Department of Economic Development to ensure transparency and integrity. The initiative also seeks to inspire Al Maryah Community Bank customers to perceive saving as a rewarding and impactful habit. Customers maintaining an average monthly balance of Dh1,000 or more in their savings accounts are automatically entered into the monthly draw, with additional entries granted for every Dh100 of their average monthly balance, thereby increasing their chances of winning. Wissam Farran, Chief Intelligence & Innovation Officer of Al Maryah Community Bank, emphasized the campaign’s significance, stating, ‘As we approach five years of serving our community, this campaign is our way of acknowledging our customers who have supported our vision from the outset. Mbank Millionaire is more than a savings campaign; it’s an invitation for every individual to believe that every dirham saved today is a tangible step toward realizing tomorrow’s dreams.’
-
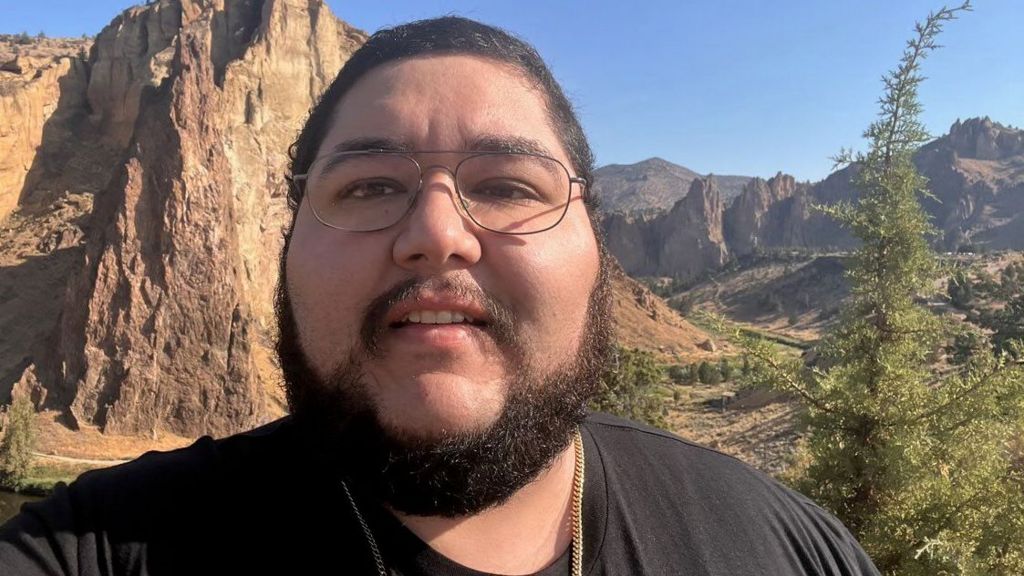
I finished building my house just before new tariffs hit
Anthony Cabrera recently completed the construction of his three-bedroom house in Hopatcong, New Jersey, just ahead of a new wave of tariffs on essential building materials and home furnishings. Starting in March, Cabrera worked diligently with a contractor to finalize his project before the tariffs took effect earlier this week. Despite his efforts, his initial budget of $300,000 surged to $450,000 due to rising costs for imported items like cabinets from Asia. ‘Tariffs were definitely on my mind throughout the whole process,’ Cabrera remarked, expressing concern over the escalating expenses. His experience mirrors the challenges faced by many homebuyers, builders, and renovators across the US. The White House argues that these tariffs aim to bolster domestic manufacturing and safeguard national security. However, economists warn that they could exacerbate the housing market’s struggles by increasing construction costs and slowing down projects. Peter Harrell, a visiting scholar at Georgetown Law School, noted, ‘The last thing an already not great new construction market needs is higher input costs.’ The new tariffs, which include a 50% levy on steel and copper imports, are part of a broader series of measures that could further inflate prices for consumers. Goldman Sachs estimates that US consumers will bear up to 55% of the cost of these tariffs this year. Furniture companies, including RH and IKEA, have already warned of potential price hikes, while smaller businesses like Jean Lin’s Manhattan-based design gallery, Colony, have seen reduced sales due to tariff-related uncertainties. The National Association of Home Builders has expressed concerns that these tariffs will create additional challenges for an already strained housing market, particularly affecting affordable housing projects. While some economists believe the tariffs alone won’t spell disaster for the industry, they acknowledge that the cumulative impact could be significant. ‘It’s yet another unwelcome thing that they have to deal with now,’ said Jake Krimmel, a senior economist at Realtor.com.
-

CFI Group celebrates the official opening of CFI Bahrain
CFI Financial Group, a prominent online trading provider in the MENA region, has officially inaugurated its newest entity, CFI Financial (Bahrain) B.S.C Closed, marking a pivotal moment in its regional expansion strategy. The launch event, held at CFI Bahrain’s Manama offices, was attended by key figures from Bahrain’s public and private sectors, as well as senior executives from CFI Financial Group. The establishment of CFI Bahrain follows the company’s receipt of a Category 2 Investment Business Firm license from the Central Bank of Bahrain (CBB) in July 2025. Yaseen Alsamerrai has been appointed as the Country CEO of CFI Bahrain, bringing extensive experience in financial services and leadership to the role. In his capacity, Alsamerrai will oversee operations and strategic growth, ensuring adherence to global standards while tailoring services to meet local market demands. Ziad Melhem, CEO of CFI Financial Group, emphasized that the launch represents more than just an expansion; it is a long-term commitment to delivering excellence, transparency, and innovation to traders in Bahrain and the broader GCC region. CFI Bahrain will provide traders with access to global markets, advanced trading platforms, and competitive conditions, backed by CFI’s global expertise. The company’s focus on financial literacy, innovation, and regulatory compliance underscores its dedication to empowering traders and supporting Bahrain’s emergence as a regional financial hub. With over 25 years of experience and a presence in key global locations, CFI continues to lead in AI-driven trading tools and financial education, further solidifying its reputation as a trusted partner for traders worldwide.
-
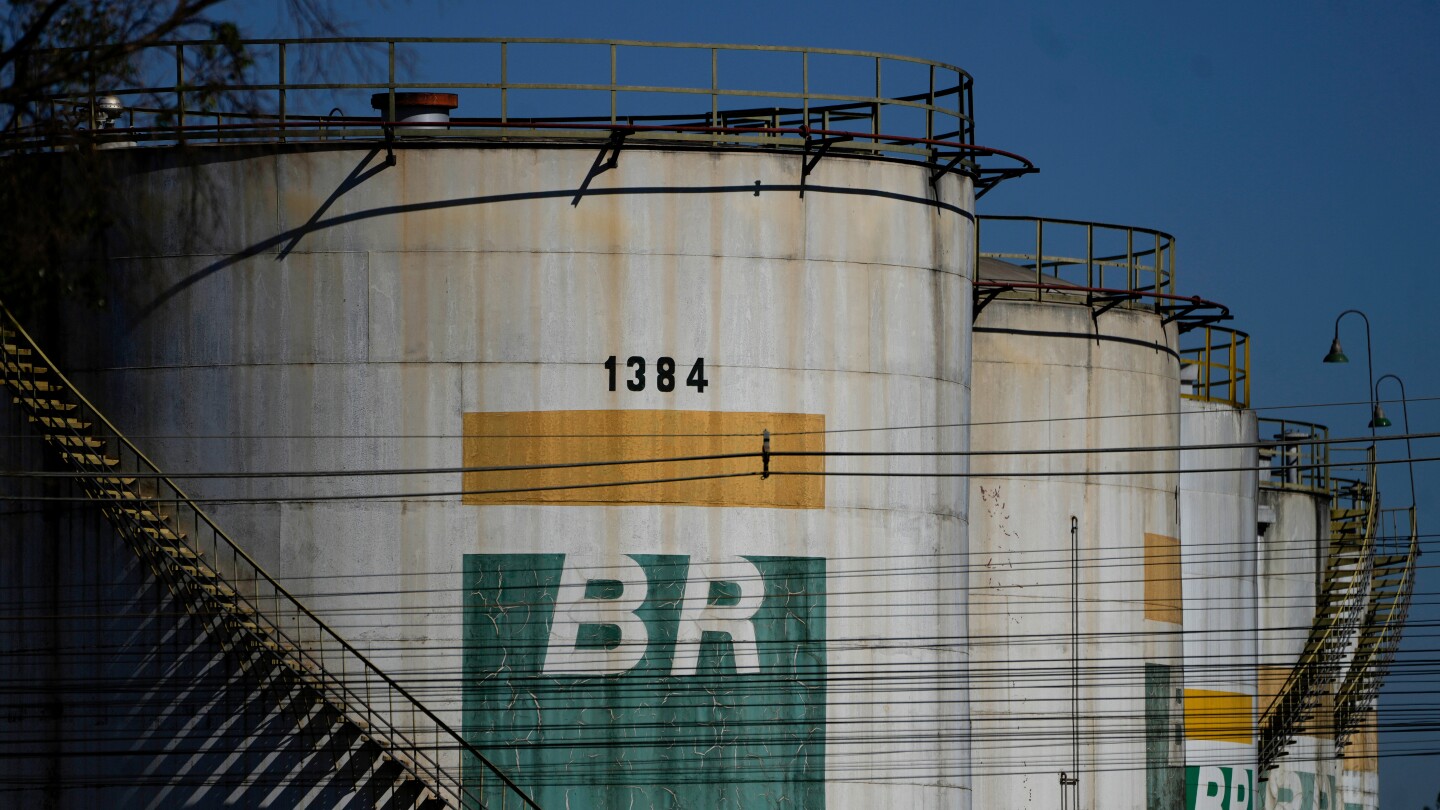
Brazil’s government green-lights oil drilling near mouth of Amazon River ahead of UN climate summit
In a significant move, Brazil’s government has greenlit exploratory drilling by Petrobras, the state-controlled oil giant, near the mouth of the Amazon River. The decision, announced on Monday, arrives just weeks before the United Nations climate conference, COP30, set to take place in Belem, where global efforts to curb fossil fuel usage will be a central topic. The Equatorial Margin, a region stretching from Brazil’s border with Suriname to its Northeast coast, is believed to hold substantial oil and gas reserves. Petrobras confirmed that drilling could commence immediately and last up to five months, targeting block FZA-M-059, located 175 kilometers offshore the northern state of Amapa. The company emphasized that this phase involves exploratory activities only, with no oil production planned. The Brazilian Institute of the Environment and Renewable Natural Resources, overseen by the environment ministry, approved the project, which was lauded by Energy Minister Alexandre Silveira. Silveira hailed the Equatorial Margin as pivotal for Brazil’s energy sovereignty, asserting that the exploration would adhere to stringent environmental standards and bring tangible benefits to the nation. This decision follows Brazil’s June auction of several oil exploration sites near the Amazon, despite opposition from environmental and Indigenous groups. The region, while promising, is also considered high-risk due to strong ocean currents and its proximity to the Amazon coastline.
-
UptexBank launches to drive digital banking innovation in the GCC
The Gulf Cooperation Council (GCC) has welcomed a groundbreaking addition to its financial landscape with the launch of UptexBank, a cutting-edge digital banking platform. Officially unveiled on October 12, 2025, during the Dubai Fintech Surge, UptexBank is poised to redefine cross-border banking by integrating advanced technology with robust regulatory compliance. Headquartered in Oman, the institution aims to streamline international transactions for individuals, freelancers, and businesses, offering multi-currency accounts and cost-effective transfer solutions. UptexBank’s launch aligns with the GCC’s Vision 2030, which emphasizes economic diversification, entrepreneurship, and digital transformation. The platform addresses a critical gap in the market, particularly for small and medium-sized enterprises (SMEs), which contribute significantly to the region’s non-oil GDP but often face challenges with traditional banking services. By providing instant transfers, transparent FX rates starting at 0.2 percent, and multi-currency accounts, UptexBank seeks to empower SMEs and freelancers across the GCC. The institution operates under regulatory licenses in Oman, the UAE, and Canada, ensuring compliance and client protection. Plans are already underway for expansion into Saudi Arabia and other GCC countries in 2026, with further international growth anticipated in 2027. Early access registration is now open for businesses and freelancers eager to join this transformative platform.
-
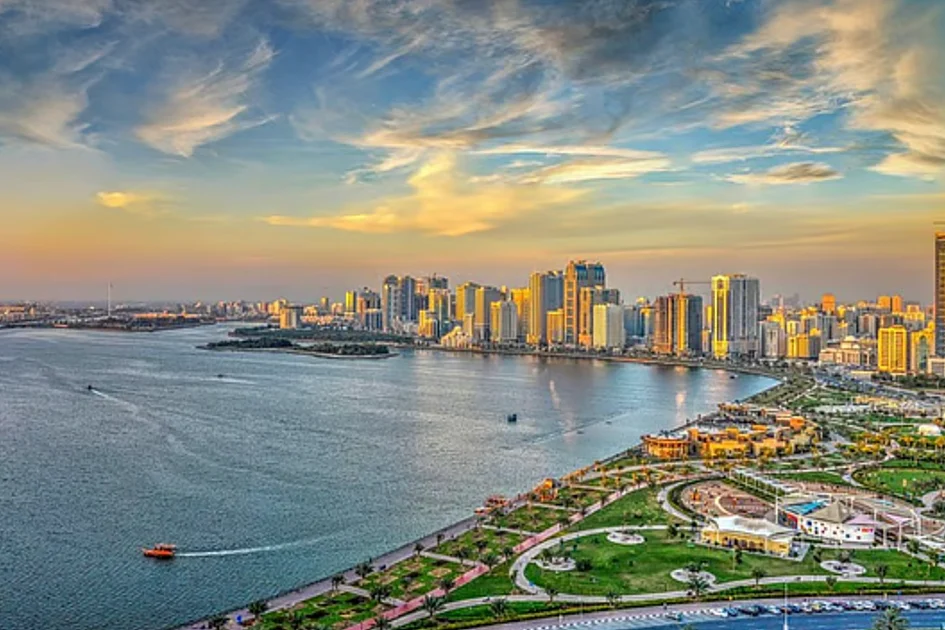
Sharjah: Property transactions for first 9 months in 2025 exceed year-total of 2024
Sharjah’s real estate sector has witnessed an unprecedented surge in 2025, with property transactions in the first nine months already surpassing the entire year’s total for 2024. Official data from the Sharjah Real Estate Registration Department (SRERD) reveals that transactions reached Dh44.3 billion, marking a remarkable 58.3% increase compared to the same period in 2024. This figure exceeds the Dh40 billion recorded for the entirety of 2024, signaling robust growth and heightened investor confidence. The number of property deals also rose significantly, with 80,320 transactions—a 16.3% increase from the previous year. Mortgage-financed purchases also saw a notable uptick, reflecting a broad-based market expansion. By mid-2025, the emirate had already recorded Dh27 billion in transactions, a 48.1% increase over H1 2024. Market segmentation highlights diverse strength, with over 24,200 sales transactions across 239 areas, covering more than 150 million sq ft of traded space. Investors from 121 nationalities participated, with Emirati nationals leading the volume at Dh21.1 billion, followed by foreign investors at Dh13.1 billion. Sharjah’s affordability, strategic regulatory reforms, and community-centric developments have been key drivers of this growth. Abdul Aziz Ahmed Al-Shamsi, SRERD’s Director-General, attributed the surge to the emirate’s solid investment infrastructure and integrated development vision. While the market’s momentum is strong, analysts caution that maintaining yields and addressing infrastructure constraints will be crucial for sustained growth.
-
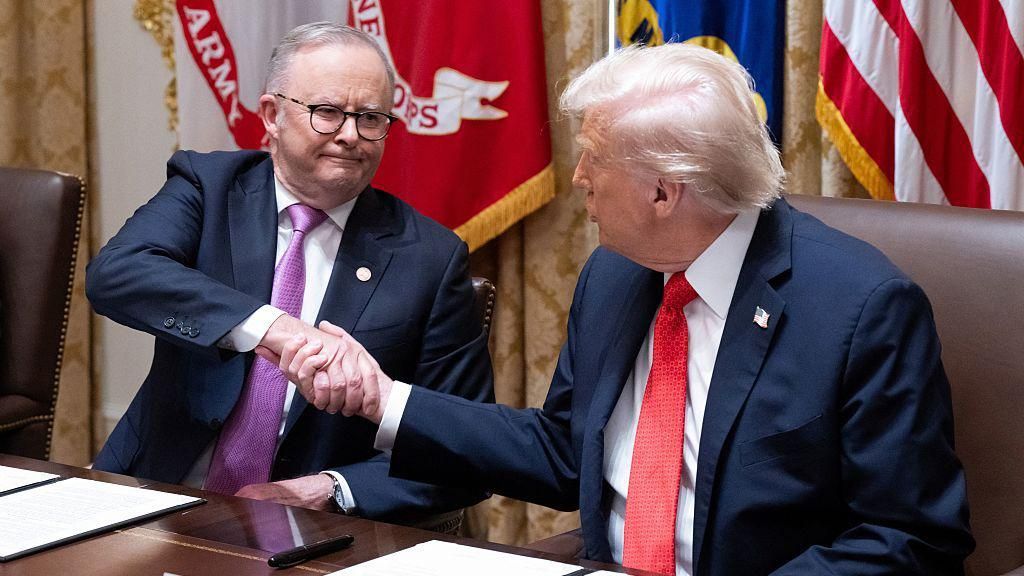
US and Australia sign rare earths deal to counter China’s dominance
In a significant move to reduce reliance on China’s control over the rare earths market, the United States and Australia have inked a landmark agreement aimed at bolstering the supply of critical minerals. The deal, announced during a high-level meeting, underscores the Trump administration’s strategic efforts to diversify global supply chains and mitigate vulnerabilities in the defense and technology sectors.