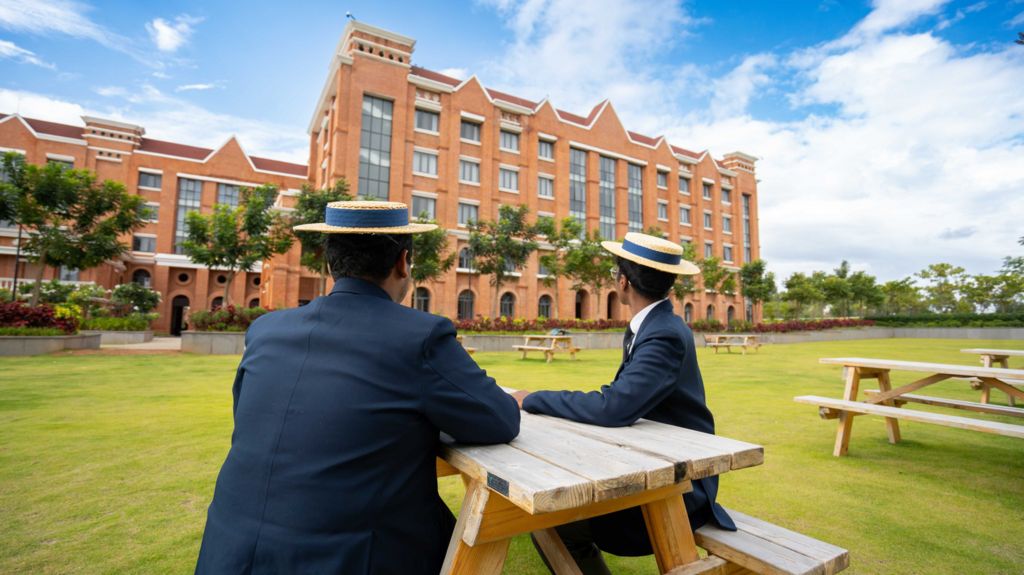
A wave of prestigious centuries-old British public private boarding schools is launching new international campuses across India, driven by shifting regulatory and market conditions in their traditional overseas expansion hubs. Earlier this year, 473-year-old Bedford School, a historic Bedfordshire institution, unveiled its first all-girls international satellite campus in Mohali, on the outskirts of Chandigarh in India’s Punjab state. Unlike the iconic Gothic central buildings that define its original UK grounds, the Mohali facility features sleek, purpose-built modern academic blocks, with a distinctive red-brick clock tower paying deliberate homage to the school’s British heritage.
Bedford is far from the only elite UK educational institution making inroads into India. At least six long-established British fee-paying private schools, including three of the UK’s oldest educational foundations, have now established locations spanning the breadth of the nation. This cohort includes Harrow School — alma mater of India’s first prime minister Jawaharlal Nehru — which opened its Bengaluru campus in 2023 in India’s Silicon Valley, a bustling hub of tech firms and startup activity. Shrewsbury School operates a site in Bhopal, central India, while Wellington College has set up operations in Pune, the western Indian city known as the “Oxford of the East” for its dense network of top-tier higher education institutions. Renowned schools including Millfield and Queen Elizabeth’s School are also in advanced stages of planning their own Indian campuses for coming years.
The expansion surge comes as external pressures reshape the global business model for UK private schools. For more than a decade, China and Hong Kong hosted roughly half of the 151 total international satellite campuses run by 50 British private schools, serving as the primary engine of their overseas growth. However, a 2025 report from UK think tank the Private Education Policy Forum (PEPF) notes that expansion in the region has slowed sharply amid tighter regulatory oversight, rising government scrutiny and public pushback against foreign-run private institutions. A 2024 national Chinese mandate requiring all schools to integrate patriotic education across every curriculum subject further disrupted operations, leading to multiple planned new campus projects being scrapped entirely. Compounding these headwinds, the UK government’s 2024 Autumn Budget introduced a new 20% VAT levy on domestic private school fees, set to take effect January 1, 2025. Naomi Atkins, founding principal of Bedford School Mohali, explains that even UK private schools that previously had no interest in international expansion are now actively pursuing overseas markets to offset domestic revenue strains, describing many institutions as being in a “desperate situation.”
India presents a uniquely attractive alternative market for these legacy schools. For generations, local elite boarding schools modelled on the British colonial public school system have served the country’s aristocratic and upper-class families, but the market has expanded exponentially in recent years as a fast-growing cohort of newly affluent Indian families prioritize global educational exposure for their children. Caroline Pascoe, head of Harrow Bengaluru, notes that the school’s all-through Cambridge curriculum — a globally recognized framework used across 10,000 institutions worldwide, spanning primary education all the way through to A-level qualifications — is a major draw for local families. Many parents, including Harsimran Singh Kocchar, a local education network operator who enrolled his 5-year-old daughter at Bedford Mohali, cite the schools’ stated focus on holistic character development, confidence building and equitable treatment of all students, free of the “VIP culture” that permeates many top-tier Indian private institutions, as key deciding factors. The student base also includes large numbers of non-resident Indians, both expats who have returned to India after long stints abroad and families still based in the UK or Middle East who want their children to maintain cultural ties to their Indian roots.
The schools work to preserve their iconic British traditions while integrating local Indian customs to resonate with their student bodies. At Harrow Bengaluru, 60% of the teaching staff are international hires, students wear the signature traditional Harrow hats and uniforms, teachers are referred to as “Beaks”, pupils take part in the global cross-country running event the Long Ducker, and the classic British house system forms the backbone of campus social life. These practices are paired with local cultural elements, including daily recitals of the Indian national anthem and celebrations of major festivals such as Ganesh Chaturthi, alongside a robust roster of extracurricular programs in music, drama and sports.
Despite these promising market conditions, operating in India has presented unforeseen challenges for the UK institutions. Almost all new campuses are launched via joint ventures with local education investors, and Atkins notes that typical revenue share margins for the British school brands have shrunk from a standard 10% in other markets to as low as 1% in some Indian partnerships. Many schools also overestimated the size of their target demographic: while India has 250 million total enrolled schoolchildren, widespread pre-existing English-language education infrastructure and a highly competitive local private school sector create far stiffer competition than in non-English-speaking markets like China, Vietnam or South Korea. India’s relatively low per capita income also limits the addressable market, as full boarding fees at top British campuses can reach £15,000 per year, a price point out of reach for the vast majority of families. Atkins notes Indian parents are far more price-sensitive than families in other Southeast Asian education markets, prompting Bedford Mohali to set its fees at roughly half the rate of competing British international schools to stay competitive.
PEPF data shows that between 2011-12 and 2022-23, British private schools’ global satellite campuses generated a combined total of £152.4 million in cumulative profits, with that figure rising steadily year over year. However, analysts and school leaders agree that growth in India will be slow and steady rather than the explosive expansion seen previously in China. While the country’s shared colonial educational heritage and fast-expanding new wealthy class create a significant long-term opportunity for the legacy British institutions, the Indian market is unlikely to fully offset the lost revenue from China for the foreseeable future.