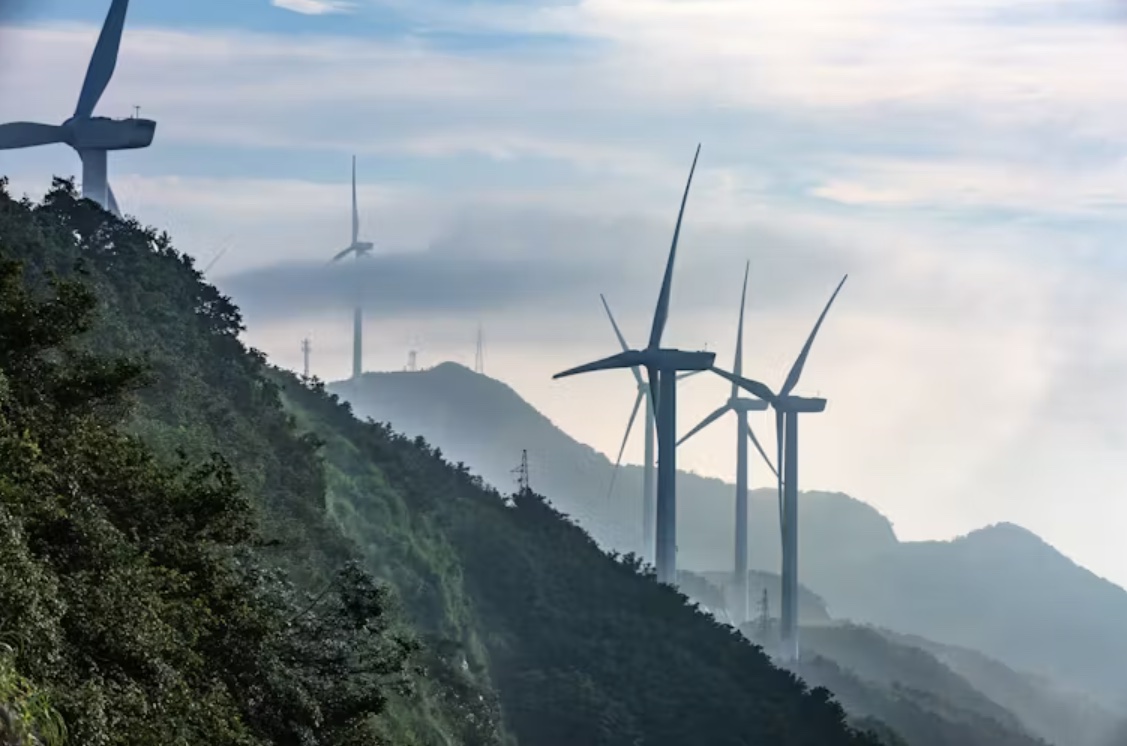
During the Cold War, the United States and the Soviet Union were engaged in a fierce competition to develop advanced technologies such as long-range missiles and satellites. Today, the global technological race has shifted to artificial intelligence (AI) and next-generation energy solutions. While the US has maintained a significant lead in AI, its position in the energy sector has been undermined by political decisions rather than technological or economic factors. Since returning to the White House in January, Donald Trump has prioritized the fossil fuel industry, rolling back support for renewable energy and appointing former industry lobbyists to key political positions. This shift has had profound implications for both domestic energy costs and the global clean energy race. The Trump administration’s policies have led to increased household energy expenses, with projections indicating a rise of $170 annually until 2035 due to the One Big Beautiful Bill Act. This legislation has stripped away incentives for renewable energy, making clean energy development more cumbersome. Meanwhile, China has surged ahead, dominating the global market for wind, solar, and next-generation batteries. China’s strategic investments in renewable energy have positioned it as a leader in electric vehicle production and solar panel manufacturing. The US, despite its potential for innovation in geothermal and battery recycling technologies, has effectively withdrawn from the competition to become the world’s 21st-century energy manufacturing powerhouse. The environmental and financial costs of Trump’s fossil fuel-centric policies are becoming increasingly evident, with climate change exacerbating natural disasters across the country. As the US grapples with rising energy costs and environmental challenges, China’s foresight in embracing renewable energy offers a stark contrast to America’s current trajectory.
分类: business
-
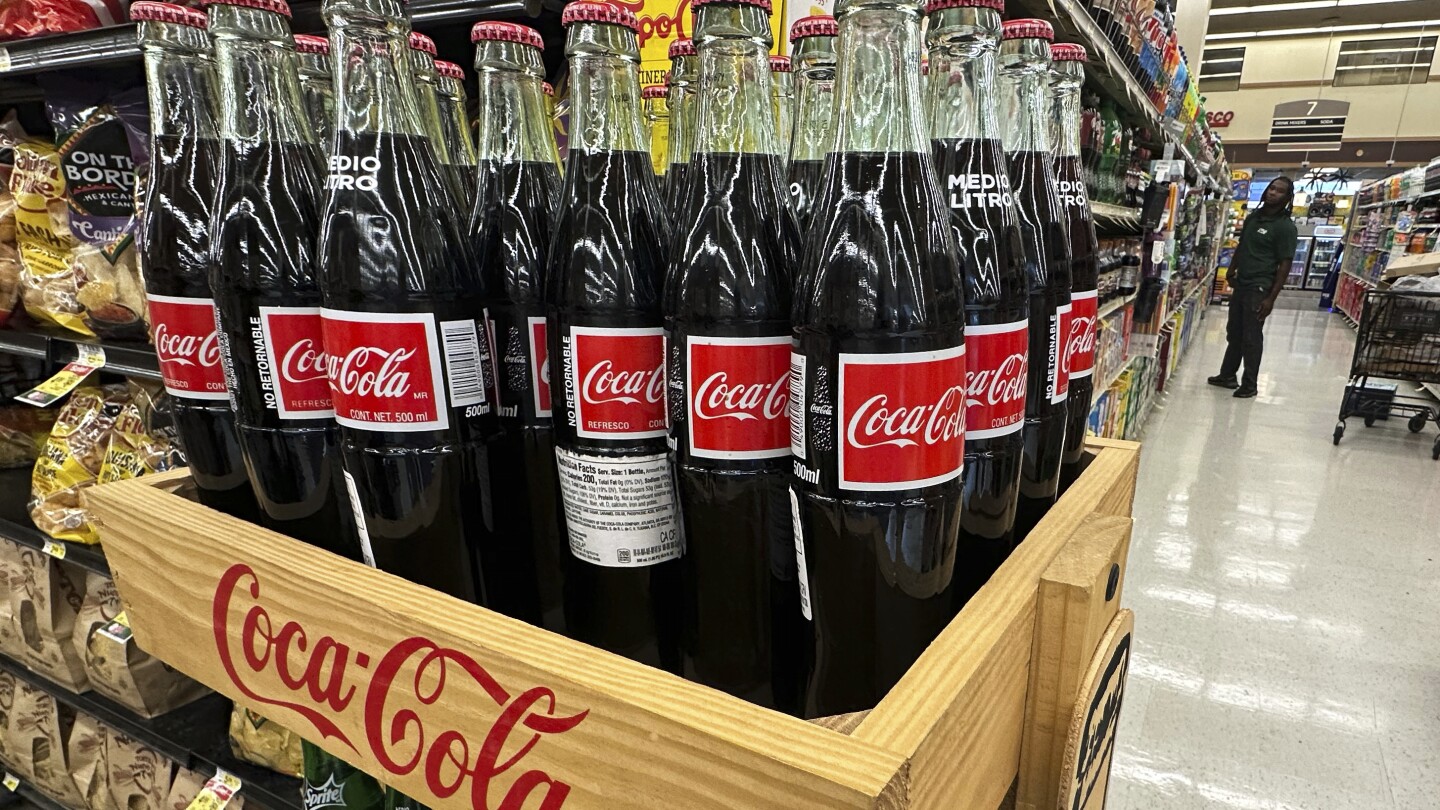
Coca-Cola confirms a cane-sugar version of its trademark cola is coming to the US
Coca-Cola announced on Tuesday that it will launch a cane-sugar version of its iconic cola in the U.S. this fall, aligning with recent remarks by former President Donald Trump. Trump had previously highlighted the company’s shift to real cane sugar in a social media post last week. This move marks a significant change for the brand, which has relied on high fructose corn syrup as its primary sweetener since the 1980s. While Coca-Cola initially remained silent on the matter, CEO James Quincey confirmed the decision during a conference call with investors, emphasizing the company’s commitment to diversifying its product offerings to meet evolving consumer demands. Quincey expressed gratitude for Trump’s enthusiasm for the brand and stated that Coca-Cola is exploring a wide range of sweetening options to cater to varied tastes. The company has already been using cane sugar in other U.S. products, such as its Simply lemonade and Honest Tea, and has sold Mexican Coca-Cola, which contains cane sugar, in the U.S. since 2005. Quincey highlighted the importance of innovation in aligning with consumer preferences, noting that the industry is experimenting with new ideas. This announcement comes as Coca-Cola faces competition from rivals like PepsiCo and Dr Pepper, which have offered cane-sugar versions of their colas since 2009. Despite challenges in certain markets, including India and Southeast Asia, Coca-Cola reported a 14% growth in case volumes for Coca-Cola Zero Sugar, reflecting a rising demand for healthier alternatives. The company also saw improved sales in North America, with Hispanic consumers returning to normal purchasing levels after a temporary decline earlier this year. Coca-Cola’s second-quarter earnings exceeded expectations, driven by a 6% global price increase, with revenue reaching $12.5 billion and net income surging 58% to $3.8 billion. The company now anticipates full-year adjusted earnings to grow by 8%, slightly below its initial forecast.
-
The corporate takeover of American housing
The 2025 US housing market presents a perplexing scenario: home sales are declining, and the number of sellers far exceeds buyers, yet prices continue to soar to unprecedented levels. Over the past decade, home values have surged nationwide, even in once-affordable Sunbelt cities. Policymakers, however, seem unprepared to address this crisis. In a July 2025 interview with the New York Times, 16 US mayors identified housing as a top concern. During her 2024 presidential campaign, former Vice President Kamala Harris proposed tax credits for first-time buyers, while President Donald Trump has renewed calls for interest rate cuts to reduce mortgage rates.
Homeownership remains a cornerstone of the American dream, with rates historically hovering around 65% from 1965 to 2025, according to Trading Economics. However, the peak was in 2004 at 69%, and despite a temporary spike during the Covid-19 pandemic, the rate has been steadily declining. Alarmingly, even among homeowners, equity is shrinking, with many owning less than half of their property’s value due to debt.
Structural issues exacerbate the crisis. Construction costs have skyrocketed, labor is scarce, and tariffs have increased material prices. Zoning laws, tax regimes, and anti-density regulations have stifled urban growth, while sprawling development faces geographic and environmental limits. Mortgage rates remain high, and the national housing shortfall, now estimated at over 4.5 million, continues to worsen.
The crisis has attracted new investors. Corporate actors are increasingly entering residential real estate, drawn by stable returns in a tightening market. Though they still own a minority of US housing, these firms are concentrated in key regions, threatening the post-World War II surge in widespread homeownership.
Large-scale corporate ownership of homes and influence over rent prices is a recent development. Before 2008, institutional investors focused on apartment buildings and urban areas, as single-family homes were seen as too dispersed and costly to manage. The housing crash changed this, with foreclosures making suburban homes available at deep discounts. Since then, major institutional financial actors have invested heavily in US single-family housing, acquiring up to 300,000 houses and renting them out.
Government-backed mortgage giant Fannie Mae began selling foreclosed homes in bulk to investors in 2012, demonstrating that single-family housing could be profitable at scale. Fannie Mae and Freddie Mac expanded support for institutional buyers through favorable financing terms and lower rates. Meanwhile, homebuilding collapsed, leading to a supply shortage.
The Covid-19 pandemic accelerated this trend. Remote work drove people from cities to suburbs, and eviction moratoriums pushed small landlords to sell, opening the door for larger buyers. Digital platforms made it easier to browse, purchase, and manage properties remotely.
Blackstone, one of the world’s largest private equity firms, became a pioneer in large-scale housing acquisitions after 2008. In 2012, it helped launch Invitation Homes, now the largest owner of single-family rentals in the US. Other major firms, like Progress Residential and Amherst Holdings, have followed suit, using advanced algorithms and AI to identify and acquire homes efficiently.
Real Estate Investment Trusts (REITs), originally designed to give everyday investors access to real estate profits, are now dominated by major institutional firms like BlackRock and Vanguard. These firms have been criticized for excessive fees, maintenance failures, and improper eviction tactics.
Corporate homebuying continues to climb. Institutional investors bought 15% of US homes for sale in the first quarter of 2021, increasing to nearly 27% by early 2025. In some markets, investors accounted for 44% of all home flips in the third quarter of 2024.
Big Tech has also become essential to the expansion of corporate housing. Tools like YieldStar, a rent pricing software developed by RealPage, use algorithms to recommend optimal prices, influencing rent markets significantly. Short-term rental platforms like Airbnb have reshaped housing, contributing to higher rents in many cities.
Addressing the issue requires public involvement and policy changes. The city of Austin is a rare success story, with median home prices falling due to increased affordable housing construction. However, without effective measures, the concentration of land in private hands will only grow, threatening affordability and public access to housing.
-
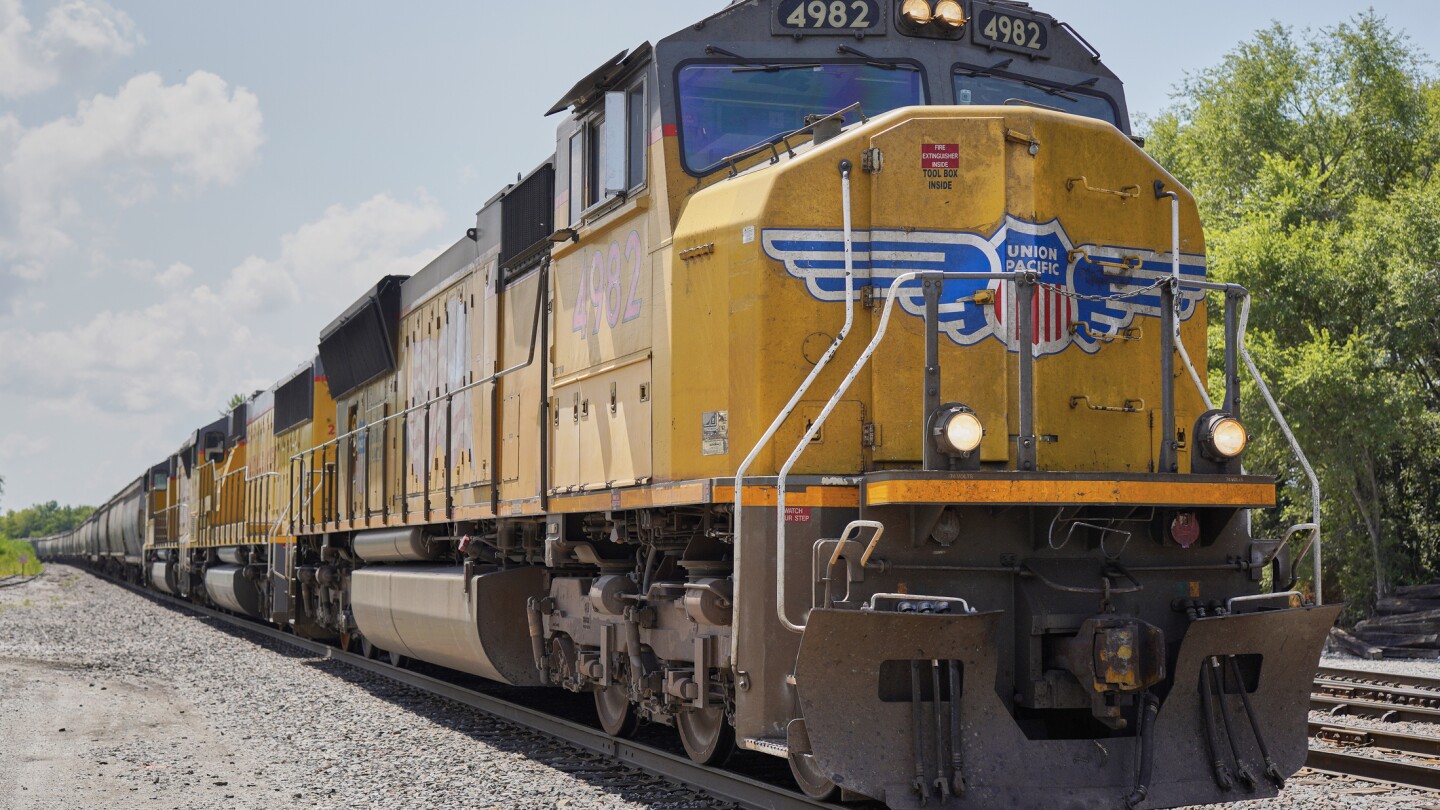
Union Pacific, Norfolk Southern discuss merger to create transcontinental railroad, AP source says
Union Pacific and Norfolk Southern are engaged in preliminary discussions to merge, potentially creating the largest railroad network in North America, spanning from the East Coast to the West Coast. These talks, which began in the first quarter of this year, involve two of the country’s six major freight railroads—Union Pacific, the largest, and Norfolk Southern, the smallest. Both companies have declined to comment on the matter. The proposed merger has sparked intense debate within the industry, particularly regarding its likelihood of approval by the Surface Transportation Board (STB). While the STB greenlit the creation of CPKC two years ago through Canadian Pacific’s $31 billion acquisition of Kansas City Southern, this would mark the first major rail merger in over two decades. The bar for such mergers was significantly raised after the problematic Union Pacific-Southern Pacific merger in 1996 and the 1999 split of Conrail, which caused widespread disruptions. Under current regulations, any major rail merger must demonstrate enhanced competition and public benefit. Union Pacific CEO Jim Vena has highlighted potential advantages, including streamlined deliveries and simplified shipping for businesses reliant on rail transport. However, concerns have been raised about reduced shipping options and the industry’s consolidation. Analysts, including Citi Research’s Ariel Rosa, warn that such a merger would face significant regulatory, political, and stakeholder pushback, making it a costly and time-intensive process. Union Pacific, headquartered in Omaha, Nebraska, reported $24.3 billion in revenue last year, while Norfolk Southern, based in Atlanta, generated $12.1 billion. Following the news, Norfolk Southern’s stock surged, reflecting investor optimism.
-
US producer prices unchanged with wholesale inflation remaining under control
In a surprising turn of events, U.S. wholesale inflation showed signs of cooling in June, despite widespread concerns that President Donald Trump’s tariffs would drive up prices for goods before they reached consumers. The Labor Department reported on Wednesday that the producer price index (PPI) remained unchanged from May, following a 0.3% increase the previous month. Year-over-year, wholesale prices rose by 2.3%, marking the smallest annual gain since September. Both figures fell short of economists’ expectations. Excluding volatile food and energy prices, core producer prices also remained flat compared to May and increased by 2.6% from June 2024. This report came a day after the Labor Department revealed that consumer prices had risen by 2.7% year-over-year in June, the largest increase since February, driven by Trump’s sweeping tariffs on goods ranging from groceries to appliances. However, consumer and producer prices do not always move in sync. Bradley Saunders, North America economist at Capital Economics, noted a 0.3% rise in core wholesale goods prices, attributing it to the impact of Trump’s tariffs. Furniture prices surged by 1% from May, while home electronics rose by 0.8%, both categories heavily reliant on imports. Interestingly, steel mill producer prices dropped by 5.5% despite Trump’s 50% tariff on imported steel. Some companies had stockpiled goods before the tariffs took effect, helping to keep prices stable, but Saunders warned that these inventories are dwindling. With new tariffs on Japanese and South Korean imports set to take effect on August 1, the situation remains precarious. Auto retailers’ profit margins also fell by 5.4%, suggesting that car dealers are absorbing the costs of Trump’s 25% tariff on imported vehicles and parts. Economists are closely monitoring wholesale prices as they provide early insights into potential consumer inflation trends. The Federal Reserve, which has been cautious this year, is also watching the inflationary impact of Trump’s trade policies. Trump’s aggressive push for rate cuts has raised concerns about the central bank’s independence.
-
‘Come meet us in Dubai’: the new offshoring of grand corruption
In a revealing 2017 interview, an African high-net-worth individual recounted being advised by a London-based executive to relocate their business dealings to Dubai. This anecdote underscores a significant yet underappreciated global trend: the migration of sensitive financial activities from traditional Western hubs to more lenient jurisdictions. This shift, driven by stricter regulations on dubious foreign funds in established financial centers, has breathed new life into corrupt practices while complicating efforts to combat them.
-
S&P 500 and Nasdaq composite pull back from their all-time highs
Wall Street experienced a modest pullback on Friday, with major U.S. stock indexes closing in the red for the week. The S&P 500 fell 0.3%, retreating from its all-time high set the previous day, while the Dow Jones Industrial Average dropped 0.6% and the Nasdaq Composite slipped 0.2%. This decline followed a week of market volatility, driven by escalating trade tensions and anticipation of the upcoming corporate earnings season. President Donald Trump’s announcement of increased tariffs on Canadian imports to 35% further strained relations with the longstanding North American ally. This move is part of the administration’s broader strategy to leverage tariff threats to secure new trade agreements globally. Despite the initial market turmoil caused by Trump’s tariff policies earlier this year, Wall Street has shown relative stability recently, with stocks reaching record highs. However, some analysts remain cautious, noting that the market’s muted response to the latest tariff escalation may not reflect underlying risks. As earnings season gains momentum, companies like Levi Strauss and PriceSmart reported strong results, boosting their shares. Meanwhile, financial and healthcare stocks weighed heavily on the market, with Visa and Gilead Sciences among the notable decliners. In other developments, T-Mobile’s shares dipped slightly after the Justice Department cleared its $4.4 billion acquisition of U.S. Cellular, and Red Cat Holdings surged following Defense Secretary Pete Hegseth’s orders to accelerate drone production. Bond yields rose, with the 10-year Treasury yield climbing to 4.42%. European and Asian markets also closed lower, while Bitcoin briefly surpassed $118,000, driven by bullish momentum and anticipation of regulatory developments during the U.S. Congress’ Crypto Week.
-
US OKs chip design software for China after a key minerals deal
In a significant development in US-China trade relations, the United States has lifted restrictions on the export of chip-making software to China, following China’s agreement to increase exports of key minerals to America. This decision, reported by Bloomberg, allows major Electronic Design Automation (EDA) software providers—Synopsys, Cadence, and Siemens—to resume operations in China, where they collectively dominate over 90% of the market. The move comes after a trade agreement signed on June 25, which was preceded by high-level meetings between US and Chinese officials in London earlier in June. The Chinese Ministry of Commerce confirmed that China would approve export applications for controlled items, while the US would reciprocate by lifting restrictive measures. US Treasury Secretary Scott Bessent expressed optimism about the increased flow of Chinese mineral and magnet exports, emphasizing the importance of rare earth magnets in the deal. Meanwhile, shares of China’s Empyrean Technology, a key chip-making software supplier for Huawei, fell by 3%, reflecting the competitive pressures in the domestic market. The trade agreement marks a de-escalation in tensions, though observers remain cautious about its long-term sustainability, given the US’s efforts to diversify its key mineral sources. Countries like India, Brazil, and Australia are emerging as alternative suppliers, potentially challenging China’s dominance in the rare earth sector. The deal underscores the complex interdependence between the two nations in critical technology and resource sectors, even as strategic competition persists.
-
Japan records trade deficit as exports suffer from Trump’s tariffs
Japan’s export sector experienced a downturn in May, primarily driven by a significant 25% drop in automobile shipments to the United States. This decline is attributed to the heightened tariffs imposed by President Donald Trump. According to the Finance Ministry, overall exports decreased by 1.7% year-on-year, a figure that, while concerning, was less severe than the anticipated decline forecasted by analysts. Concurrently, imports plummeted by 7.7%, indicative of weakening domestic demand and marking a steeper fall compared to April’s 2% decrease. The trade deficit for May stood at 637.6 billion yen, equivalent to $4.4 billion. Despite ongoing discussions, Japan has yet to secure an agreement with the U.S. to resolve the tariff issue. Prime Minister Shigeru Ishiba, following a meeting with President Trump at the Group of Seven summit in Canada, noted that the two nations remain at odds on several key points. Trump has levied a 25% tariff on Japanese automobiles and a 24% tariff on other goods, with recent statements suggesting potential increases in auto tariffs. Ishiba has underscored Japan’s role as a crucial ally in the bilateral defense alliance with Washington, emphasizing efforts to safeguard national interests. The auto industry, a cornerstone of Japan’s economy, exports over a million vehicles to the U.S. annually. Tokyo has consistently highlighted the contributions of automakers like Toyota and Honda, which manufacture vehicles in North America, bolstering the economy and generating employment.
-
The statistical truth about American stagnation
The narrative that globalization hollowed out the American middle class has been a topic of intense debate. A recent analysis challenges this notion, arguing that the timing of wage stagnation in the U.S. does not align with the era of globalization. John Lettieri of the Economic Innovation Group highlights that wage stagnation occurred primarily between 1973 and 1994, predating the North American Free Trade Agreement (NAFTA) in 1994. In fact, wages began to grow again shortly after NAFTA’s implementation. However, the story is more nuanced. While NAFTA had minimal negative effects on specific industries, the ‘China Shock’ following China’s entry into the World Trade Organization (WTO) in 2001 had a more significant impact on American wages, particularly for the working class. Between 2003 and 2015, median wages flattened, coinciding with increased competition from China. The Great Recession further exacerbated wage stagnation post-2007. Despite these factors, the most prolonged period of wage stagnation occurred before globalization, from 1973 to 1994. This era was marked by multiple economic shocks, including oil crises, inflation, and shifts in global monetary policies. Theories explaining this stagnation include productivity slowdowns, financialization, the decline of unions, and inflation. However, none of these factors alone fully account for the 20-year stagnation. The productivity slowdown, which aligns closely with the stagnation period, remains a leading explanation, though its exact causes are still debated. Other factors, such as de-unionization and financialization, played partial roles but do not fully explain the phenomenon. Ultimately, the wage stagnation of 1973-1994 may have resulted from a combination of these factors, rather than a single cause. This complex interplay underscores the challenges of isolating economic trends and highlights the need for further research to understand this pivotal period in American economic history.