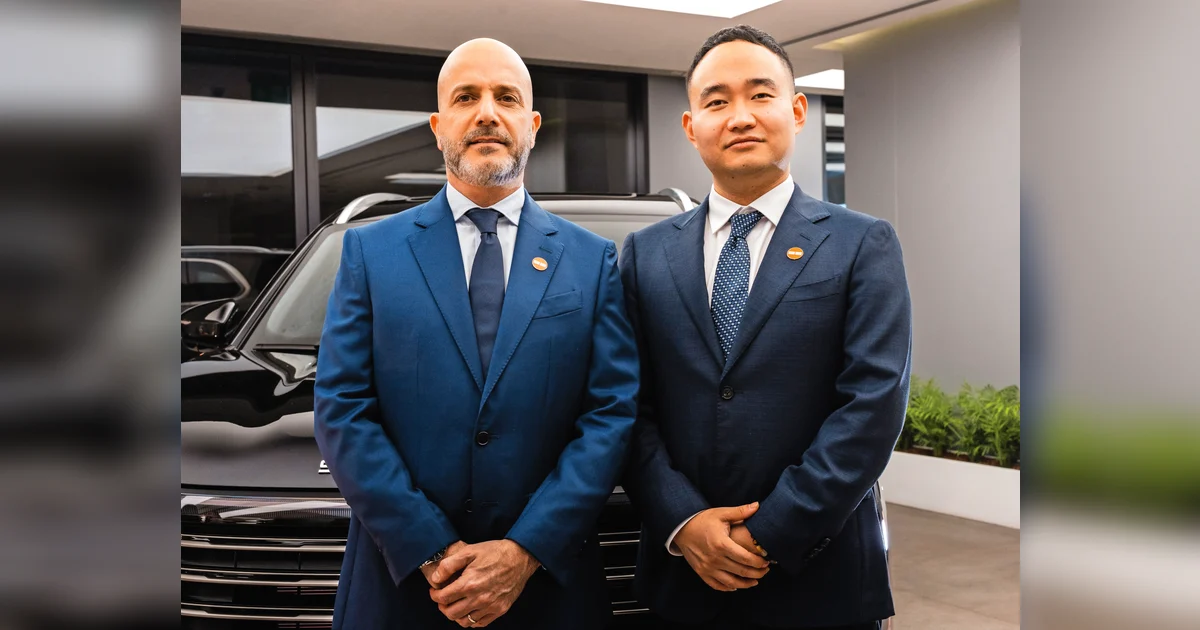
Soueast UAE, a leading Chinese automotive brand celebrated for its innovation, safety, and modern design, has unveiled its third showroom in Abu Dhabi, marking a significant milestone in its regional expansion under Elite Group Holding. The new 520-square-metre facility, which opened on September 15, 2025, showcases the brand’s full range of vehicles, including the S06, S06 DM (PHEV), S07, and S09. The showroom also features customer-centric amenities such as a café, a kids’ play area, an accessories zone, and dedicated parking. As part of the launch celebrations, Soueast UAE offered a preview of its upcoming plug-in hybrid SUV, the Soueast S08DM, set for an official release in early 2026. This seven-seater PHEV SUV boasts dual-mode technology, delivering 355 horsepower and 530NM torque. To commemorate the opening, Soueast UAE is rolling out exclusive offers and giveaways across its models, emphasizing its commitment to accessibility and value. Since its UAE debut in early 2025 under Elite Group Holding, Soueast UAE has gained momentum with its “Ease Your Life” philosophy, blending practicality, advanced technology, and modern design. The Abu Dhabi showroom serves as both a retail hub and a strategic base to expand its customer-centric approach. With plans for additional showrooms across other emirates, Soueast UAE’s growth underscores Elite Group’s dedication to reshaping the regional automotive landscape. Elie Nehme, Senior General Manager of Soueast UAE, highlighted the strategic significance of the Abu Dhabi expansion, stating, ‘This showroom reinforces our commitment to customer experience, innovation, and sustainability.’ Soueast UAE’s expansion aligns with the UAE’s broader goals of fostering innovation, environmental responsibility, and mobility transformation. With plug-in hybrid models already available and new launches planned for 2026, the brand continues to lead in delivering smart, sustainable, and accessible automotive solutions.
分类: business
-
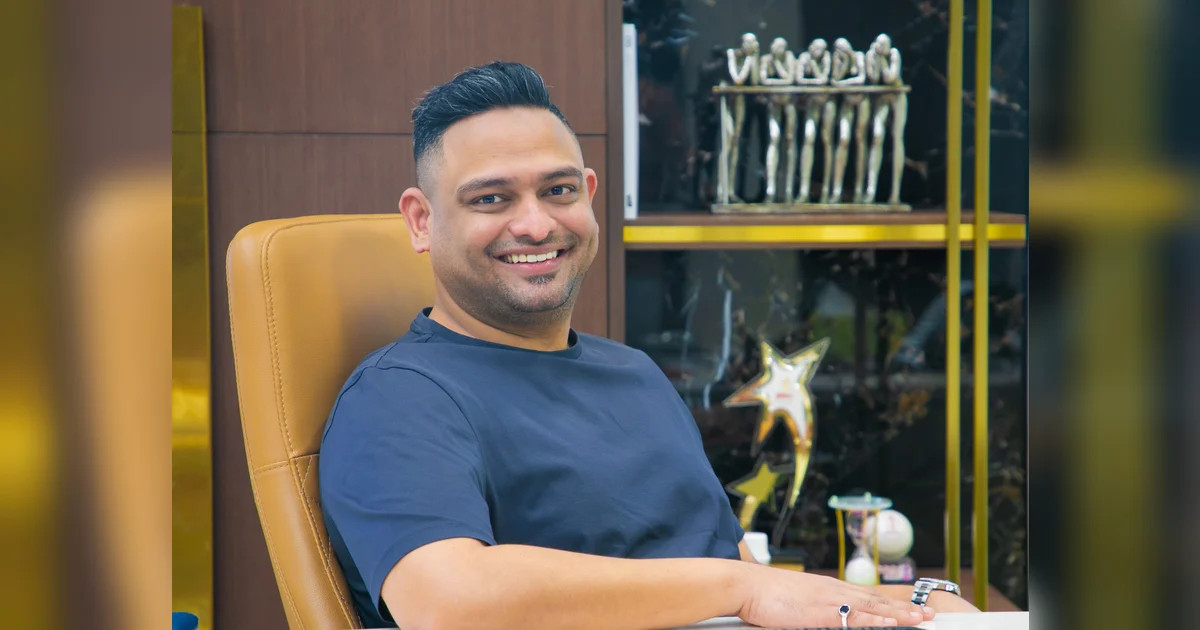
My Perfumes Group: The scent of success
The Middle East, particularly Dubai, has long been a beacon of luxury, opulence, and enchanting scents. In recent years, perfume brands from the region have captivated the global fragrance industry, blending traditional oriental richness with modern sophistication. Leading this transformative wave is My Perfumes Group, one of the UAE’s most prominent and influential perfume houses. With a legacy spanning three decades, the group has consistently redefined excellence in perfumery and packaging, earning a reputation for quality, creativity, and customer satisfaction. In an exclusive interview, Mustafa Firoz, Managing Director of My Perfumes Group, shared insights into the brand’s global expansion, its upcoming launches at Beautyworld Middle East 2025, and his vision for the future of the UAE fragrance industry. The success of Middle Eastern perfumes is rooted in the UAE’s visionary ecosystem, which fosters innovation and excellence. Stringent production laws ensure that ‘Made in UAE’ is synonymous with quality and trust. My Perfumes Group has capitalized on this foundation, offering fragrances that combine oriental mystique, premium ingredients, and competitive pricing. The group’s expertise spans the entire value chain, from manufacturing and global distribution to luxury retail, franchise operations, private labeling, and international licensing. Its portfolio includes renowned brands like Arabiyat, Otoori, and My Perfumes Select, alongside licensing partnerships with global icons such as FC Barcelona, Juventus, and Chupa Chups. With products sold in over 90 countries, the group is scaling production to meet rising demand, aiming to produce 30 million bottles by 2026. The year 2025 has been exceptional for My Perfumes, with six fragrances from its Arabiyat Prestige line going viral globally. Looking ahead, the group plans to unveil 15 new references at Beautyworld Middle East, including the highly anticipated Arabiyat Sugar collection. By 2030, My Perfumes Group aims to expand its global footprint, driven by innovation, quality, and customer trust.
-
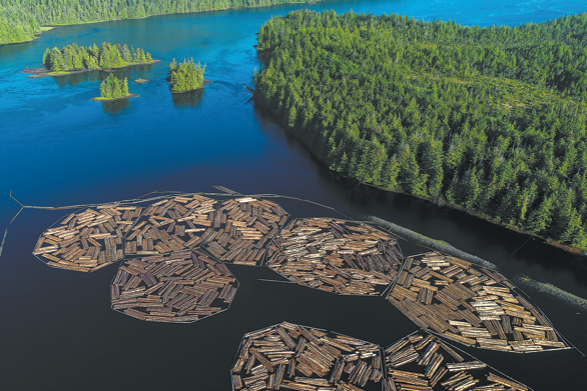
Canada’s lumber sector reels from Washington’s tariffs
Canada’s lumber sector is grappling with significant challenges following the imposition of new tariffs by the United States on timber and furniture imports. On October 14, Washington introduced a 10% tariff on imported timber and lumber, alongside a 25% duty on kitchen cabinets, in addition to the existing 35% levy on Canadian lumber. Experts warn that these measures could exacerbate price disparities and strain the already fragile trade relationship between the two nations. Harry Nelson, an associate professor of forestry at the University of British Columbia, described the combined 45% tariff on Canadian softwood as ‘unprecedented,’ predicting it could persist for at least six months. The tariffs are expected to widen the gap between domestic and export prices, with Canadian lumber prices likely to fall relative to the US market. Beyond the immediate impact on lumber, the broader North American economy could also suffer, with potential declines in housing starts and increased economic uncertainty. Industry groups, including the British Columbia Lumber Trade Council (BCLTC), have expressed deep disappointment, arguing that the tariffs will drive up costs, threaten jobs, and exacerbate the US housing supply crisis. The Canadian government has pledged C$1.2 billion in aid to softwood producers, but experts warn this may be insufficient to address the widespread effects across the interconnected sector. With the US threatening to raise tariffs further in January, pressure is mounting on Canada to negotiate a resolution. Canadian Prime Minister Mark Carney hinted at the possibility of a trade deal ahead of the upcoming APEC Economic Leaders’ Meeting, but uncertainties remain.
-
Trade cooperation continues to anchor Sino-Japanese ties
Despite the global rise in protectionism, supply chain realignments, and Japan’s political shift to the right, economic collaboration between China and Japan continues to be a cornerstone of their bilateral relationship. This was highlighted during the Beijing launch of the 2025 Blue Book of Japanese Economy, a report co-authored by the Institute of Japanese Studies at the Chinese Academy of Social Sciences and the Chinese Association for Japanese Economic Studies. The report emphasizes the enduring significance of the Chinese market for Japanese businesses, even as Japan’s foreign direct investment in China has seen a decline due to global supply chain shifts, the yen’s depreciation, and rising labor costs. According to Japan’s Finance Ministry, China ranked ninth among destinations for Japanese investment last year, with direct investment totaling 493.1 billion yen ($3.23 billion). Yang Bojiang, director of the Institute of Japanese Studies, noted that Japan’s net investment in China last year was nearly 60 percent below its 2017 peak, largely due to the relocation of manufacturing lines for U.S.-bound exports out of China to avoid tariff barriers and geopolitical risks. However, experts caution against interpreting this decline as the full picture. A survey by the Japanese Chamber of Commerce and Industry in China revealed that 56 percent of respondent companies plan to ‘increase or maintain’ investment in China this year, with 54 percent considering the Chinese market as ‘the most important’ or ‘one of the top three important markets.’ Chang Sichun, an associate researcher at the Institute of Japanese Studies, pointed out that China remains Japan’s fourth-largest destination for direct investment, following the U.S., the U.K., and the Netherlands. Japanese companies in China have consistently maintained high returns on investment, particularly in the services sector, where recent performance has been strong. The Japanese Chamber of Commerce and Industry in China reported that the return on direct investment for Japanese companies in China rose from 12.1 percent in 2015 to 18.4 percent in 2022, outperforming returns in the U.S. (8.8 percent) and the U.K. (14.7 percent). This strong performance has led to a rebound, with China’s Commerce Ministry reporting a 58.9 percent year-on-year increase in actual investment from Japan in the first eight months of this year. Yang also highlighted China’s modernization achievements as a key attraction for Japanese businesses, noting growing appreciation in Japan for China’s path to modernization, particularly in areas like poverty reduction and the digital economy. However, experts warned of potential uncertainties arising from Japan’s increasingly rightward political shift, which could suppress Japanese investment in China, particularly in high-tech sectors. Despite these challenges, the significant presence of Japanese companies in China and their substantial accumulated investment form an important channel for stabilizing bilateral relations. Strengthening bilateral exchanges and ensuring the healthy development of China-Japan relations not only serves the fundamental interests of both countries but also contributes to regional prosperity and global economic recovery.
-
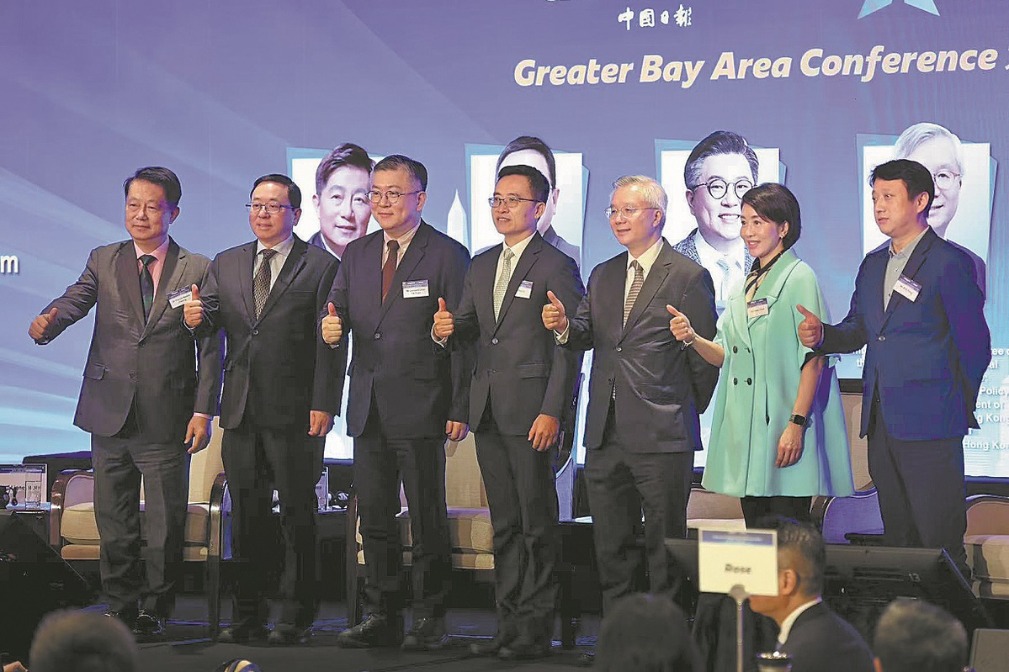
HK to spur growth of Greater Bay Area
Hong Kong is set to play a pivotal role in accelerating the integrated development of the Guangdong-Hong Kong-Macao Greater Bay Area, leveraging its unique position as a ‘super-connector’ to foster the flow of goods, capital, and talent. This was the central theme of the Greater Bay Area Conference 2025, co-organized by China Daily and the Hong Kong Coalition, which brought together over 300 industry leaders, policymakers, and experts to discuss the region’s future.
-
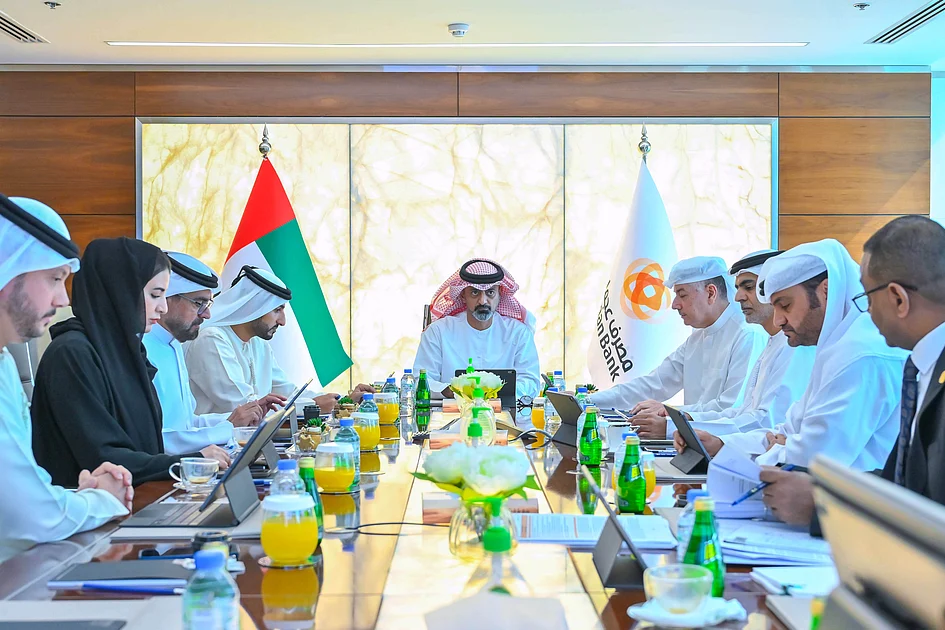
Ajman Bank posts 32% surge in profit before tax for first nine months of 2025
Ajman Bank has announced a remarkable financial performance for the first nine months of 2025, with profit before tax soaring by 32% year-on-year to Dh414 million. This impressive growth underscores the bank’s operational strength and strategic focus on sustainable development. The results were reviewed during a Board of Directors meeting led by Sheikh Ammar bin Humaid Al Nuaimi, Crown Prince of Ajman and Chairman of Ajman Bank. Profit after tax also saw a substantial increase, rising 31% to Dh380 million. Total operating income reached Dh1.2 billion, while net operating income stood at Dh660 million, reflecting robust performance across the bank’s core business segments. Ajman Bank’s total assets grew by 23% since the end of 2024, reaching Dh28.0 billion, driven by a 20% increase in total financing to Dh18.5 billion. Customer deposits rose 14% to Dh20.6 billion, and shareholders’ equity increased 8% to Dh3.4 billion, highlighting the bank’s stable funding base and balance sheet expansion. Key financial metrics also improved, with Return on Equity (ROE) rising to 15.6% and Return on Assets (ROA) improving to 2.0%. The bank’s asset quality strengthened significantly, with the Non-Performing Loans (NPL) Ratio dropping to 7.7% and the Real Estate Ratio declining to 31.9%. Mustafa Al Khalfawi, CEO of Ajman Bank, emphasized the bank’s commitment to enhancing efficiency, optimizing its balance sheet, and expanding its digital ecosystem to drive sustainable growth. The bank also reaffirmed its dedication to Ajman Vision 2030 and the UAE’s broader economic transformation goals, including its Dh4 billion Sustainable Finance pledge by 2030 and Net Zero Emission target by 2050.
-
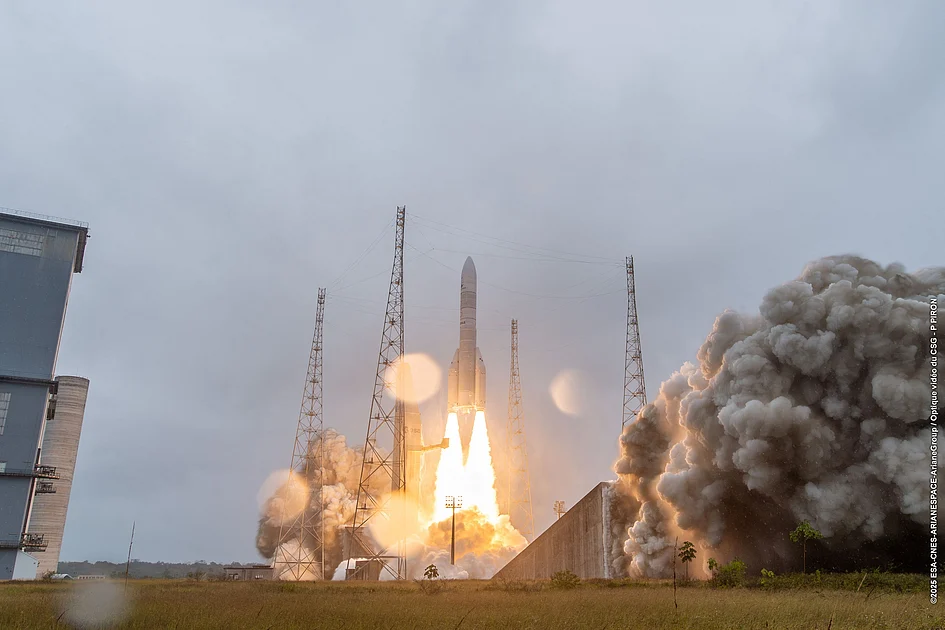
Europe aerospace firms team up in space to counter Musk
In a landmark move to counter the growing influence of Elon Musk’s Starlink, Europe’s leading aerospace companies—Airbus, Thales, and Leonardo—have announced a preliminary agreement to merge their satellite manufacturing and services operations. The new France-based venture, set to launch in 2027, marks the most significant consolidation of European aerospace assets since the formation of MBDA, the missile manufacturer, in 2001. The collaboration, codenamed ‘Project Bromo,’ aims to create a formidable competitor in the global space industry. The combined entity is projected to employ 25,000 people and generate €6.5 billion ($7.58 billion) in revenue, based on 2024 figures. The venture is expected to yield ‘mid-triple digit’ millions of euros in synergies within five years, though specific strategies remain undisclosed. French Finance Minister Roland Lescure emphasized that the deal would ‘strengthen European sovereignty in a context of intense global competition.’ The agreement comes after months of negotiations, overcoming hurdles related to governance and valuation. Airbus will hold a 35% stake, with Thales and Leonardo each retaining 32.5%, ensuring a balanced governance structure. The merger will integrate Thales Alenia Space, Telespazio, and various Airbus space and digital businesses, alongside remaining space activities of Leonardo and Thales SESO. While the companies have already reduced 3,000 jobs in their space divisions, executives have shifted focus to potential growth opportunities. The deal faces up to two years of discussions with governments, unions, and the European Commission, with implications for operations in Britain, Germany, Italy, and France. Thales CFO Pascal Bouchiat acknowledged the challenges ahead, particularly in the telecoms sector, despite securing an initial contract for the new European satellite network, IRIS². The announcement follows Reuters’ earlier report of a framework agreement, which was salvaged after overcoming governance disputes. Executives have pledged to avoid rotating leadership or nationality-based appointments, which have historically caused friction in the European aerospace industry.
-
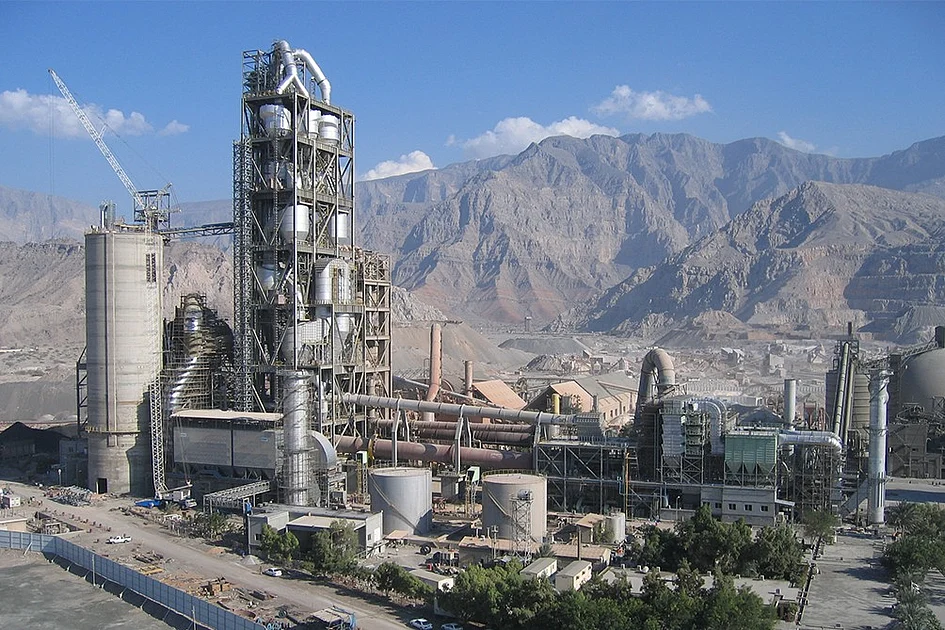
Gulf Cement Company joins Buzzi, marking a new era of industrial excellence in the UAE
In a landmark development for the UAE’s industrial sector, Gulf Cement Company (GCC), a pivotal player in the region’s infrastructure for nearly 50 years, has officially become part of Buzzi, the Italian global leader in cement and heavy construction materials. This strategic integration was commemorated with a ribbon-cutting ceremony at The Waldorf Astoria Ras Al Khaimah, attended by top executives from both organizations, including Pietro Buzzi, CEO of Buzzi SpA, and José B. Sena, CEO and Managing Director of GCC, alongside regional stakeholders and dignitaries. The event symbolizes a transformative phase for GCC, emphasizing its dedication to innovation, sustainability, and global competitiveness. Established in 1977, GCC has been instrumental in the UAE’s infrastructure growth, producing premium cement products and spearheading environmental initiatives like waste heat recovery systems and carbon emission reduction programs. By joining forces with Buzzi, GCC aims to harness global expertise, advanced technologies, and strategic insights to enhance operational efficiency and expand its reach in international markets. Pietro Buzzi remarked, ‘This integration transcends a mere business deal; it reflects a shared vision of innovation and long-term growth.’ José B. Sena added, ‘This partnership marks a pivotal moment for GCC, blending international expertise with regional strength to drive industrial excellence.’ The move also highlights Buzzi’s commitment to bolstering its presence in the Middle East, a rapidly growing hub for construction and infrastructure development.
-
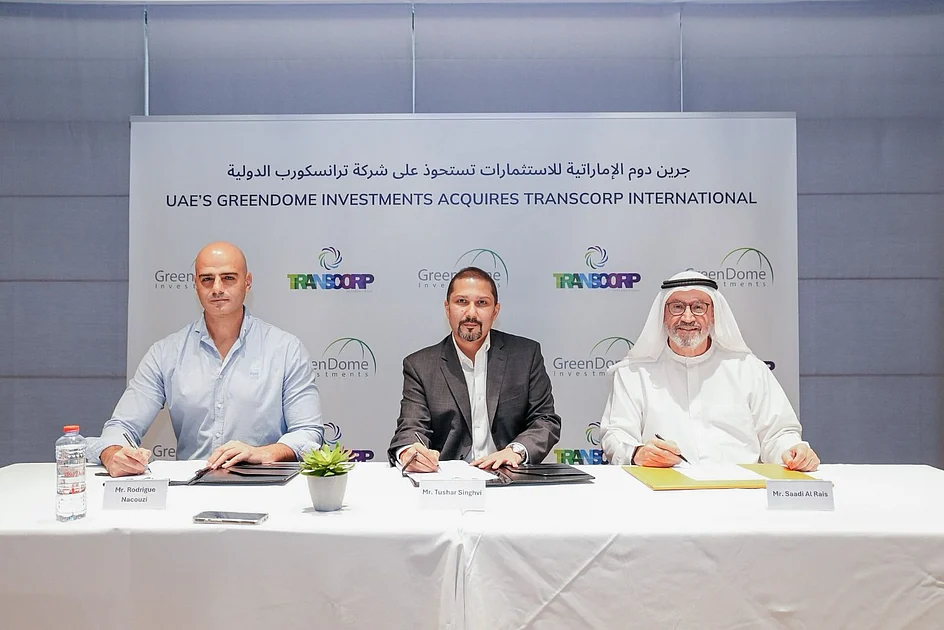
CE-Ventures announces strategic exit from Transcorp
CE-Ventures, the corporate venture capital arm of Crescent Enterprises, has announced the successful divestment of its equity stake in Transcorp, a UAE-based logistics and fulfilment company. The strategic sale to Elite Co, a leading regional operator supported by Green Dome Investments, has yielded a remarkable 7.6x multiple on invested capital (MOIC), marking one of the most lucrative exits in the region across all sectors. CE-Ventures initially invested in Transcorp in 2018, playing a pivotal role in transforming the company into a dominant player in cold-chain fulfilment, last-mile delivery, and B2B distribution. Over the years, CE-Ventures collaborated closely with Transcorp’s leadership to institutionalise governance, enhance internal systems, and unlock strategic growth opportunities. Tushar Singhvi, Deputy CEO & Head of Investments at Crescent Enterprises, expressed pride in supporting Transcorp’s evolution into a scalable, institutional-grade logistics company. Rodrigue Nacouzi, CEO and founder of Transcorp, praised CE-Ventures as a strategic partner that contributed significantly to the company’s growth. Sudarshan Pareek, Senior Vice President at CE-Ventures, highlighted the firm’s philosophy of backing mission-driven founders in sectors where operational excellence is key. Hisham Albahar, CEO of Elite Co, emphasised Transcorp’s market-leading position in cold-chain logistics and its strategic importance in Elite Co’s regional expansion. This transaction underscores Crescent Enterprises’ strategy of fostering resilient, high-impact businesses while driving sector consolidation. It also aligns with Elite Co’s broader expansion plans under Green Dome Investments, which aims to consolidate logistics and supply chain assets across the GCC.
-
Dubai Golden Visa attracts new wave of property buyers
Dubai’s Golden Visa policy, which offers a 10-year renewable residency to property investors committing at least Dh2 million, has significantly reshaped the emirate’s real estate landscape. The streamlined eligibility criteria, which eliminated the previous Dh1 million or 50% down payment requirement, have positioned Dubai as a dual hub for investment and lifestyle. According to Rebiha Helimi, CEO and Founder of RH Luxury Properties, this policy has become a pivotal factor in attracting global wealth and reshaping investor behavior in 2025. Data from the Dubai Land Department reveals a 36% increase in real estate transaction volume and a 20% rise in value in 2024, totaling Dh761 billion. In the first half of 2025 alone, transactions surged by 26%, with off-plan projects accounting for nearly 70% of deals. Premium residential prices have also climbed, with villas averaging Dh2,088 per square meter. Helimi highlights that many clients now view visa processing and property acquisition as integral components of a strategic plan to leverage Dubai’s offerings. The policy has not only boosted liquidity in the luxury segment but also attracted long-term investors seeking profitability in a politically neutral jurisdiction. Analysts predict that around 9,800 millionaires will relocate to the UAE in 2025, bringing an estimated USD 63 billion in investable wealth. This migration is fueling Dubai’s high-end housing market, reinforcing its global appeal as a hub for asset diversification amid global economic uncertainties.